


EN
Spyre Therapeutics (SYRE) After UEGW 2026 Buzz, Is Its Valuation Already Priced In?
Event driven focus on Spyre Therapeutics valuation
Spyre Therapeutics (SYRE) is back in focus as investors position ahead of clinical and preclinical data presentations on its inflammatory bowel disease antibody programs at UEGW 2026, with enthusiasm reflected in an elevated price to book ratio.
Recent trading in Spyre Therapeutics has been choppy, with a 13.05% 7 day share price return giving way to a 2.17% drop in the last session and a 30 day gain of 2.45%. Over 90 days the share price return is down 11.55%, and the year to date share price move of 195.39% sits alongside a very large 3 year total shareholder return of about 7x. This suggests that enthusiasm around the upcoming UEGW 2026 data is layered onto already strong longer term momentum rather than arising from a fresh rerating from a low base.
Scan 34 healthcare AI stocks, similar to Spyre Therapeutics ahead of its UEGW 2026 catalysts, that are already pricing in big expectations around clinical data and future pipelines.
Spyre Therapeutics has already delivered a very large multi year gain, yet investors are still paying a rich multiple ahead of UEGW 2026. How much of the potential reward now sits in the rear view mirror versus still on the table?
Most Popular Narrative: 25% Undervalued
On the most followed view, Spyre Therapeutics is worth about $120 per share, which sits well above the last close around $90, so the current valuation leans heavily on how its IBD and autoimmune pipeline converts into future earnings.
The main requirement for this strategy is successful execution of the SKYLINE and SKYWAY trials so that TL1A and co formulated antibody combinations in IBD and rheumatic diseases demonstrate sufficient additive efficacy to support potential first line use, despite earlier RA de prioritisation and licensing constraints on SPY003.
See why 2 investors see Spyre Therapeutics as 25% undervalued.
Using a 7.46% discount rate, that narrative ties a fair value of $120.08 to expectations that Spyre Therapeutics can eventually move from zero revenue today to $28.9 million by 2029, with margins stepping up over time from deep losses toward sector averages and a very high implied 3,226.5x P/E on those projected earnings.
The same storyline leans on a large cash balance of about $1.1b that is expected to fund current Phase 2 work and some Phase 3 activity into the second half of 2029, together with a broad set of TL1A, IL 23 and a4ß7 programs across SKYLINE and SKYWAY that could, if successful, support a wider range of reimbursed autoimmune uses and justify the elevated multiple investors are paying today.
That leaves the share price highly sensitive to clinical readouts and to any shift in confidence around execution, especially given the history of insider selling in 2026, forecast losses over at least the next three years, and a very demanding multiple that already assumes meaningful future revenue and margin progress.
Result: Fair Value of $120.08 (UNDERVALUED)
Still, the bullish Spyre Therapeutics narrative could crack if TL1A or combination data underwhelm in key trials, or if further insider selling pressures sentiment again.
Find out about the key risks to this Spyre Therapeutics narrative.
Another View: Spyre Therapeutics through its P/B premium
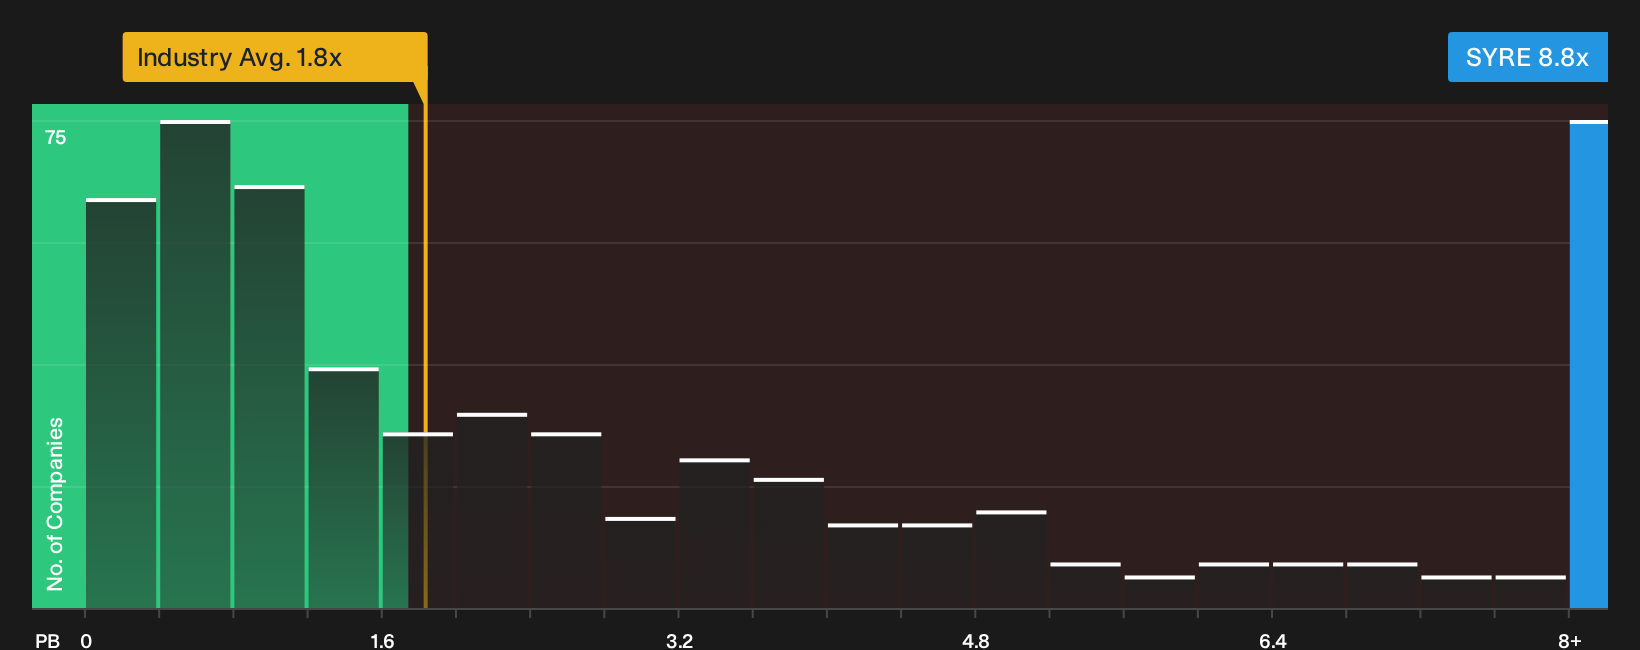
The first story paints Spyre Therapeutics as about 25% undervalued, yet the share price already trades on a P/B of 8.8x versus 1.9x for the wider US Biotechs group and 10.3x across close peers. That rich book multiple loads a lot of expectation into a business with no current revenue.
This gap does not prove the analysts are wrong, but it does mean anyone buying in today is paying a premium for potential rather than current earnings. The real question is whether you are comfortable underwriting that kind of valuation risk while clinical and regulatory hurdles are still ahead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Spyre Therapeutics story pulls in opposite directions, with excitement and worry both visible in the numbers. Act quickly, review the data for yourself, then weigh the 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond Spyre Therapeutics?
Do not stop with Spyre Therapeutics when the real edge often comes from lining up a few strong, well researched ideas across different parts of the market.
- Target stability by reviewing companies with resilient balance sheets and consistent fundamentals in the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities that combine quality with attractive valuations using the 27 high quality undervalued stocks.
- Build a more defensive core by focusing on reliable income streams screened through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com