


EN
Why Takeuchi Mfg (TSE:6432) Is Back In The Spotlight
Takeuchi Mfg (TSE:6432) has come into focus after management raised full year earnings guidance, lifted dividend plans, and approved a sizeable share repurchase program aimed at returning surplus capital to investors.
Recent trading has been strong, with a 1 month share price return of 9.75% and a year to date share price gain of 16.98% at a current level of ¥7,990, as investors react to Takeuchi Mfg’s upgraded guidance, richer dividend outlook, and the newly approved buyback. Over a longer horizon, total shareholder return of 33.14% over 1 year and 223.74% over 5 years signals momentum that has been building rather than fading, which helps frame the latest capital return moves as part of a broader rerating by the market.
Spot other construction and capital goods stocks where management is also putting cash back in investors’ pockets by focusing on 29 dividend fortresses in this income focused list. Takeuchi Mfg now pairs upgraded guidance, richer dividends, and a new buyback with a long run of strong returns. The tougher call is whether that quality is already fully reflected in the current share price.Price-to-Earnings of 12.6x: Is it justified for Takeuchi Mfg?
On a P/E of 12.6x, Takeuchi Mfg trades slightly richer than both the Japanese machinery sector and its immediate peer group, even after a strong share price run to ¥7,990.
The P/E ratio compares what investors pay today for each unit of current earnings. For an equipment manufacturer like Takeuchi Mfg, which operates in a cyclical capital goods field, that earnings multiple often reflects how confident the market feels about the durability of profits through future cycles.
Earnings have grown 17.5% per year over the past 5 years, but the most recent 12 month growth rate of 11.5% trails that longer run pace and also lags the wider machinery industry figure of 26%. That slower recent profit expansion, together with a Return on Equity of 14.8% that is flagged as low against a 20% benchmark, suggests the current P/E asks investors to pay up for quality and capital returns rather than for superior growth momentum.
The premium is also clear in comparisons. The 12.6x P/E is marked as expensive versus the Japanese machinery industry average of 12.5x and sits well above the peer average of 7.4x. This implies the market is putting a higher price on Takeuchi Mfg's earnings stream than on similar stocks. Yet against an estimated fair P/E of 13.9x, the current ratio is assessed as good value and the gap points to a level the market could move towards if investor confidence in the earnings profile is maintained.
Explore the SWS fair ratio for Takeuchi Mfg.
Result: Price-to-Earnings of 12.6x (ABOUT RIGHT)
Still, if earnings momentum or the 7.2% annual revenue growth rate were to weaken, the current value score of 2 could start to look demanding.
Find out about the key risks to this Takeuchi Mfg narrative.
Another View on Takeuchi Mfg’s Value
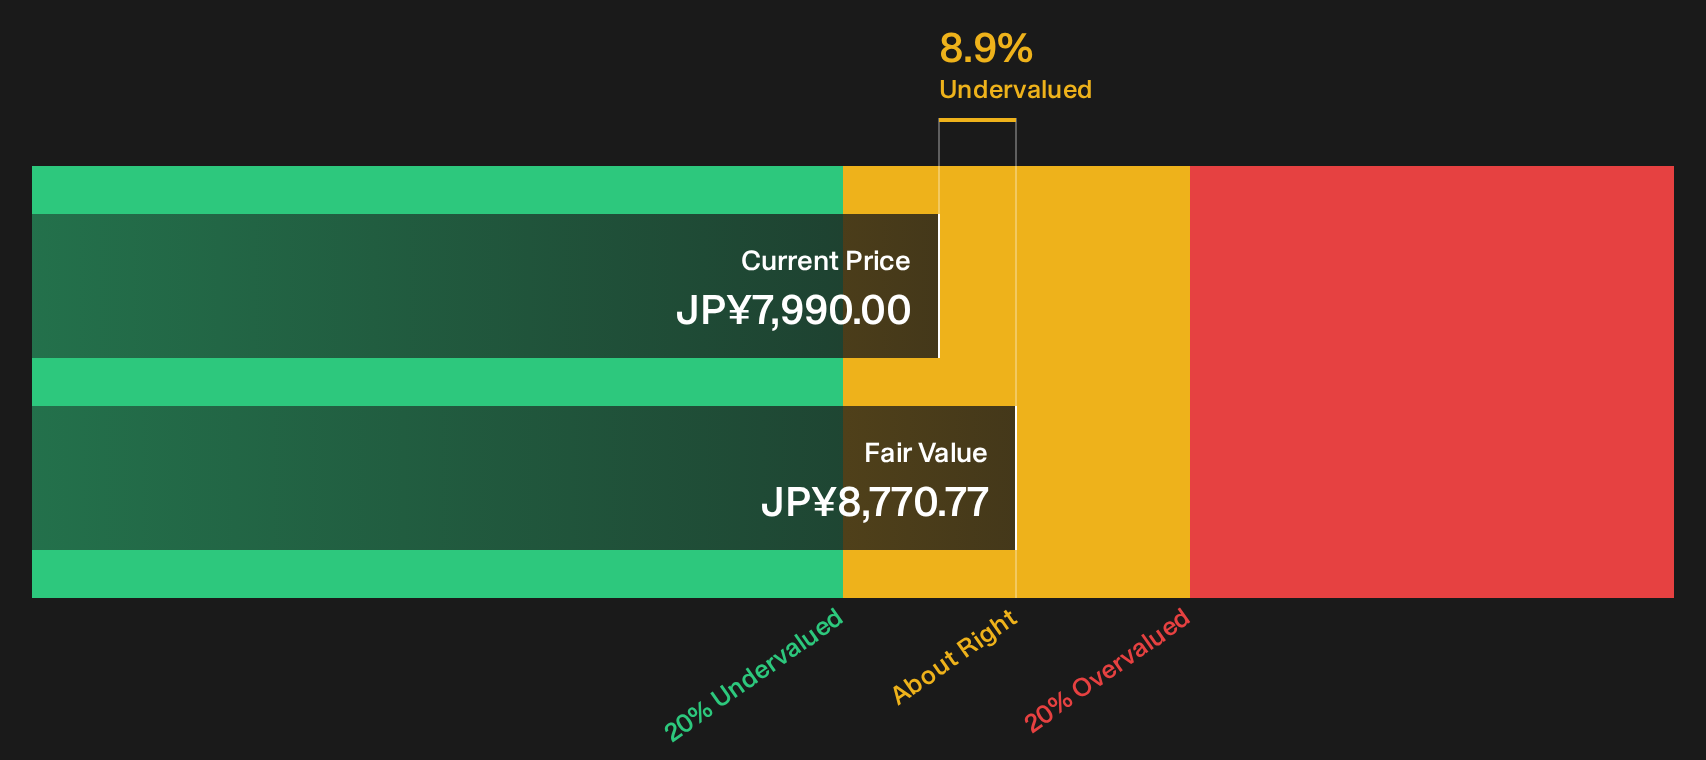
The first check on Takeuchi Mfg focused on its P/E of 12.6x, which screens a touch expensive against both the machinery sector and its peers. A different lens tells a slightly friendlier story. The SWS DCF model estimates fair value at ¥8,770.77, which is about 8.9% above the current ¥7,990 share price.
That gap is not huge, but it does suggest the cash flow profile could justify a bit more than the market is paying today. The question for you is simple: do you trust the earnings multiple more, or the cash flow model that says there is still some value left on the table?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takeuchi Mfg for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sense check the mood of this Takeuchi Mfg story for yourself, then move fast enough to form your own view before sentiment shifts. To see both sides of that debate in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Takeuchi Mfg?
Use the same tools that flagged Takeuchi Mfg to widen your opportunity set before the next batch of quality ideas moves out of reach.
- Target companies with strong fundamentals and room for a re-rating by scanning our 14 high quality undervalued stocks.
- Prioritise resilient balance sheets that can handle tougher conditions and still reward shareholders through the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known prospects with robust metrics before the crowd catches on through our 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com