


EN
Does Chlamydia Coinfection Data Change The Bull Case For Innoviva Stock (INVA)?
- Innoviva reported new IDWeek 2026 data showing that FDA approved zoliflodacin maintained high cure rates for uncomplicated urogenital gonorrhea in patients co infected with chlamydia, with chlamydia still requiring separate therapy.
- The finding that chlamydial co infection does not appear to reduce zoliflodacin’s effectiveness supports Innoviva’s effort to build a broader infectious disease franchise within its multi pillar model.
- We will now examine how Innoviva’s investment narrative could shift as zoliflodacin’s robust performance in chlamydia co infections gains attention.
Innoviva Investment Narrative Recap
To own Innoviva, you need to believe the multi pillar model holds together. That means respiratory royalties remain a solid cash engine, Innoviva Specialty Therapeutics keeps scaling, and newer assets like NUZOLVENCE and bacteriophage programs gradually matter more. The IDWeek zoliflodacin data supports this story by reinforcing NUZOLVENCE’s clinical profile, but it does not transform the near term setup on its own.
The key short term catalyst is still a clean and effective NUZOLVENCE US launch in the second half of 2026 into a 1.0 to 1.5 million patient market. The main risk stays the same: any disappointment in the expected US$1b respiratory royalty stream or slower than expected Innoviva Specialty Therapeutics traction would pressure earnings, which already carry forecasts for declining profit over the next three years.
The most relevant recent milestone is the FDA approval of zoliflodacin based NUZOLVENCE in December 2025 for uncomplicated urogenital gonorrhea. The new IDWeek 2026 data that Innoviva presented reinforces that approval by showing maintained cure rates even in patients co infected with chlamydia, which still needs separate treatment.
For you as an investor, that pairing matters. NUZOLVENCE moves from being a theoretical second half 2026 launch to a product with growing real world and late stage evidence in complex patients, which can help execution with infectious disease specialists. The remaining execution risk is commercial: Innoviva still has to convert this profile into sustained US$150 million plus Innoviva Specialty Therapeutics sales and manage any pressure on respiratory royalties.
What The Street Is Building Into Innoviva’s Zoliflodacin Story
Analysts looking at Innoviva are effectively treating NUZOLVENCE and the broader infectious disease effort as part of a bigger puzzle. That puzzle pairs a still meaningful respiratory royalty engine with a hospital focused drug portfolio and a set of healthcare equity stakes that could reshape earnings over time. The new IDWeek 2026 data on zoliflodacin in chlamydia co infections feeds into that picture because it supports the argument that NUZOLVENCE can serve more complex patient profiles without losing effectiveness against uncomplicated urogenital gonorrhea.
The equity story that comes out of the consensus numbers is not one of straight line expansion. Forecasts call for revenue to grow by 7.8% a year for the next three years, yet earnings are projected to move the other way. Profit today of US$357.2 million is expected to shift down to US$214.6 million by 2029 as margins compress from 81.2% to 38.9%. That kind of split view means the market narrative has to balance a growing top line with a thinner profit pool that still depends heavily on respiratory royalties and careful capital deployment into infectious disease assets such as NUZOLVENCE and bacteriophage programs.
NUZOLVENCE’s approval in December 2025 and the supportive IDWeek 2026 readout do not rewrite those forecasts on their own. What they can do is influence how investors judge the quality of the projected US$551.1 million of revenue and US$214.6 million of earnings in 2029. If infectious disease specialists view zoliflodacin as reliable in real world co infection settings, then the hospital anti infective platform looks more resilient. That perception feeds into whether a future P/E of 13.1x on those 2029 earnings feels conservative, aggressive, or simply a fair reflection of a maturing royalty backed infectious disease and critical care business.
Innoviva's narrative projects US$551.1 million revenue and US$214.6 million earnings by 2029. This assumes 7.8% yearly revenue growth and an earnings decline of about US$142.6 million from US$357.2 million today.
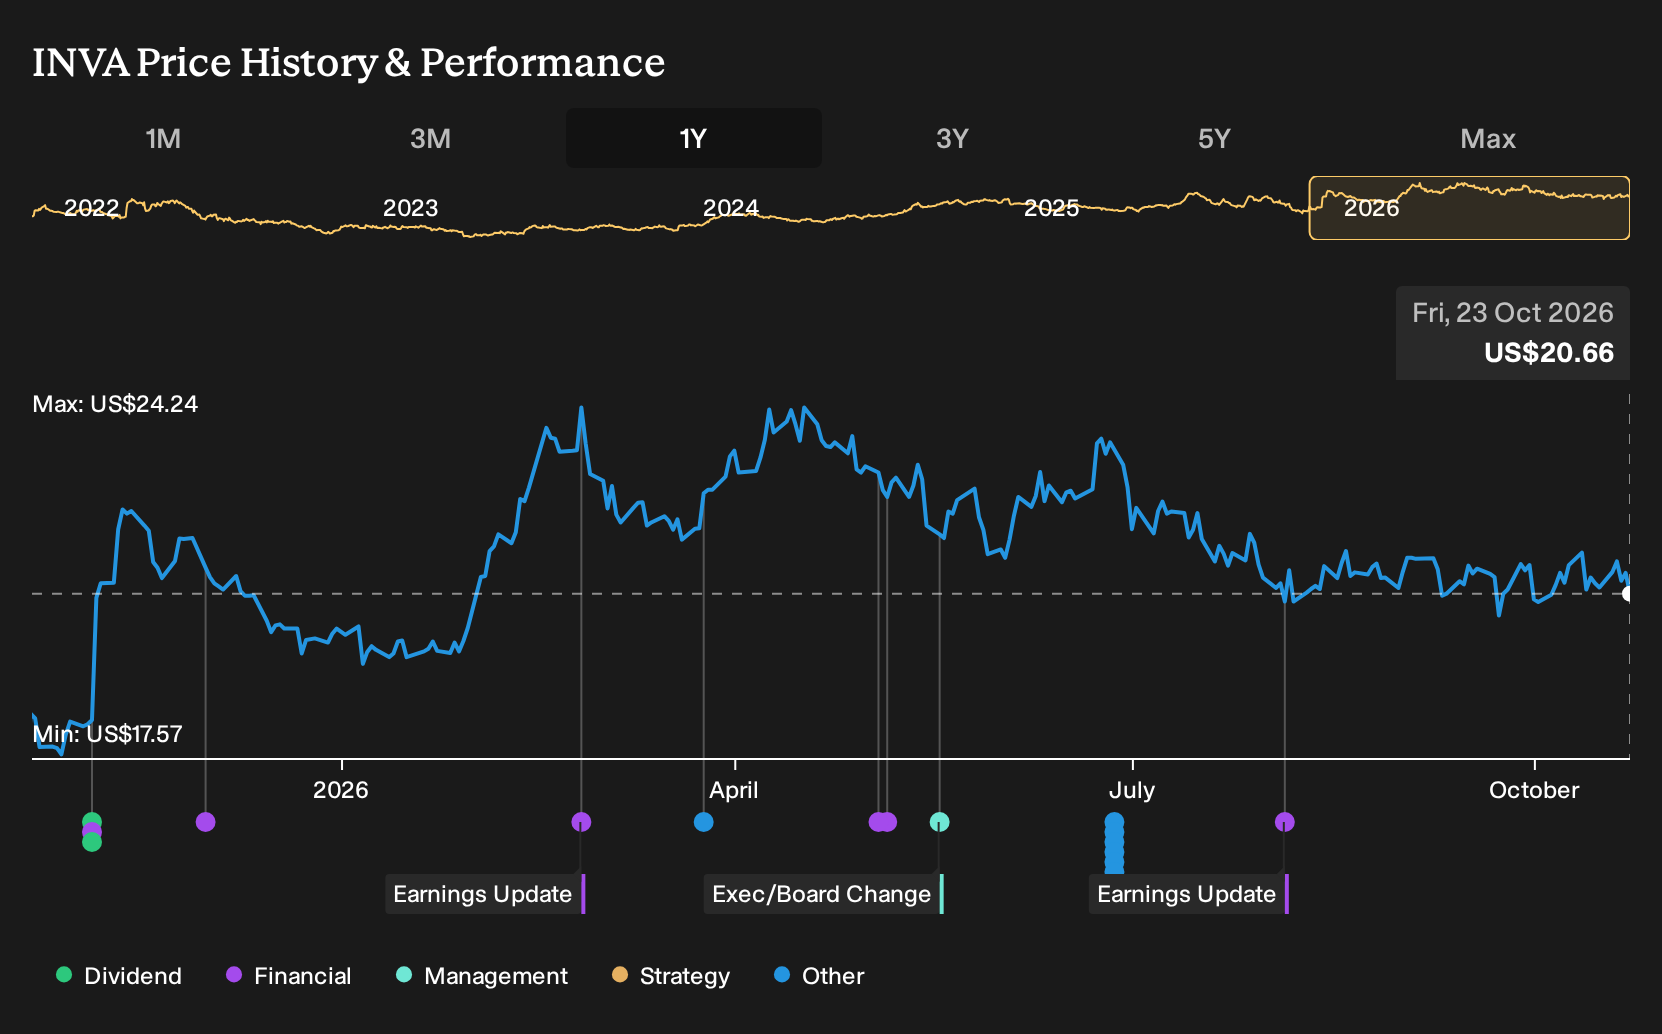
Uncover why Innoviva's fair value indicates a 69% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle you might consider is the bearish focus on margins. The lowest analysts were modelling revenue of about US$425.8 million and earnings of roughly US$127.2 million by 2029, with margins compressing to 29.9%. That is far harsher than consensus and shows how sharply opinions on Innoviva can diverge, even before factoring in the new IDWeek 2026 data.
Explore 2 other Innoviva fair value estimates, including one that suggests it could be worth just $35.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Innoviva research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Innoviva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Innoviva's overall financial health at a glance.
Looking For More Investment Ideas Beyond Innoviva?
If Innoviva has sharpened your focus on how clinical data and cash flows intersect, it can be useful to line it up against a wider set of opportunities using the Simply Wall St Screener.
- For investors who care most about valuation support and fundamentals, review a 27 high quality undervalued stocks that combine stronger balance sheets with pricing that still implies caution.
- If reliability and capital protection matter more to you than headline growth stories, scan a 30 resilient stocks with low risk scores that score well on stability and risk metrics.
- When you want to broaden your watchlist with underfollowed ideas, sift through a 21 high quality undiscovered gems that pair financial quality with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com