


EN
Analyst Upgrade Might Change The Case For Investing In Dick's Sporting Goods (DKS)
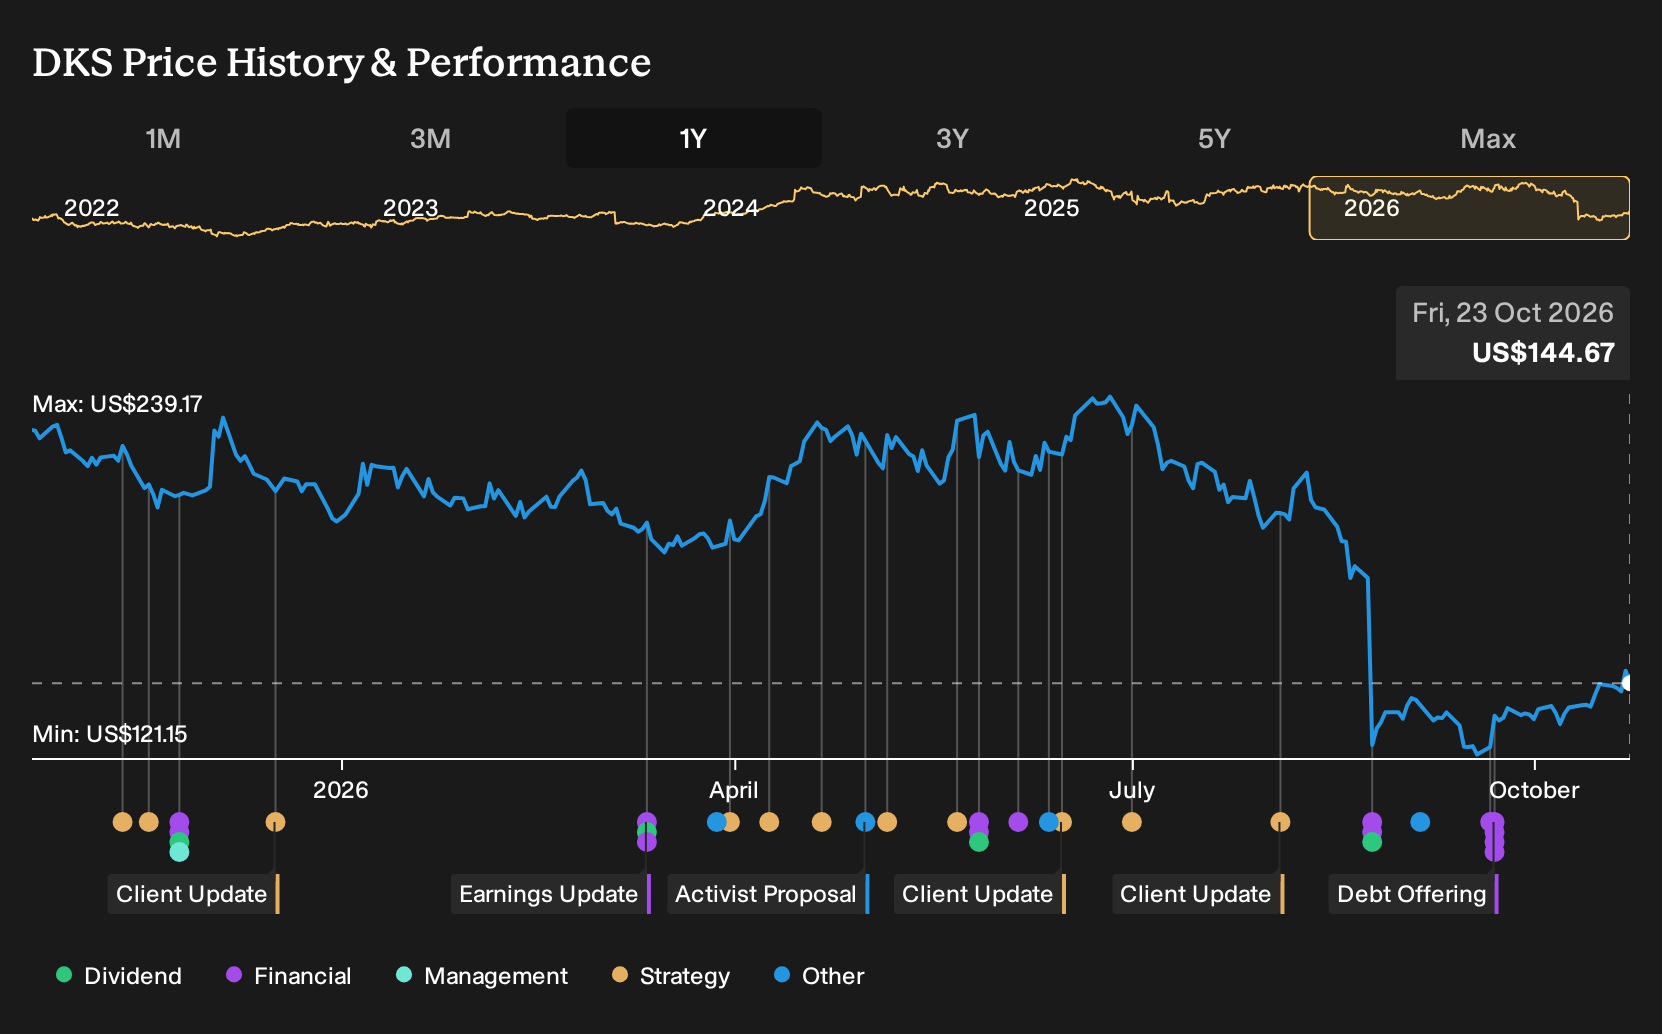
- DICK'S Sporting Goods recently faced investor scrutiny after weaker Foot Locker sales, heavier promotions and a reduced fiscal 2026 adjusted earnings outlook, while a research firm initiated coverage with a positive view on the long term setup.
- The class action lawsuit tied to the Foot Locker acquisition highlights how integration challenges, inventory quality and promotional intensity are now central to DICK'S Sporting Goods' earnings story.
- We will now look at how DICK'S Sporting Goods' investment narrative intersects with renewed optimism about holiday demand and Foot Locker integration.
Scan how other retailers with complex turnarounds are priced right now by exploring our curated list of list of solid balance sheet and fundamentals (25 results)
DICK'S Sporting Goods Investment Narrative Recap
For a shareholder in DICK'S Sporting Goods, the core belief is that the core banner, new formats such as House of Sport and Field House, and higher margin platforms such as GameChanger and DICK'S Media Network can offset the drag from Foot Locker. The weaker outlook tied to footwear and promotions keeps the near term catalyst very clear. Investors are watching for proof that merchandise margins and store traffic can hold up through key shopping periods.
The biggest operational risk remains the Foot Locker turnaround. It is running operating losses, carries heavy restructuring charges and depends on a footwear category dealing with discounting and softer launches. Recent seasonal optimism and the research upgrade do not change that this turnaround, and whether synergies actually show up in margins, is still the main swing factor.
The class action lawsuit linked to the Foot Locker acquisition is the announcement that matters most around this news. It focuses on claims that investors were given too optimistic a view of inventory clean up and promotional pressure. For you, that brings governance and disclosure quality into the operational story, not just legal costs in isolation.
In the near term, that legal overhang sits alongside Foot Locker's projected US$40 million to US$80 million operating loss in 2026, significant integration charges and already tighter free cash flow. Those issues interact directly with the key catalysts investors are tracking, such as cost synergies, Fast Break remodel performance and the ability of DICK'S Sporting Goods to protect the dividend without relying on share buybacks or more aggressive discounting.
DICK'S Sporting Goods' current analyst narrative points to revenues of US$23.9 billion and earnings of US$1.4 billion by 2029. That profile implies 4.2% yearly revenue growth and an earnings increase of about US$561 million from the US$838.8 million reported today.
Uncover why DICK'S Sporting Goods' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You might see the Wolfe Research upgrade and think holiday demand is the main story. The lowest analysts instead zero in on spending risk. They were only penciling in revenue of about US$23.0b and earnings of roughly US$1.0b by 2029, which is far more cautious than consensus. Those views were set before this news, so opinions may shift. Make sure you explore several angles before deciding how DICK'S Sporting Goods fits your portfolio.
Explore 3 other DICK'S Sporting Goods fair value estimates, including one that suggests as much as 43% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DICK'S Sporting Goods research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DICK'S Sporting Goods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DICK'S Sporting Goods' overall financial health at a glance.
Looking for more investment ideas beyond DICK'S Sporting Goods?
If the DICK'S Sporting Goods story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you widen the field and stress test your thesis against other opportunities with different risk and income profiles.
- For investors who care most about resilience and capital preservation, the 30 resilient stocks with low risk scores can help surface businesses where risk scores sit on the lower end of the spectrum.
- If your focus is on quality at a reasonable price, the 27 high quality undervalued stocks can point you toward companies that combine stronger fundamentals with more modest valuations.
- For readers hunting for less crowded stories, the 21 high quality undiscovered gems can highlight under-the-radar stocks that still screen well on financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com