


EN
How Earnings Expectations At Exelixis (EXEL) Has Changed Its Investment Story
- Exelixis recently attracted attention after analysts highlighted expectations for higher quarterly revenue and earnings per share, supported by ongoing demand for its oncology portfolio and upcoming results for the September 2026 quarter.
- The extended FDA review for zanzalintinib in metastatic colorectal cancer has sharpened focus on how Exelixis balances pipeline timing with its existing cabozantinib driven cash engine.
- We will now look at how Exelixis’ investment narrative might be influenced by anticipated earnings strength and the zanzalintinib review extension.
Scan how Exelixis compares to other oncology players by reviewing our curated list of 27 high quality undervalued stocks that analysts currently view as mispriced by the market.
Exelixis Investment Narrative Recap
To own Exelixis, you need to be comfortable with a story built on a cabozantinib cash engine and a pipeline that is still converting into commercial products. The near term hinge point is whether upcoming CABOMETYX and broader portfolio performance can keep earnings on a solid track while R&D stays near the targeted US$1b or less.
The biggest operational risk right now remains concentration in cabozantinib and the timing of new indications, especially as zanzalintinib moves through an extended review. The recent expectation for stronger September quarter earnings does not materially change that equation. However, it does give the company a little more breathing room while waiting for regulatory clarity.
The extended FDA review for zanzalintinib plus atezolizumab in previously treated metastatic colorectal cancer is the update that matters most here. That three month delay pushes out potential U.S. launch timing, and therefore pushes out when Exelixis might start building a second major oncology franchise alongside CABOMETYX.
This review extension makes execution on existing CABOMETYX indications, including neuroendocrine tumors, even more important as the firm approaches its 2030 to 2031 patent window. It also raises the stakes for the seven ongoing pivotal studies for zanzalintinib, since any further regulatory setbacks or restrictive labels would weigh on how fully those clinical assets translate into future earnings and cash generation.
What The Current Exelixis Forecasts Assume
Analysts sketch a version of Exelixis that leans on steady top line expansion and a fatter profit pool over the next few years. The working model points to revenue growing at about 12.6% a year, with profit margins rising from 35.3% today to 41.0% by year three.
On the earnings side, the consensus case lines up on a destination rather than the exact path. Forecast profit of US$1.4b by 2029 compares with earnings today of US$860.6m. That move implies an increase of roughly US$539m in annual profit, backed by analysts’ expectation that share count declines by about 7% a year through buybacks.
Those assumptions matter because they frame what has to go right around cabozantinib durability, zanzalintinib approvals and cost discipline. If margins do not widen from the low 30s to the low 40s, or if revenue growth runs below the low teens figure that is currently baked in, then the earnings bridge from roughly US$861m to about US$1.4b becomes tougher to reach.
For investors watching Exelixis through the next few earnings cycles, the key test will be simple: does reported revenue and profit progression track anything close to that 12.6% revenue growth and margin expansion path, or do revisions start to pull the 2029 destination down?
Exelixis' current analyst framework points to revenue of US$3.5b and earnings of US$1.4b by 2029. That path assumes yearly revenue growth of 12.6% and an earnings increase of about US$539m from current earnings of US$860.6m.
Uncover why Exelixis' fair value indicates a 15% potential downside to its current price that leaves little room for error.
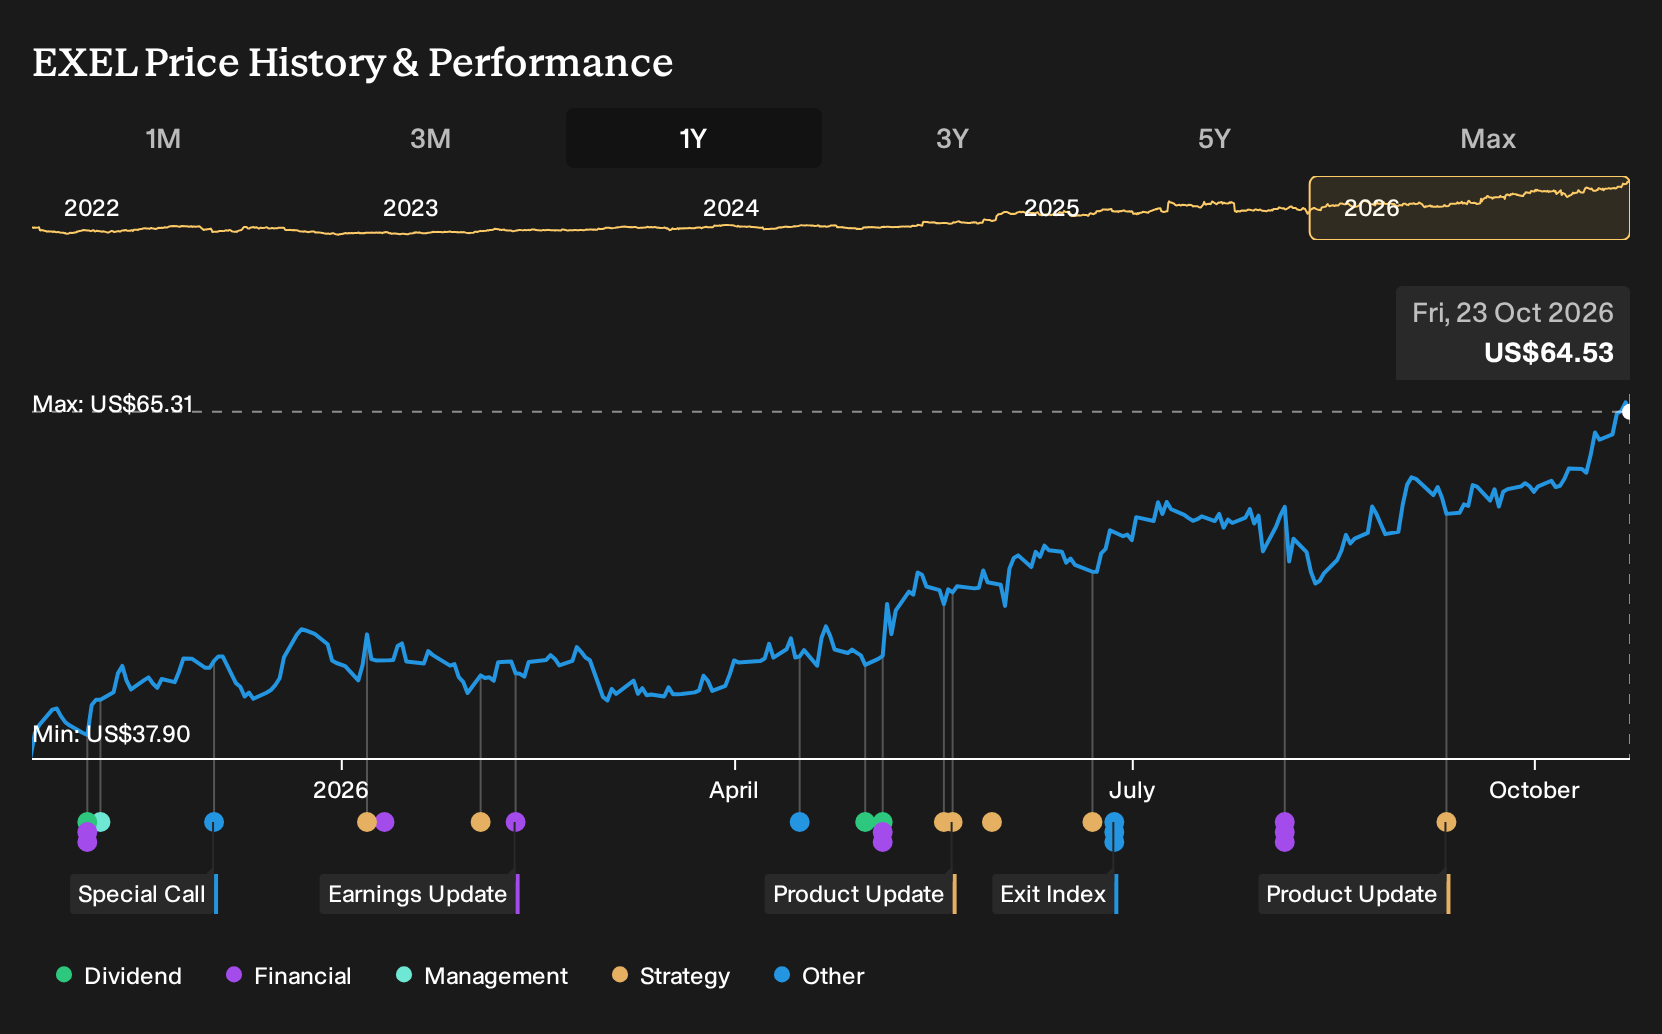
Exploring Other Perspectives
For Exelixis, the sharpest alternate worry is that colorectal and NET launches do not fully materialize. The most cautious analysts were penciling in revenue of about US$3.3b and earnings of roughly US$1.2b by 2029, versus the US$3.5b and US$1.4b consensus. That gap shows how wide opinion can run, so use this news to compare several viewpoints before deciding what you believe.
Explore 4 other Exelixis fair value estimates, including one that suggests as much as 15% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Exelixis research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Exelixis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exelixis' overall financial health at a glance.
Looking for more Exelixis style investment ideas?
Once you have a view on Exelixis, it can help to line it up against other opportunities so you can see where the risk, income and balance sheet profiles feel most comfortable for you.
- For investors who want quality and value together, start with a focused selection of 21 high quality undiscovered gems that combine solid fundamentals with less crowded ownership.
- If capital preservation ranks high on your list, compare Exelixis with a group of 30 resilient stocks with low risk scores that screen well on balance sheet strength and volatility.
- For those who care about financial resilience first, widen your research to a list of solid balance sheet and fundamentals (25 results) and see which companies match your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com