


EN
Earnings Miss Could Be A Game Changer For PulteGroup Stock (PHM)
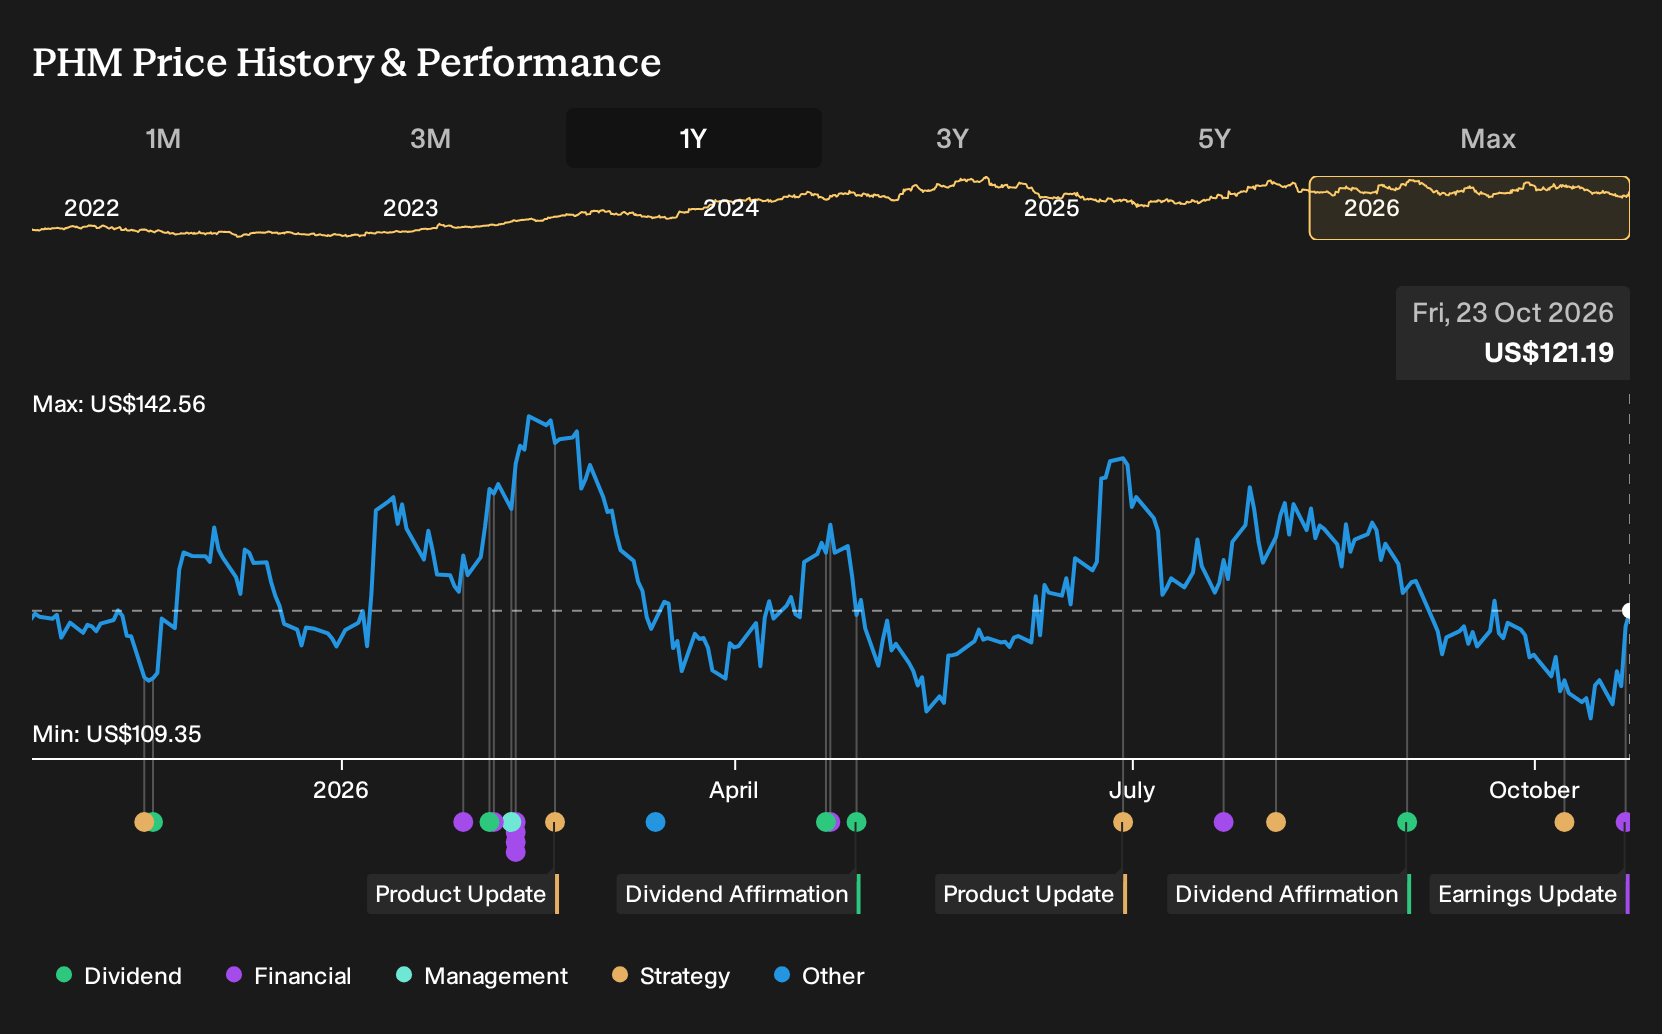
- PulteGroup reported third quarter 2026 revenue of US$3.97b and net income of US$475.73m, with earnings per share from continuing operations below the prior year as higher mortgage rates and inflation weighed on homebuying demand.
- The active adult segment showed resilience while first time buyers faced affordability pressure, and management leaned on pricing discipline, inventory control, and a US$6.44b backlog to support margins despite softer orders and a weaker operating margin.
- We will look at how PulteGroup's investment narrative is affected by softer demand tied to higher mortgage rates and affordability pressures.
What Is PulteGroup's Investment Narrative?
PulteGroup is a cyclical homebuilder, so the main consideration is straightforward: you need to be comfortable owning a business where demand, pricing power, and land spend are tightly linked to mortgage rates and buyer confidence. The latest quarter, with revenue of US$3.97b and earnings per share from continuing operations below last year, underlines that sensitivity. Orders and margins felt the rate shock, yet a US$6.44b backlog and focus on build to order and product mix show management leaning on operational levers rather than blunt price cuts.
In the short term, the key factors to watch are buyer traffic stabilising, incentives remaining contained, and PulteGroup converting that backlog into cash at the margin profile it targets. The quarter’s miss against expectations and share price pullback highlight that softer demand and lower net income are not just noise. Execution on land acquisition, build cycles, and capital returns, including buybacks, now matters even more as revenue growth forecasts sit well below the broader US market.
Even so, there is a less comfortable angle to PulteGroup’s story that sits beneath the backlog and value case...
There's only one way to know the right time to buy, sell or hold PulteGroup. Head to Simply Wall St's company report for the latest analysis of PulteGroup's Fair Value.
Exploring Other Perspectives
One of the starkest alternate views on PulteGroup focuses on earnings quality. The most bearish analysts were modelling only about 2.4% annual revenue growth to roughly US$17.6b and flat earnings of about US$1.9b with EPS near US$11.5 before this miss. That is a much more pessimistic earnings path than consensus, and this latest quarter could push those opinions even further apart. If you want a fuller picture, compare these lower assumptions with other analyst scenarios to decide which story feels more realistic to you.
Explore 4 other PulteGroup fair value estimates, including one that suggests as much as 13% downside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PulteGroup research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PulteGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PulteGroup's overall financial health at a glance.
Looking For More Ideas Beyond PulteGroup?
If you want to round out your watchlist beyond PulteGroup, a quick scan of different types of opportunities can help you balance quality, risk, and income potential.
- For investors who want to lean into value with quality filters, use the 27 high quality undervalued stocks that screens for strong fundamentals and pricing that may not fully reflect them.
- If balance sheet strength is your anchor, run a pass through the list of solid balance sheet and fundamentals (25 results) to focus on businesses with financial structures that can better handle tougher conditions.
- Those aiming to prioritise income can scan the 5 dividend fortresses and narrow in on higher yield opportunities that still meet your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com