


EN
Vistra (VST) Stock Looks Below Fair Value After Nuclear Funding
Vistra has delivered a very large 5 year share price gain while the stock has retreated over the past year, so the live question now is whether that journey leaves today's valuation fully supported by its earnings power. With fresh government backed funding for nuclear upgrades and long term power deals with big technology customers, investors are weighing how those moves feed into the profit stream that underpins the current share price.
- Over the past 5 years the stock has returned roughly 7x, which puts a lot of focus on whether recent earnings can sustain that kind of value creation going forward.
- The conditional US$4.2b loan for nuclear plant upgrades and long term contracts with companies like Meta and Amazon can improve earnings visibility, but they also reshape the timing and scale of future cash flows that matter for any earnings based valuation.
- The analysts covering Vistra have run their own numbers. See what analysts think Vistra's shares could be worth.
The issue now is whether Vistra's current share price is adequately explained by what the business is earning today and what those earnings reasonably suggest about its future profit stream.
To cross-check Vistra's earnings story against other options in the same broad theme, use a focused stock screen of 42 power grid technology and infrastructure stocks.
Does Vistra Look Undervalued on Earnings?
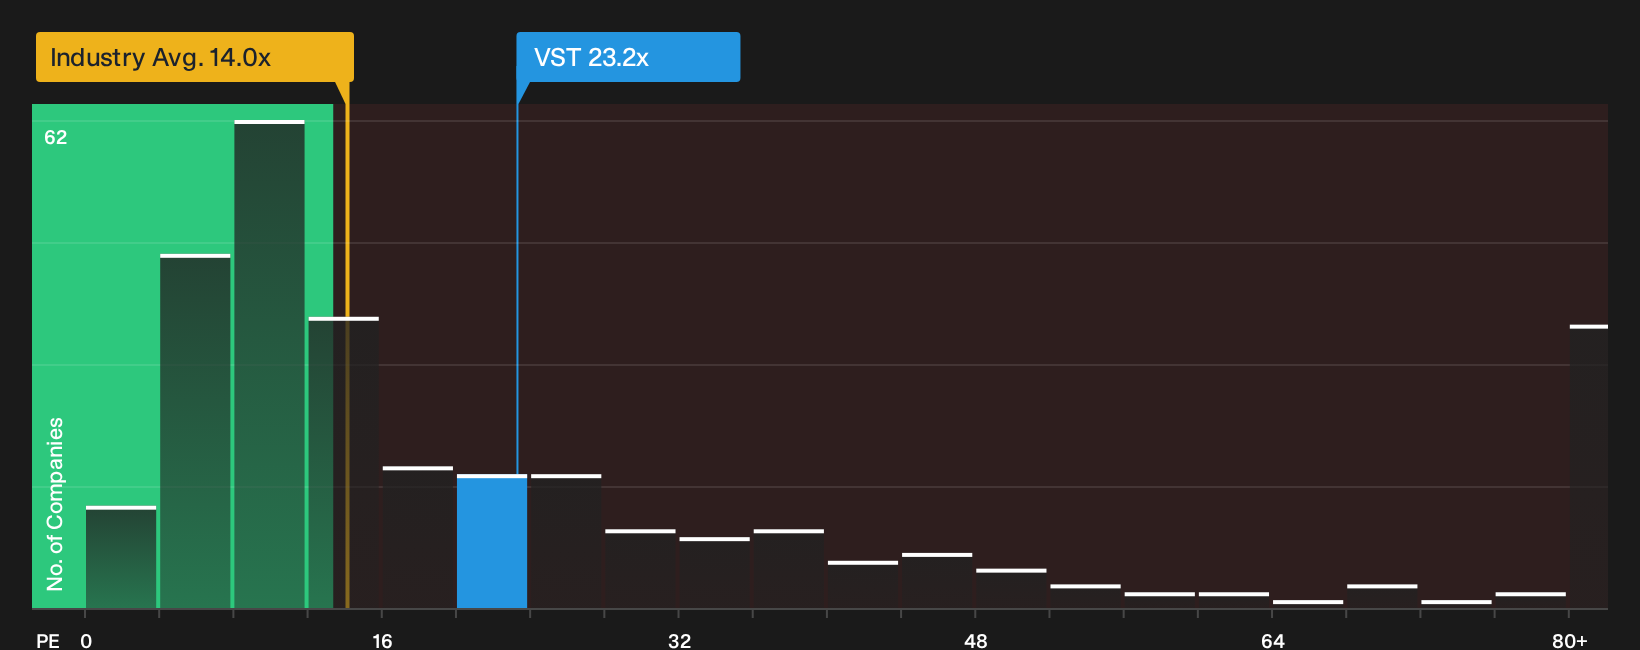
The P/E multiple suits Vistra because earnings sit at the center of how investors frame regulated and contracted power businesses. On this yardstick, Vistra trades on a P/E of about 23.2x, which is higher than both the renewable energy industry average of roughly 14.0x and the peer group near 18.4x. That indicates the market is willing to pay a richer price for each dollar of Vistra's reported profit than for many similar utilities and power producers.
The tailored fair P/E that blends Vistra's growth profile, margins, scale and risk points to a higher level than where the stock currently trades, so the present 23.2x sits below what that model implies. Because the US$4.2b nuclear upgrade loan and long term deals with large technology customers support a more visible earnings stream, the stock appears on this framework as undervalued relative to that customised benchmark rather than stretched. Explore the numbers behind Vistra's P/E valuation.
The Vistra Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Vistra pick up where the valuation questions leave off and spell out the specific growth, margin and earnings paths that would need to hold for the stock to look meaningfully cheaper or more expensive than today’s price. Rather than stopping at a single ratio or model output, they lay out the future that those numbers assume so you can revisit that story over time and see whether Vistra's progress still lines up.
Vistra draws two very different readings, with one camp seeing a sizeable discount and another arguing the shares already reflect plenty of good news.
Bull case: 34% undervalued
"Progress on large-scale, multi-decade contracts with hyperscalers and data centers is moving forward as Vistra signs long-dated PPAs with counterparties such as Meta, Amazon and TCDC..."
Discover why this Narrative puts Vistra at 34% undervalued.
Bear case: 8% overvalued
"Debt is real. $18.73 billion of net debt, confirmed, is not something two credit upgrades erase."
Explore why this Narrative puts Vistra at 8% overvalued.
Vistra's valuation raises one more big question
Price ratios and recent contracts frame what Vistra is today, but there is a separate lens that compares this share price with where professionals expect the business to be a few years from now. Explore where analysts expect Vistra to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com