


EN
How Investors Are Reacting To Extreme Networks (EXTR) On Prem AI Roadmap
- Extreme Networks previewed its Extreme Exchange zones roadmap, a planned on-prem enterprise AI offering that pools existing access point and switch capacity with local servers to control data residency, latency, and AI workload placement.
- The on-prem focus targets customers with strict sovereignty, resilience, and cost constraints, aligning Extreme Networks’ AI stack with real-world compliance needs and branch-heavy deployments such as retail, warehouses, and public sector sites.
- We will look at how Extreme Networks’ investment narrative is reshaped by this on-prem AI roadmap and pooled edge compute capability.
Scan how Extreme Networks’ on-prem AI push compares with other infrastructure plays by reviewing 55 AI infrastructure stocks positioned to benefit from similar data residency and edge compute themes.
Extreme Networks Investment Narrative Recap
For a shareholder in Extreme Networks, the core belief is that AI driven networking and edge compute can turn its existing hardware footprint and software stack into deeper, stickier customer relationships. The preview of Extreme Exchange zones points toward that direction, but it is early and availability is targeted for the first half of calendar 2027, so near term impact looks limited.
The more immediate swing factor remains execution on cloud managed subscriptions, AI features in Extreme Platform ONE, and Wi Fi 6E and Wi Fi 7 refresh activity. The biggest current risk still sits in revenue concentration in government and public sector deals, where contract timing and budgets can quickly affect quarterly performance.
The Extreme Exchange zones roadmap is the announcement that matters most here. It links directly to the existing Extreme AI layer and Agent ONE interface, and to the firm’s focus on edge compute and data residency. If customers adopt on premises AI where data cannot leave the site, that can support usage of Extreme’s broader enterprise stack.
Execution is the real test. Management needs to turn this concept into robust software, clear pricing, and reliable performance across thousands of distributed sites. Competitive pressure from larger vendors, together with Extreme Networks’ higher P/E relative to peers, keeps the bar high for this type of product roadmap to act as a durable catalyst.
Extreme Networks' narrative projects US$1.7b revenue and US$60.2 million earnings by 2029. This assumes 9.8% yearly revenue growth and an earnings increase of about US$18.1 million from US$42.1 million today.
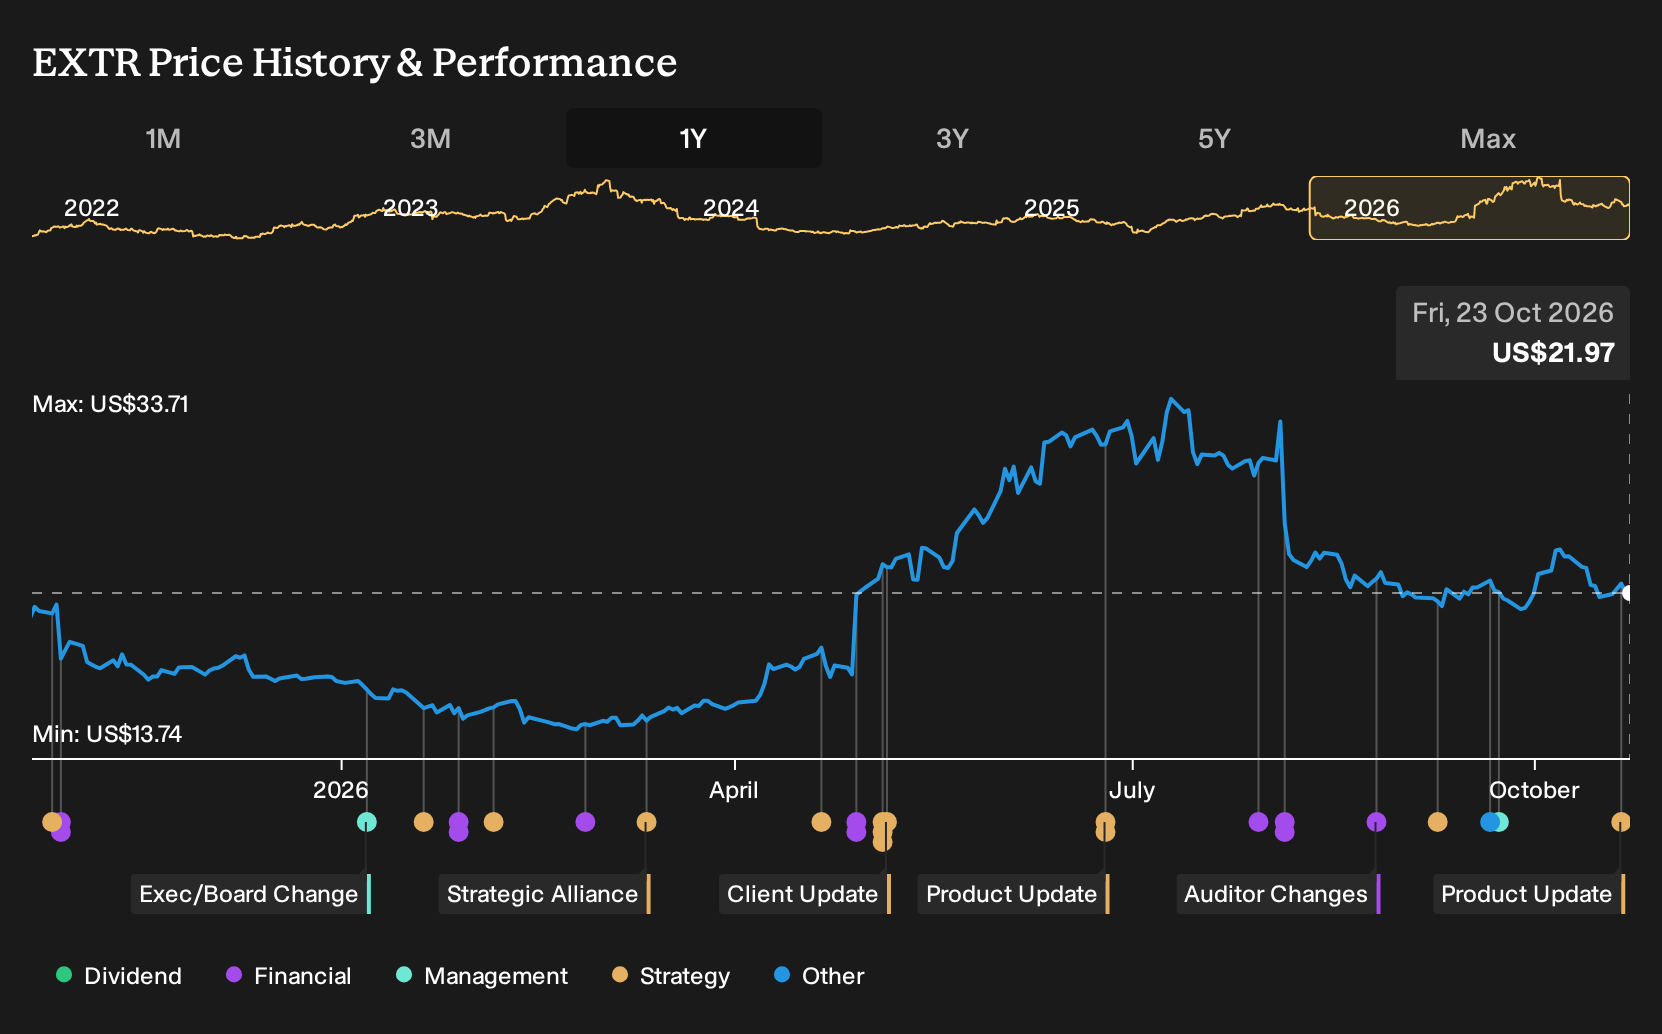
Discover how Extreme Networks' fair value indicates a 52% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts on Extreme Networks focus heavily on the on premises AI angle. They were already modeling about US$1.7b in revenue and US$45.2 million in earnings by 2029, with a P/E of 140.4x. You can treat this product roadmap as a fresh input that might shift those expectations further, in either direction.
Explore 4 other Extreme Networks fair value estimates, including one that suggests as much as 137% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Extreme Networks research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Extreme Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extreme Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Extreme Networks?
If the Extreme Networks story has sharpened your view on AI, edge compute, and data residency, it can help to benchmark that thinking against a wider pool of companies. The Simply Wall St Screener gives you a way to filter for traits that match your own risk, return, and balance sheet preferences.
Here are a few focused angles you could use as a next step.
- If resilience and capital strength matter most to you, focus on companies with strong cash positions and manageable debt using our list of solid balance sheet and fundamentals (25 results).
- If you prefer to aim for mispriced quality, review a curated set of fundamentally sound businesses trading below their estimated worth through the 27 high quality undervalued stocks.
- If you are hunting for lesser known opportunities with solid fundamentals, widen your watchlist with the 21 high quality undiscovered gems before they attract broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com