


EN
Is Sustainability Report Progress Altering The Investment Case For DTE Energy (DTE)?
- DTE Energy has released its 2025 Sustainability Report, outlining progress on retiring coal by 2032, scaling wind and solar parks, and investing in grid reliability and customer assistance programs across Michigan.
- The report frames decarbonization as an infrastructure buildout, linking coal retirement, renewables, and grid upgrades to long term capital deployment and customer affordability pressures.
- This article will now examine how DTE Energy's planned coal exit by 2032 and renewable buildout may reshape its broader investment narrative.
Scan 42 power grid technology and infrastructure stocks to find other utilities that could benefit as grid upgrades and cleaner generation (like DTE Energy) reshape long term capital spending and reliability themes.
DTE Energy Investment Narrative Recap
To own DTE Energy, you need to be comfortable with a regulated utility that is trying to shift its generation mix while pouring money into reliability and customer programs. The short term story still revolves around winning timely approvals for large capital projects and recovering those costs in rates without overwhelming customer bills.
The 2025 Sustainability Report does not materially change that near term catalyst or the biggest risk. The pressure point remains the same. Storm related outages, potential penalties and any move to tighten links between reliability, affordability and allowed returns could squeeze earnings if spending rises faster than what regulators are willing to approve.
The most relevant disclosure tied to this report is DTE Energy’s plan to end coal by 2032 and rely more on gas, wind, solar and storage. That is a long build program. It aligns with existing plans for gas plants and renewables to support growing large load customers such as data centers.
For you, the operational question is whether the utility can execute that transition while funding US$11b of planned electric distribution spending and annual equity issuance of roughly US$500m to US$600m. If regulators remain comfortable with cost recovery and reliability metrics improve, that investment pipeline can remain a key earnings driver rather than a balance sheet risk.
DTE Energy's current analyst narrative points to forecast revenue of US$17.8b and earnings of US$2.1b by 2029. That outlook assumes revenue growth of 2.6% a year, along with an earnings increase of roughly US$0.8b from current earnings of about US$1.3b.
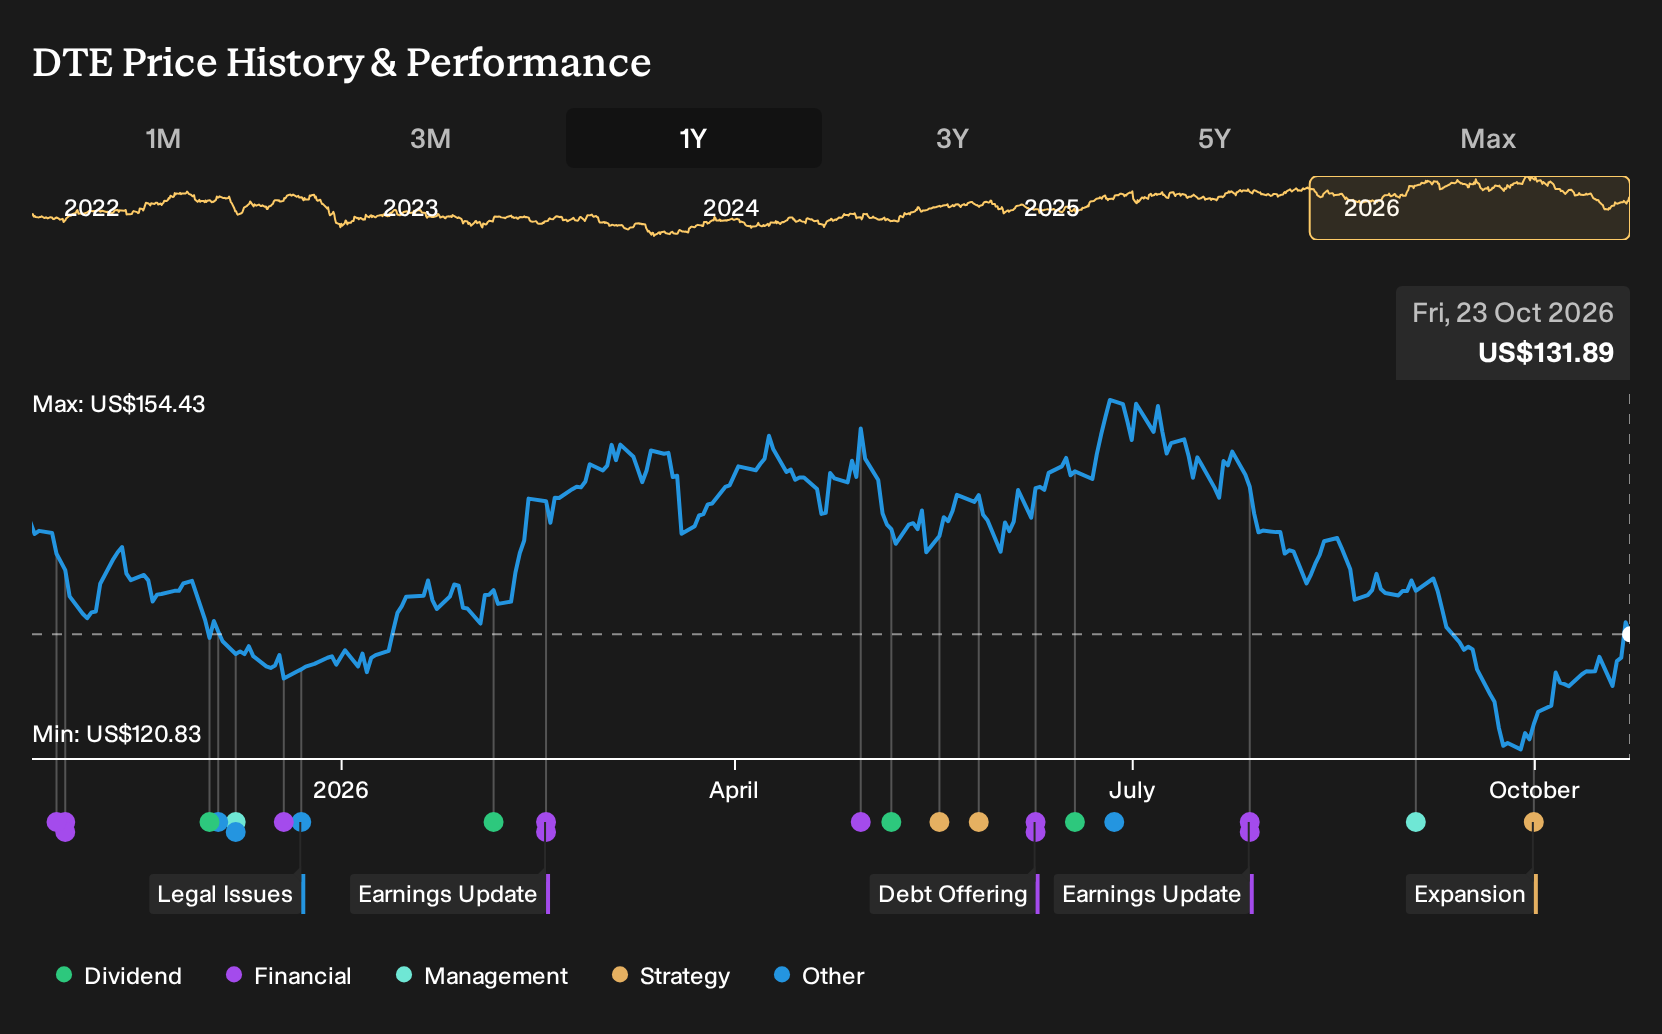
Uncover why DTE Energy's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$106 and US$149, with one view at the top end flagging much richer upside for DTE Energy than the rest. Set that against storm, regulatory and equity issuance risks, and you can see why opinions differ. Use these contrasting viewpoints to stress test your own stance.
Explore 3 other DTE Energy fair value estimates, including one that suggests as much as 13% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DTE Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DTE Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DTE Energy's overall financial health at a glance.
Looking for more investment ideas beyond DTE Energy?
If DTE Energy has sharpened your thinking on regulated utilities and long term infrastructure spending, it can be useful to line that up against other potential opportunities. The Simply Wall St Screener lets you quickly scan for companies that match different risk, income and valuation profiles so you can see where DTE Energy fits in your broader watchlist.
- For investors who care most about resilient balance sheets and solid fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you compare financial strength side by side.
- If you want income to play a bigger role in your portfolio, consider a 5 dividend fortresses that focuses on companies offering higher yields with a stability angle.
- Those looking for mispriced opportunities can review a 27 high quality undervalued stocks that highlights businesses where fundamentals and current prices appear out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com