


EN
Why Chime Stock And Payment Peers Matter As Banks Rein In AI Payments
AI is rushing into finance, but big banks are suddenly drawing hard lines around who controls customer payments. That shift creates real friction for third party agents and fresh attention on the established electronic payment rails that keep money moving quietly in the background. This piece walks through three large U.S. payments stocks that sit closest to this AI tug of war and explains how the same headlines could help or hurt each one.
The three stocks covered below are a small sample of what AI sensitive payment giants look like. The full electronic payments screen surfaced 9 more large, U.S.-listed networks and processors with equally compelling narratives that are not unpacked here. To sort through the broader universe yourself, head straight into the Electronic Payments Networks and Processors screener to identify, analyze, and focus on the electronic payments plays that best fit your thesis.
Chime Financial (CHYM)
Overview: Chime Financial is a digital banking platform that provides checking, debit, credit building, savings, and payment tools through app based accounts.
Operations: Chime Financial generates about US$2.5b in revenue from data processing services, with all reported revenue coming from the United States.
Market Cap: US$11.4b
Chime Financial fits this payments focused screen as a digital bank that routes everyday spending, transfers, and credit activity across established card and electronic networks. This may matter even more as banks tighten access for third party AI agents and bring more data rich tools in house.
"The rapid shift toward digital banking is maturing, and with Chime already at 9.1 million active members in a finite mainstream market, incremental member growth may decelerate as the easiest-to-acquire users are captured, limiting long term revenue expansion and ARPAM growth."
What happens if one unseen pressure on how much value Chime can squeeze from each existing member quietly shifts the margin math?
That pressure point is exactly where the thesis for Chime Financial starts to get interesting, and the full narrative for Chime Financial unpacks how AI driven engagement could reprice that potential.
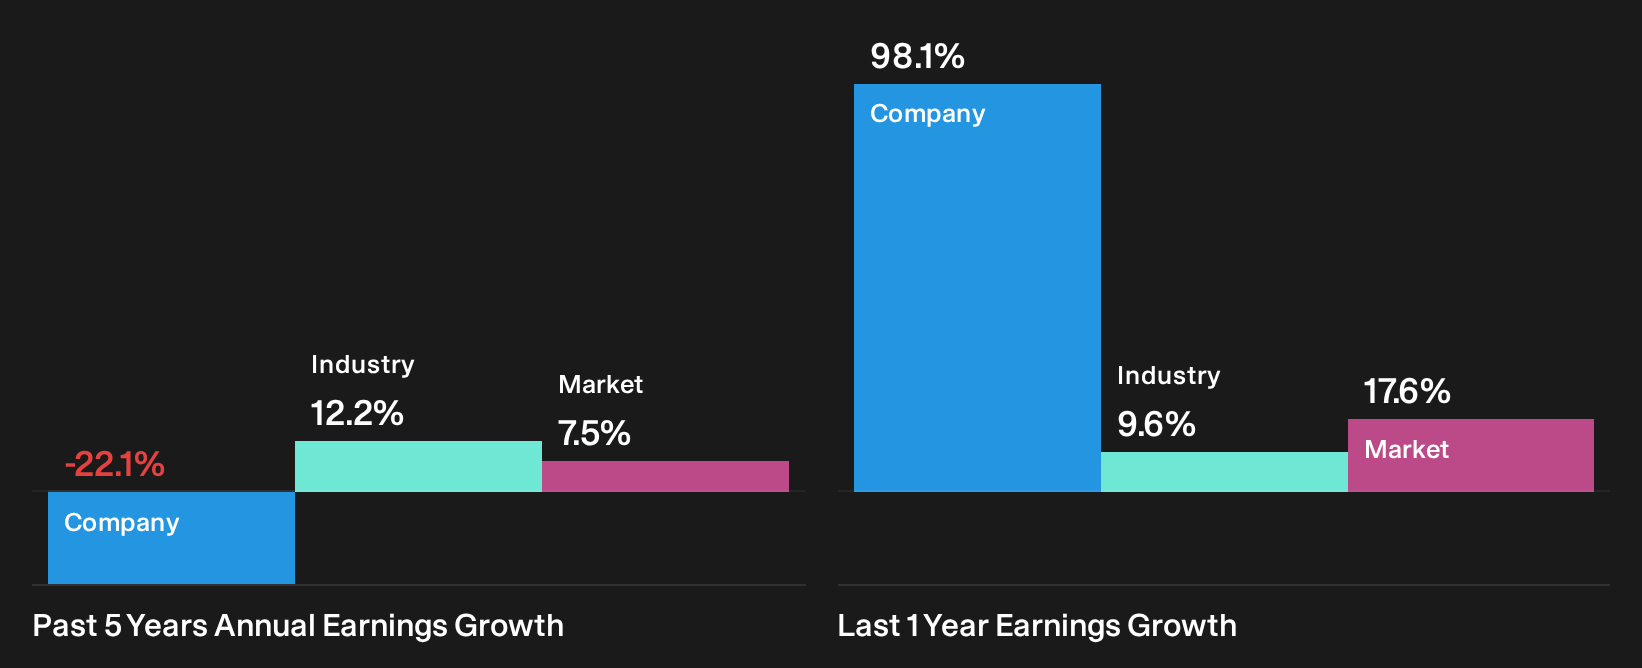
DLocal (DLO)
Overview: DLocal runs a global payments platform that lets international merchants accept and send digital payments using local methods in emerging markets.
Operations: DLocal generates about US$1.36b from payment processing, with revenue concentrated across Brazil, Mexico, Argentina and other Latin American countries.
Market Cap: US$4.3b
DLocal matters in this payments focused screen because it handles the behind the scenes routing for merchants trying to reach shoppers in harder to access emerging markets.
"dLocal is continuing to expand its solution set through higher take-rate value-added services such as buy now pay later in eight markets, merchant of record, FX OTC products and physical POS."
The real swing factor is how one quiet shift in how merchants use those services ultimately feeds through to DLocal's margins.
That margin swing is exactly what the full narrative for DLocal unpacks, revealing how payment mix, take rates, and AI driven acceptance tools could accelerate DLocal's earnings leverage.

Payoneer Global (PAYO)
Overview: Payoneer Global runs a New York based fintech platform that gives small and mid sized businesses multi currency accounts for cross border payments.
Operations: Payoneer Global generates about US$1.08b from data processing services tied to its cross border payments platform across multiple global regions.
Market Cap: US$2.43b
Payoneer Global matters for this payments focused screen because it plugs directly into cross border B2B flows, sitting between merchants, banks, and marketplaces as those partners reassess which digital rails they trust most in a tighter AI and compliance climate.
"Expansion of higher-margin B2B payments and value-added services into larger SMB and SME customers, backed by 44% year-over-year B2B volume growth in Q1 2026 and about one-third of SMB volume now coming from B2B, supports further take rate uplift and revenue ex-interest growth as Payoneer Global continues to shift its mix toward higher ARPU clients."
What happens if a single assumption in that higher margin mix shift moves the wrong way and squeezes the room for future profitability gains?
If that profit squeeze is what you are focused on, the full narrative for Payoneer Global explains how those B2B shifts could either accelerate or stall Payoneer Global's earnings engine.

Seeking Alternatives Before Everyone Else?
Fresh stock ideas can move from quiet to crowded fast. Spot potential breakout stories while they are still under the radar for now, then act now.
- Target income streams by focusing on companies in the 5 dividend fortresses before yield chasers direct more attention to these payouts.
- Track developments in automation by scanning the curated 95 robotics and automation stocks while these operators are still building momentum outside of major headlines.
- Look for solid balance sheets using the focused list of solid balance sheet and fundamentals (25 results) and identify quality names before stronger results narrow potential entry points.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com