


EN
Is NiSource (NI) Fully Priced On Its Microsoft Power Deal?
NiSource (NI) is back in focus after signing a long term energy agreement with Microsoft for the tech giant’s planned northwest Indiana data center campus, a material commitment for both power capacity and customer savings.
Recent trading has been choppy. NiSource’s share price has advanced 10.27% over the past month but slipped 7.28% over the last 90 days, while the 1-year total shareholder return of 1.85% contrasts with a very large 5-year total shareholder return above 100%. This suggests that long term holders have already seen substantial gains and that recent momentum is now rebuilding around news like the Microsoft agreement.
Scan regulated utilities connected to major data center demand and see which ones appear in the hand picked 42 power grid technology and infrastructure stocks list.
After a sharp month long rebound on top of very strong 3 and 5 year returns, the real debate is whether NiSource still offers meaningful upside or if most of the rerating has already occurred as investors reassess the Microsoft deal and its earnings profile.
Most Popular Narrative: 11% Undervalued
NiSource last closed at $43.28, while the most followed narrative pegs fair value at about $48.73. This leaves a double digit percentage gap that hinges on how much the Microsoft and broader data center build out feed into the long term capital plan.
Strong visibility into multi year, rate based capital expenditure has been updated to a plan through 2033 that supports 9 to 11% consolidated rate base growth and higher long term adjusted EPS CAGR guidance of 9 to 10%, which can compound regulated revenue and earnings as projects enter the rate base.
See why 11 investors see NiSource as 11% undervalued.
Result: Fair Value of $48.73 (UNDERVALUED)
Still, the story around NiSource can shift quickly if regulators push back on its US$28.6b long term capital plan, or if higher storm and labor costs keep pressuring margins.
Find out about the key risks to this NiSource narrative.
Another View: What The Market Is Paying For NiSource
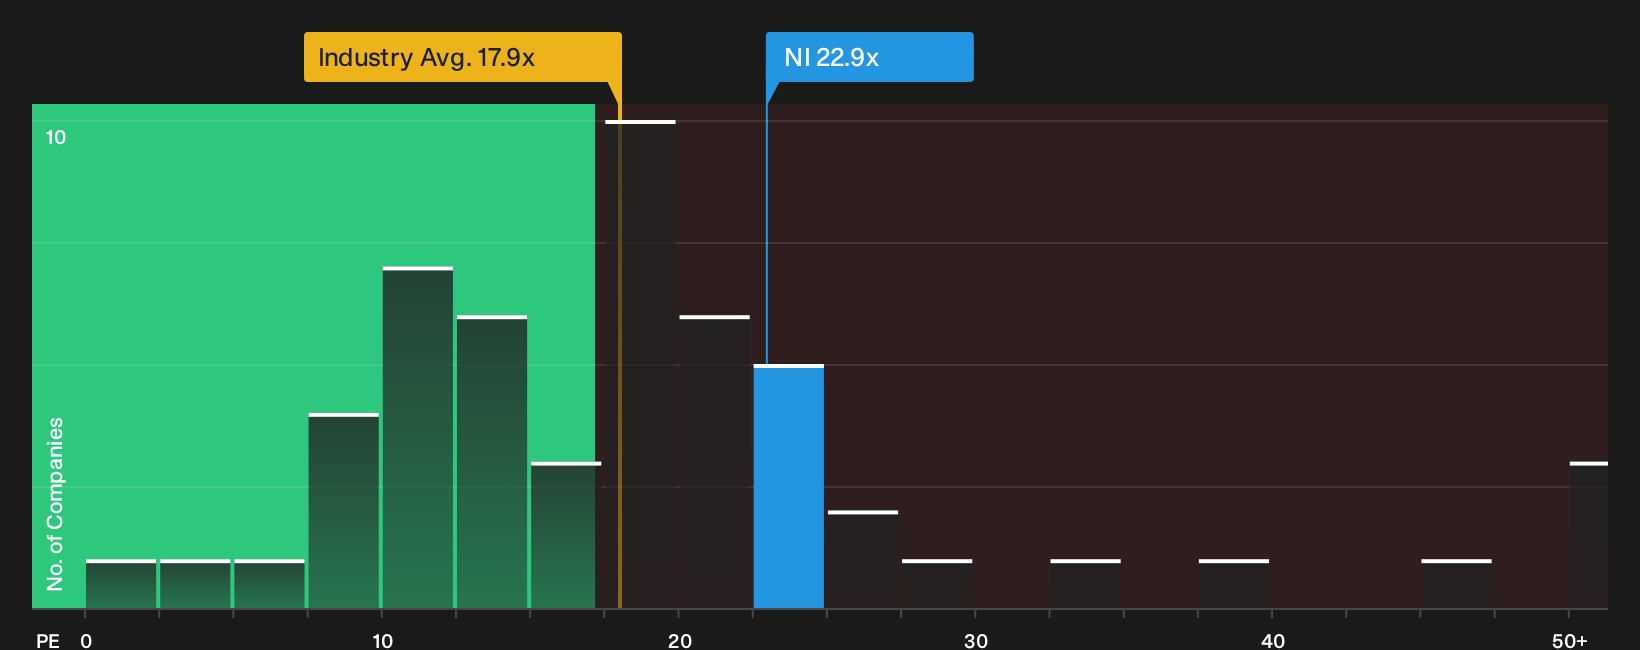
The analyst narrative leans on fair value of $48.73, yet the current P/E of 22.9x tells a different story. NiSource trades richer than the global Integrated Utilities average at 18x and above its own fair ratio of 20.8x, which signals valuation risk if sentiment cools.
Numbers like that raise a simple question for investors: Is the premium price a reasonable charge for the Microsoft data center optionality, or is it more than you are comfortable paying for a regulated utility profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident about where NiSource sits after the Microsoft deal headlines and valuation debate, or still on the fence as risks and rewards jostle for attention? If you want to weigh both sides quickly and form your own view, start with the 2 key rewards and 3 important warning signs.
Looking for more NiSource style investment ideas?
If NiSource has sharpened your focus on quality and risk, do not stop here. The next winning idea might already be waiting in another corner of the market.
- Target resilient upside by scanning a 27 high quality undervalued stocks list that filters for quality businesses trading at compressed valuations.
- Prioritize staying power and sleep better at night by focusing on a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- Get in early on potential future leaders using a 21 high quality undiscovered gems that surfaces strong fundamentals before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com