


EN
CSX (CSX) Could Be 4% Undervalued As Earnings Beat Lifts 2026 Outlook
CSX (CSX) raised its full-year 2026 revenue guidance to high single-digit growth after reporting third-quarter results that topped expectations, supported by higher volumes, stronger pricing, and wider operating margins.
The earnings beat and guidance upgrade came after a strong run in CSX’s share price, with a year-to-date share price return of 40.03% and a one-year total shareholder return of 42.38%. The recent 30-day share price gain of 7.63% points to momentum building again, following a 90-day share price return that declined 4.58%.
Scan other rail and infrastructure plays that show similar earnings momentum and margin strength with our hand-picked 27 high quality undervalued stocks, which share financial traits with CSX.
Bulls point to CSX’s upgraded outlook and margin strength, while bears flag the 40% year to date rally and rich past returns. Which side does the current valuation actually support?
Most Popular Narrative: 4.4% Undervalued
CSX closed at $50.79, while the most followed narrative pegs fair value closer to $53.10, which puts the recent rally in a different light.
The industrial development pipeline of roughly 600 active projects, with about 100 expected to enter service in 2026 and provide significantly more volume at full ramp than the prior year cohort, is poised to add new carloads that support merchandise and bulk revenue and help operating leverage.
See why 25 investors see CSX as 4% undervalued.
Result: Fair Value of $53.10 (UNDERVALUED)
Still, if CSX stumbles on crew availability or faces tougher safety and access rules, the current thesis could quickly shift from efficiency to constraint.
Find out about the key risks to this CSX narrative.
Another View: CSX Looks Full On Cash Flows
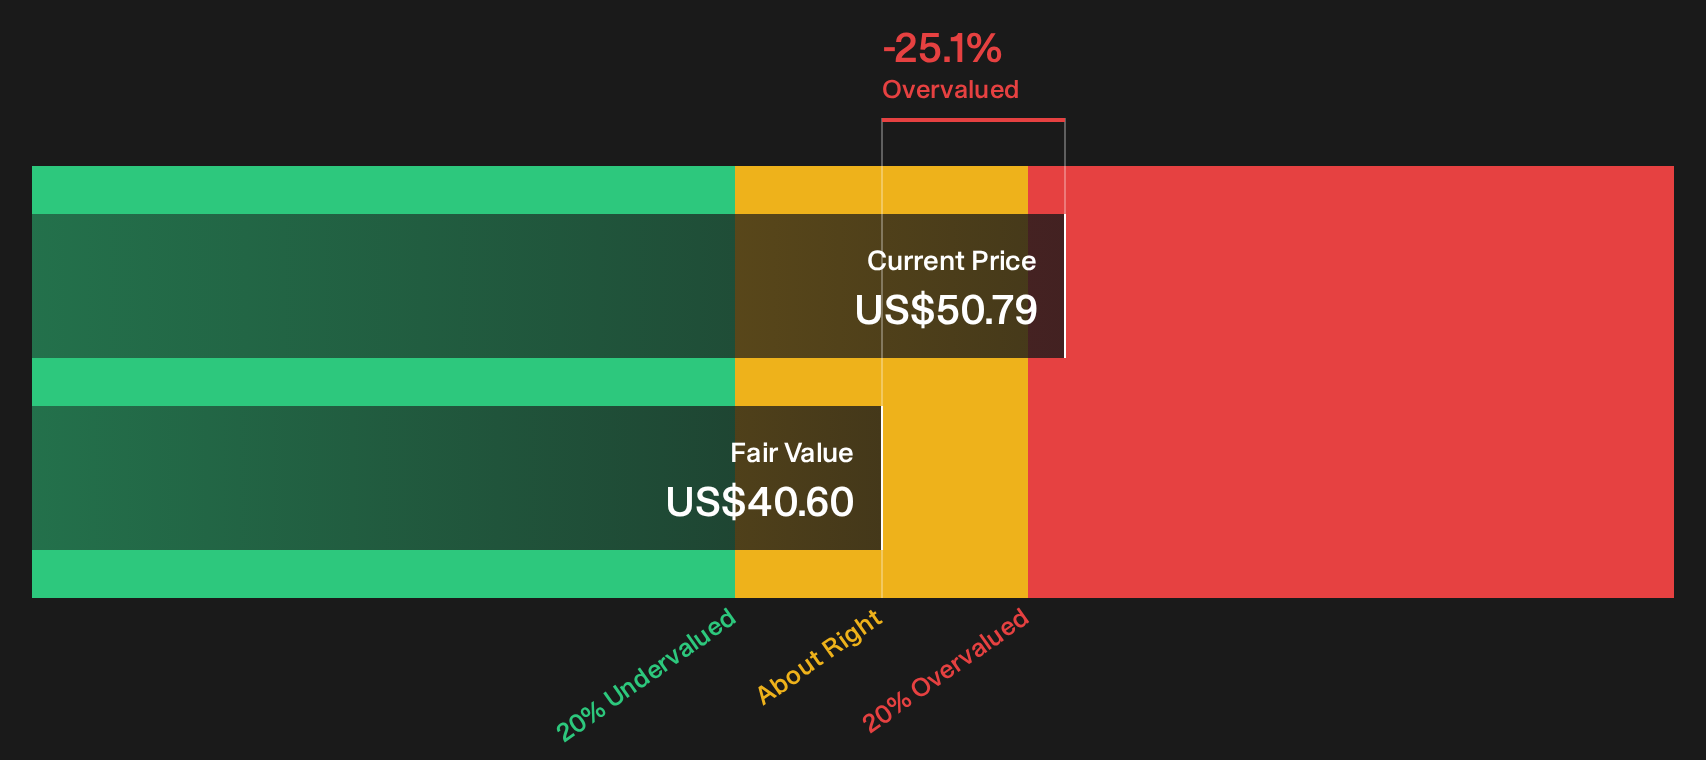
The earlier 4.4% undervaluation narrative leans on earnings power and analyst targets. A different lens, the Simply Wall St DCF model, values CSX at $40.60 per share, which makes the recent $50.79 price look expensive rather than cheap.
If cash flows point to overvaluation while earnings based metrics hint at upside, which picture do you treat as the anchor for risk?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on CSX’s value and risk profile are exactly why you should look at the underlying data yourself and move fast to form your own stance. To see both the upside case and the pressure points in one place, start with these 3 key rewards and 2 important warning signs.
Looking for more CSX investment ideas?
If you stop with CSX, you miss the wider opportunity set. Use the Simply Wall St Screener to surface fresh candidates that fit your risk and return goals.
- Target higher quality potential upside by reviewing companies flagged in the 27 high quality undervalued stocks that share stronger fundamentals and attractive pricing.
- Prioritise resilience by scanning the 30 resilient stocks with low risk scores to find businesses with sturdier risk profiles than the typical index constituent.
- Hunt for overlooked potential by checking the 21 high quality undiscovered gems that combine solid financials with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com