


EN
Carvana (CVNA), What Is Behind The Fresh Attention?
Community partnerships and brand reach around Carvana stock
Carvana (CVNA) recently renewed its multi year partnership with Phoenix Rising FC, keeping its branding on the club’s kit and deepening ties across professional and youth soccer programs in Arizona.
For shareholders, this is a marketing and community engagement development rather than a direct financial catalyst. However, it shapes how the retailer connects with local customers and builds long term brand recognition.
Carvana’s share price has cooled recently, with the stock down 9.6% over the past month and 27.8% year to date even as headlines highlight partnership renewals and service expansions. Yet the three year total shareholder return of more than 9x still signals how sharply sentiment shifted around the business during its recovery phase.
Compare Carvana’s community driven approach with other retailers by scanning the list of solid balance sheet and fundamentals (25 results) that may offer a different blend of resilience and market potential.
Carvana has delivered sharp share price gains over three years, even as the stock has slipped recently. Are investors now reacting to changing fundamentals, or just re-pricing the story as sentiment cools, and what does that mean for valuation next?
Most Popular Narrative: 30.3% Undervalued
Carvana’s most followed narrative anchors on a fair value of $82.98, which sits well above the recent $57.81 close and frames today’s pullback as a valuation gap rather than a clean verdict on the business.
The continued move toward buying cars online, with auto e-commerce still in the low single digits compared with roughly 20% for retail overall, gives Carvana room to keep taking digital share, which can support unit growth and revenue expansion.
The positive feedback loop between higher regional inventory, faster delivery and more efficient marketing, evidenced by regions where inventory growth and sales growth track closely, points to further operating leverage that can support gross margins and earnings.
See why 56 investors see Carvana as 30% undervalued.
Result: Fair Value of $82.98 (UNDERVALUED)
Still, the Carvana narrative depends on inventory and reconditioning capacity catching up with sales, and on unit economics stabilising despite lower profit per vehicle.
Find out about the key risks to this Carvana narrative.
Another View On Carvana’s Valuation
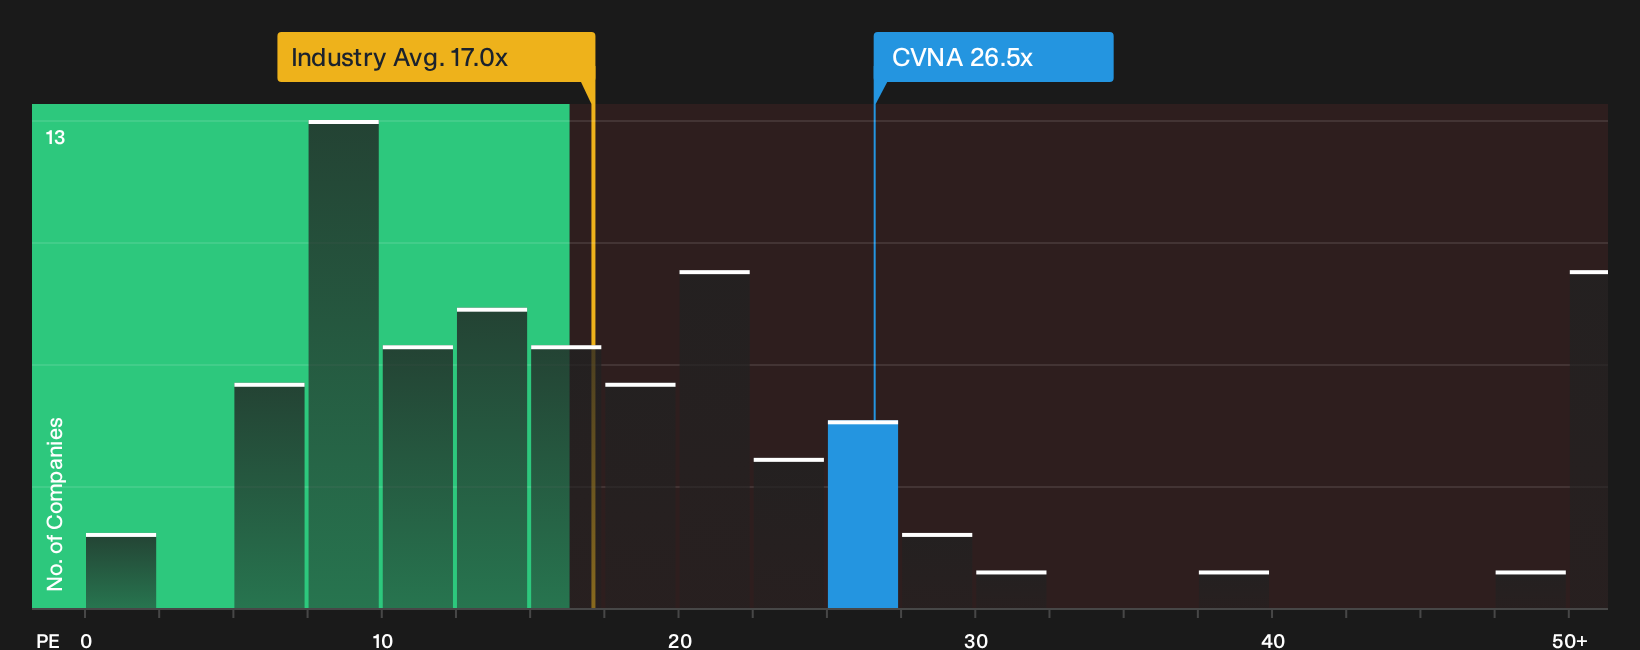
That 30.3% “undervalued” narrative leans on fair value estimates linked to future earnings. A second lens tells a different story. Carvana trades on a P/E of 26.5x, compared with 17x for the US Specialty Retail group, 19.7x for peers and a fair ratio of 26x. This points to a stock already pricing in a lot of optimism. If the market drifts closer to those lower benchmarks, where does that leave the upside case?
To see how those P/E gaps might matter for your own approach, take a closer look at the valuation breakdown and what the numbers imply for risk versus potential reward: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Carvana’s story today. If you want to move quickly and base your view on more than headlines, consider both sides with 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Carvana?
If you only focus on Carvana, you could miss other setups that better fit your risk tolerance, income needs, or appetite for underappreciated opportunities.
- Target steadier potential by reviewing a basket of companies screened for resilience and balance sheet strength through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by checking the 27 high quality undervalued stocks that match strong fundamentals with prices that may not fully reflect them.
- Build a paycheck style portfolio by scanning the 5 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com