


EN
Did Executive Changes Just Shift Ball (BALL) Investment Narrative?
- Ball Corporation has reshaped its beverage packaging leadership, appointing Carey Causey to lead North and Central America and Scott Vail to head the EMEA unit following Mandy Glew’s planned retirement.
- The shift places Ball’s long running operational and cost programs directly under leaders with extensive experience in global packaging, supply chains and commercial execution.
- The next area of attention will be how Ball’s investment narrative may change as Carey Causey takes over the key North American beverage business.
Ball Investment Narrative Recap
To hold Ball stock, investors need to believe the aluminum packaging franchise can turn tight industry capacity, 2027 contract cover and the Ball Business System cost program into steadier margins and cash generation. The key near term catalyst remains execution on North American capacity ramps and Millersburg start up costs in 2026, where management has been working through operational inefficiencies.
These leadership moves appear more like continuity than disruption, with Carey Causey and Scott Vail already embedded in Ball’s commercial and operations engine. That suggests the direct impact on the main near term catalyst is modest. The bigger risk still sits with input cost swings, including aluminum and tariffs, and any setback with a large South American customer.
The leadership reshuffle connects directly to Ball’s company wide productivity push under the Ball Business System, which targets US$500m of gross savings by the end of 2026 and ongoing 1% to 2% annual supply chain cost reductions. Causey has already been responsible for growth and commercial strategy, while Vail has been running global manufacturing and operational excellence.
That background matters for investors who focus on catalysts such as improving free cash flow from a business that is roughly 90% sold out for 2027 and more than 50% contracted through the end of the decade. Execution risk remains, particularly with debt only partly covered by operating cash flow, but there are now clear owners for customer relationships, plant performance and margins in the two most important beverage regions.
What The New Ball Leaders Are Being Asked To Deliver
Ball's narrative projects US$16.1b revenue and US$1.3b earnings by 2029. This lines up with analyst assumptions of 3.9% yearly revenue growth and an earnings increase of about US$355m from US$945.0m today.
Discover how Ball's fair value indicates a 12% potential upside to its current price that may not last much longer.
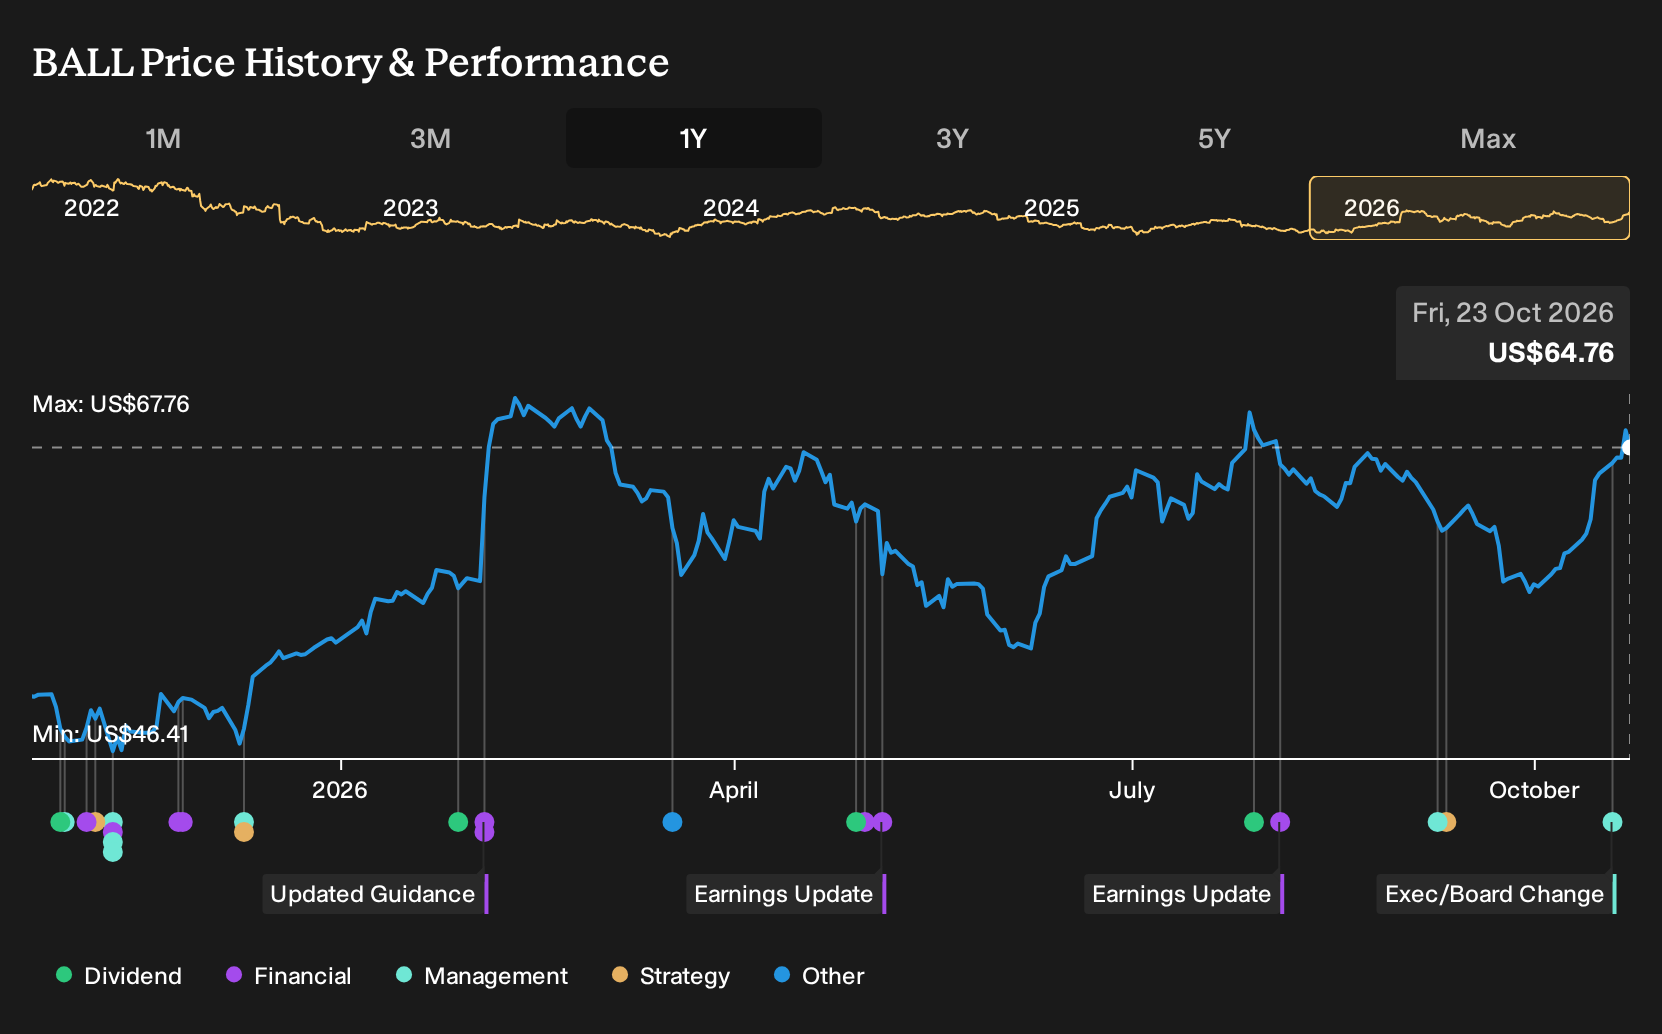
Exploring Other Perspectives
One point that bullish analysts focus on is free cash flow. Before this Ball leadership change, the most optimistic forecasts were built on guidance for more than US$900m of free cash flow in 2026 and about US$17.0b of revenue by 2029. You can read those as a much more upbeat story that may still shift as the new executives settle in.
Explore 4 other Ball fair value estimates, including one that suggests as much as 109% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ball research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ball. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ball's overall financial health at a glance.
Looking For More Ideas Beyond Ball?
If you want to widen your watchlist beyond Ball and see how other companies line up on quality, value and resilience, the Simply Wall St Screener can help you quickly filter the market down to a focused shortlist that actually fits your approach.
- If income is your priority, focus on stability and payouts by zeroing in on 5 dividend fortresses that may suit a yield focused portfolio.
- If capital preservation matters most, tighten your risk profile by scanning a 30 resilient stocks with low risk scores that could help anchor your holdings when conditions get rough.
- If balance sheet strength is non negotiable, start with financially robust businesses using a list of solid balance sheet and fundamentals (25 results) that meet your quality thresholds before you even look at price.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com