


EN
SharkNinja (SN) Faces A Valuation Test Following Strong Earnings Expectations
SharkNinja (SN) heads into its November 4 earnings release with projections calling for 26% EPS growth and more than 14% higher revenue versus last year, drawing attention to the company’s near term outlook.
The share price tells you investors have already been repositioning around SharkNinja’s story, with the stock gaining 16.6% over the past month and 32.2% over 90 days, while the 1-year total shareholder return of 103.2% and 3-year total shareholder return near 4x indicate strong momentum both recently and over a longer holding period.
Spot similar earnings driven momentum by scanning our curated list of 21 high quality undiscovered gems, which, like SharkNinja, are drawing attention ahead of key results.After a near 4x three year run and a triple digit 1 year return, SharkNinja already reflects a lot of enthusiasm. The live question now is whether the current valuation still leaves meaningful upside on the table.
Most Popular Narrative: 77% Overvalued
Against SharkNinja’s last close at $196.38, the most followed valuation story on Simply Wall St pins fair value at $110.73, which frames the current price as rich and sets up a more cautious take on the recent surge.
SharkNinja makes products people genuinely seem to love. My brother-in-law hasn't stopped talking about his Ninja coffee machine. Every gym-goer seems to own a Ninja ice cream maker churning out protein ice cream. And don't get me started on how everyone now owns an air fryer. This is a brand that has quietly embedded itself into daily life and that kind of word-of-mouth loyalty is genuinely hard to manufacture.
Twelve straight quarters of double-digit growth tells you this isn't a fluke. They keep launching products people actually want, they are pushing into new markets globally, and the more people buy direct from Shark and Ninja's own sites rather than through retailers such as Myer and Good Guys, the more margin they get to keep. That flywheel is only going to get stronger as the brand grows.
See why 8 investors see SharkNinja as 77% overvalued.
According to AshleighG, who authored this widely followed thesis, that product and brand strength still did not justify paying more than $110.73 per share at the time of writing, even after factoring in assumptions for moderating growth, slightly higher margins and a premium P/E multiple. Set against today’s $196.38 price, this narrative implies the market is baking in a far more optimistic path than those inputs support, so anyone assessing SharkNinja’s rally needs to decide which story feels more realistic.
Result: Fair Value of $110.73 (OVERVALUED)
Still, SharkNinja’s story could shift quickly if consumer budgets tighten further or if tariffs and other cost pressures bite harder into profitability than current assumptions allow.
Find out about the key risks to this SharkNinja narrative.
Another View: SWS DCF Model Puts SharkNinja Below Fair Value
That first narrative pegs SharkNinja as expensive at $196.38, yet the SWS DCF model points the other way, with an estimated future cash flow value of $238.60 and a 17.7% gap that screens as undervalued. Which story you trust more depends on how confident you are in those long term cash flow assumptions.
For a closer look at how this cash flow based approach is built, and where the main pressure points sit in the forecast path, Look into how the SWS DCF model arrives at its fair value.
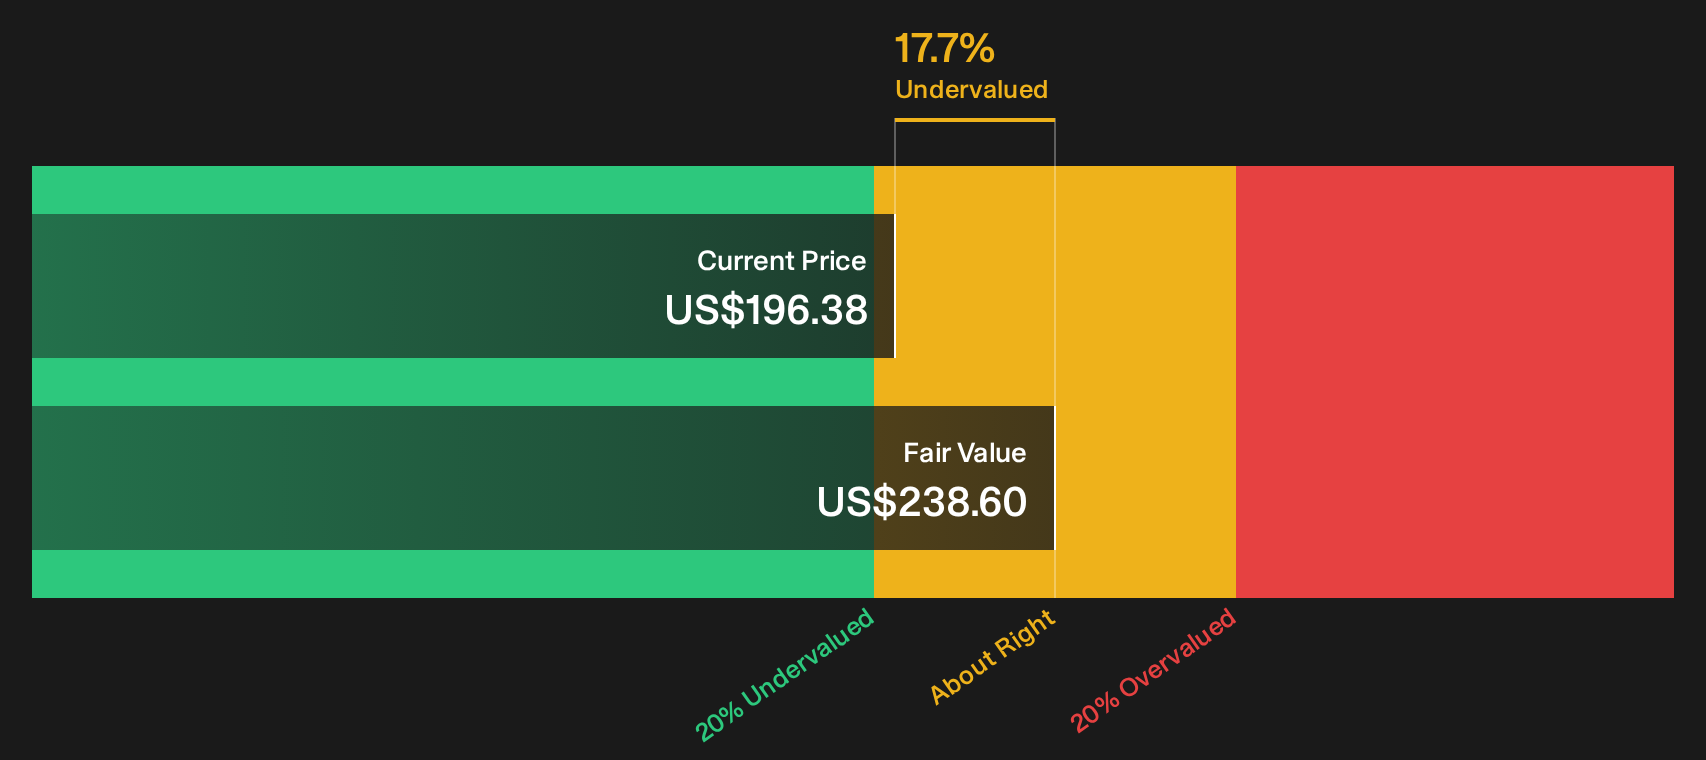
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong views are forming around SharkNinja on both value and risk. Act while the data and narratives are fresh and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SharkNinja?
If you only focus on SharkNinja, you may miss other opportunities that match your risk profile, income needs, or return goals across the wider market.
- Target higher potential payoff by scanning a curated group of 7 elite penny stocks with strong financials that already pass strict financial quality checks.
- Strengthen your core holdings by reviewing a focused 27 high quality undervalued stocks that pairs solid cash generation with disciplined balance sheets.
- Dial down portfolio stress by filtering for a 30 resilient stocks with low risk scores and see which companies score strongest on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com