


EN
Is Earnings Beat Altering The Investment Case For Tractor Supply Stock (TSCO)?
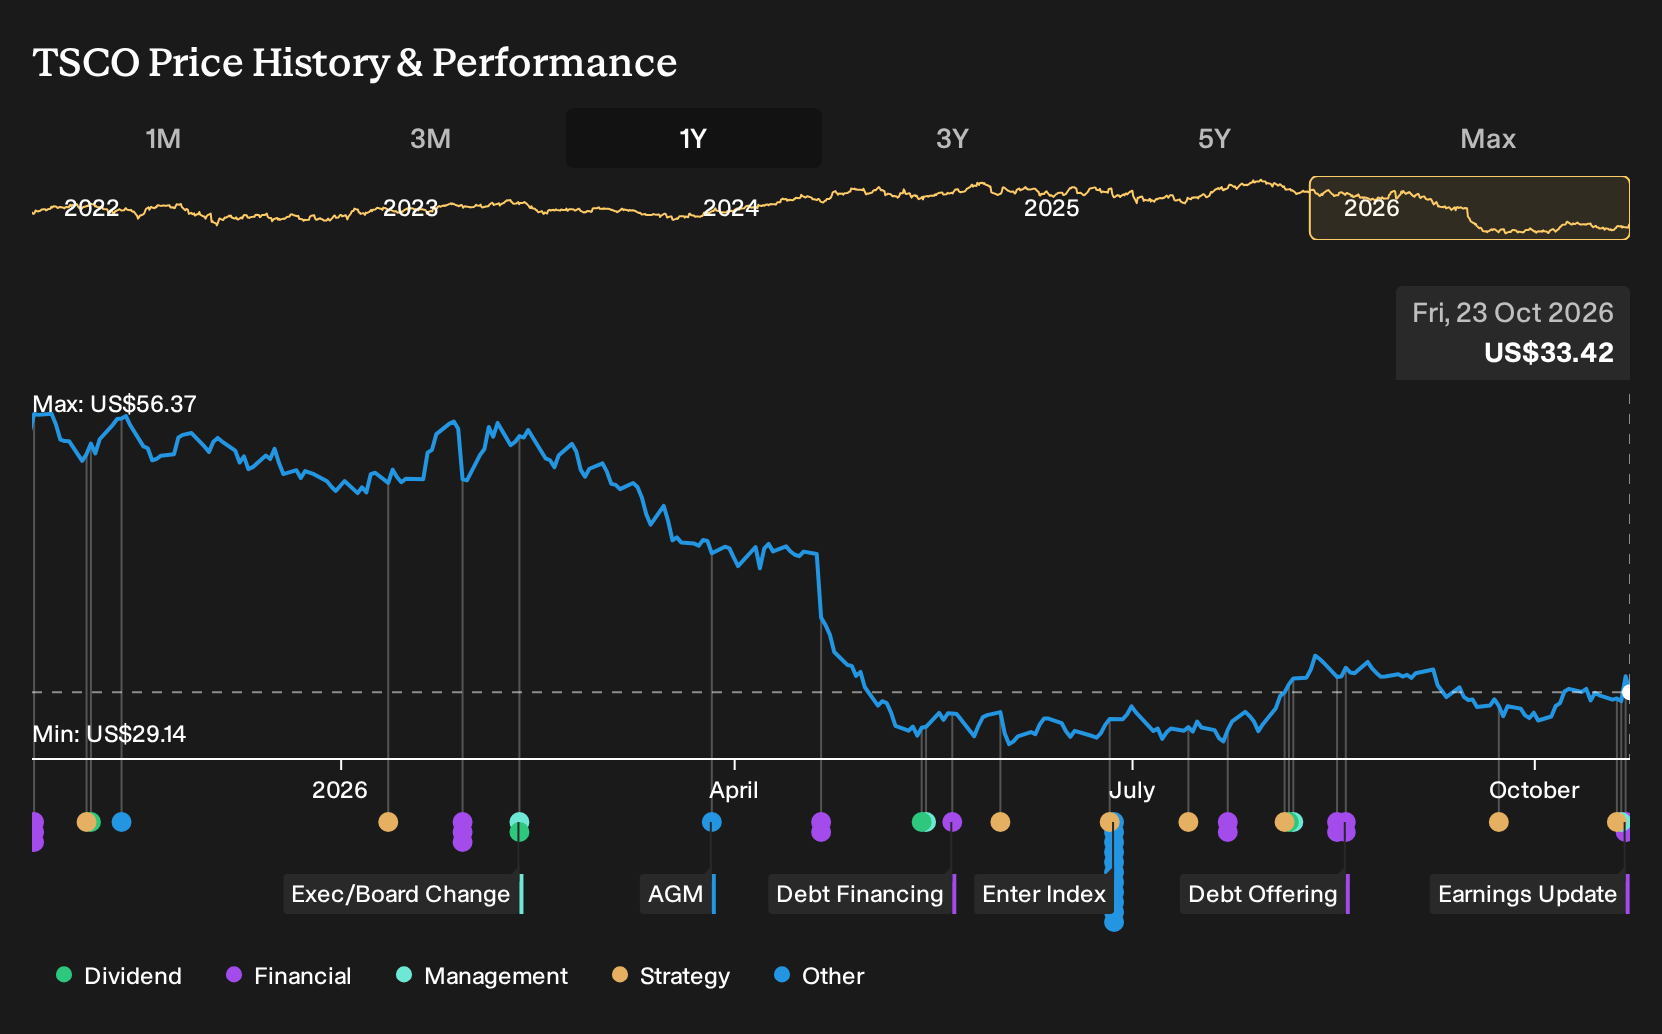
- Tractor Supply reported third quarter 2026 sales of US$3.91b and earnings per diluted share of US$0.43, reaffirming full year guidance that includes expected net sales growth of about 2.5% to 3.5% and net income between US$930m and US$990m.
- The retailer paired its guidance confirmation with new cost control plans, including SG&A reduction targets and moderated store expansion, while continuing to invest in digital capabilities and pet related offerings.
- This article examines how Tractor Supply's reaffirmed guidance and margin repair efforts shape the investment narrative investors rely on.
Compare Tractor Supply's margin repair story with other retailers that pair cost discipline and measured growth in our hand picked 30 resilient stocks with low risk scores list.
Tractor Supply Investment Narrative Recap
To own Tractor Supply, you need to believe this retailer can restore profitability while keeping rural and pet customers coming back regularly. The reaffirmed 2026 outlook, with net sales growth of about 2.5% to 3.5% and net income of US$930m to US$990m, supports a steady but not aggressive recovery path. The key short term catalyst is margin repair as management leans on vendor support, pricing and SG&A controls.
The biggest near term risk is that softer discretionary and big ticket demand returns or macro pressure drags on comparable sales again, which could blunt that margin rebuild. Q3 results showed revenue at US$3.91b and EPS at US$0.43, alongside lower year to date earnings, so execution on cost savings and capital discipline remains central.
The appointment of Fahim Siddiqui as Executive Vice President, Chief Technology and Digital Officer looks tightly connected to Tractor Supply's current catalysts. Management is leaning on digital revenue growth, Final Mile delivery and e commerce convenience. Siddiqui's remit spans technology infrastructure, cybersecurity, digital commerce and data platforms that support those areas.
This hire also matters for risk. As Tractor Supply moderates store openings and tightens capital spending, more of the growth and margin story runs through digital productivity, better inventory and smarter customer engagement. Strong execution from the new technology leader could influence how effectively the retailer converts its online traffic, pet ecosystem and delivery capabilities into steadier comps and more resilient operating margins.
What Analyst Forecasts Imply for Tractor Supply
Analyst expectations provide a rough map of where Tractor Supply might be heading if its current playbook on margins, pet, and digital continues to hold. The consensus view incorporates steady revenue expansion, modestly better profitability and a tighter share count, which together shape how much earnings power the retailer could produce a few years from now.
On the top line, analysts are penciling in 4.6% yearly revenue growth over the next three years. That rate sits above the reaffirmed near-term outlook for 2026 and indicates that the earnings story investors watch is tied to a mix of new income streams, a healthier mix of consumables and improved productivity from Final Mile delivery and distribution center automation.
Profitability assumptions are more incremental than dramatic. Forecasts call for profit margins to move from 6.1% today to 6.6% in three years. That half point lift reflects the cost work Tractor Supply is already pursuing, including SG&A control, tariff refund deployment, vendor support and the Nampa automated facility that is targeted to add about 20 basis points to gross margin once it is fully contributing.
On earnings, analysts expect Tractor Supply to move from US$977.3m in earnings today to US$1.2b by around 2029, which is an increase of about US$220m. That change assumes the retailer can translate modestly higher margins and a slightly smaller share count into higher net income without relying on aggressive store growth.
Valuation work in the consensus report links those earnings forecasts to a 2029 P/E of 19.6x, compared with 18.5x today and an industry figure of 16.5x for US Specialty Retail. The gap suggests that the current investment narrative depends on Tractor Supply maintaining above-sector economics if it delivers on revenue growth, margin repair and the ongoing rationalisation of underperforming Petsense locations.
Tractor Supply's narrative outlines US$18.2b revenue and US$1.2b earnings by 2029. This is based on 4.6% yearly revenue growth and requires about a US$220m earnings increase from US$977.3m.
Uncover why Tractor Supply's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Tractor Supply focuses on pet as a long term catalyst. The most optimistic analysts were estimating about US$18.5b of revenue and US$1.3b of earnings by 2029 before this reaffirmed guidance. That view assumes pet subscriptions, fresh food and Rx services meaningfully lift results. You can compare that outlook with the latest margin focused update and decide which story feels closer to your own expectations, knowing both analyst playbooks may change after the new information is incorporated.
Explore 4 other Tractor Supply fair value estimates, including one that suggests there could be as much as 34% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tractor Supply research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tractor Supply. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tractor Supply's overall financial health at a glance.
Looking For More Ideas Beyond Tractor Supply?
If the Tractor Supply story has sharpened your thinking, use that same lens on a wider set of businesses. A curated screener can help you filter for balance sheet strength, income potential, or mispriced quality so you are not relying on one retailer to carry your whole thesis.
- If capital preservation is high on your list, start with a 30 resilient stocks with low risk scores that focuses on resilient businesses with lower risk scores and steadier fundamentals.
- For investors who prize dependable income, scan a curated group of higher yielding stocks through our 5 dividend fortresses and see which payouts line up with your goals.
- When you want to cast a wider net for quality at a reasonable price, broaden your watchlist with a 21 high quality undiscovered gems that surfaces lesser known companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com