


EN
3 UK Stocks For Investors Watching The Shift From High Street To Online Payments
As TG Jones shutters high street stores and post offices disappear from big retail chains, daily services that once felt basic now look uncertain, and that kind of disruption often reshapes where money flows. Investors who spot where parcels, payments and ecommerce activity might reroute may catch new winners early or sidestep future headaches. This article unpacks that story and looks at three UK digital commerce and logistics stocks exposed to this shift.
The three stocks below are just a starting sample, and the full screen on Simply Wall St flags 10 more UK digital commerce and logistics companies with equally compelling narratives that are not covered here.
If you want to identify, compare and analyze the wider opportunity set, head straight into the UK Digital Commerce & Logistics Enablement screener
Fonix (AIM:FNX)
Fonix plugs directly into the UK Digital Commerce & Logistics Enablement theme by handling carrier billing, online payments and messaging for digital services. It generated about £83 million from facilitating mobile payments and messaging, and the stock is valued at roughly £171 million.
Fonix is wired into the shift away from physical branches, processing mobile payments and messaging across media, gaming, charity and e-mobility in the UK and Europe as more transactions move online. Strong profitability and high reported returns on equity support that role, although one unseen pressure could matter a lot for how far those economics stretch.
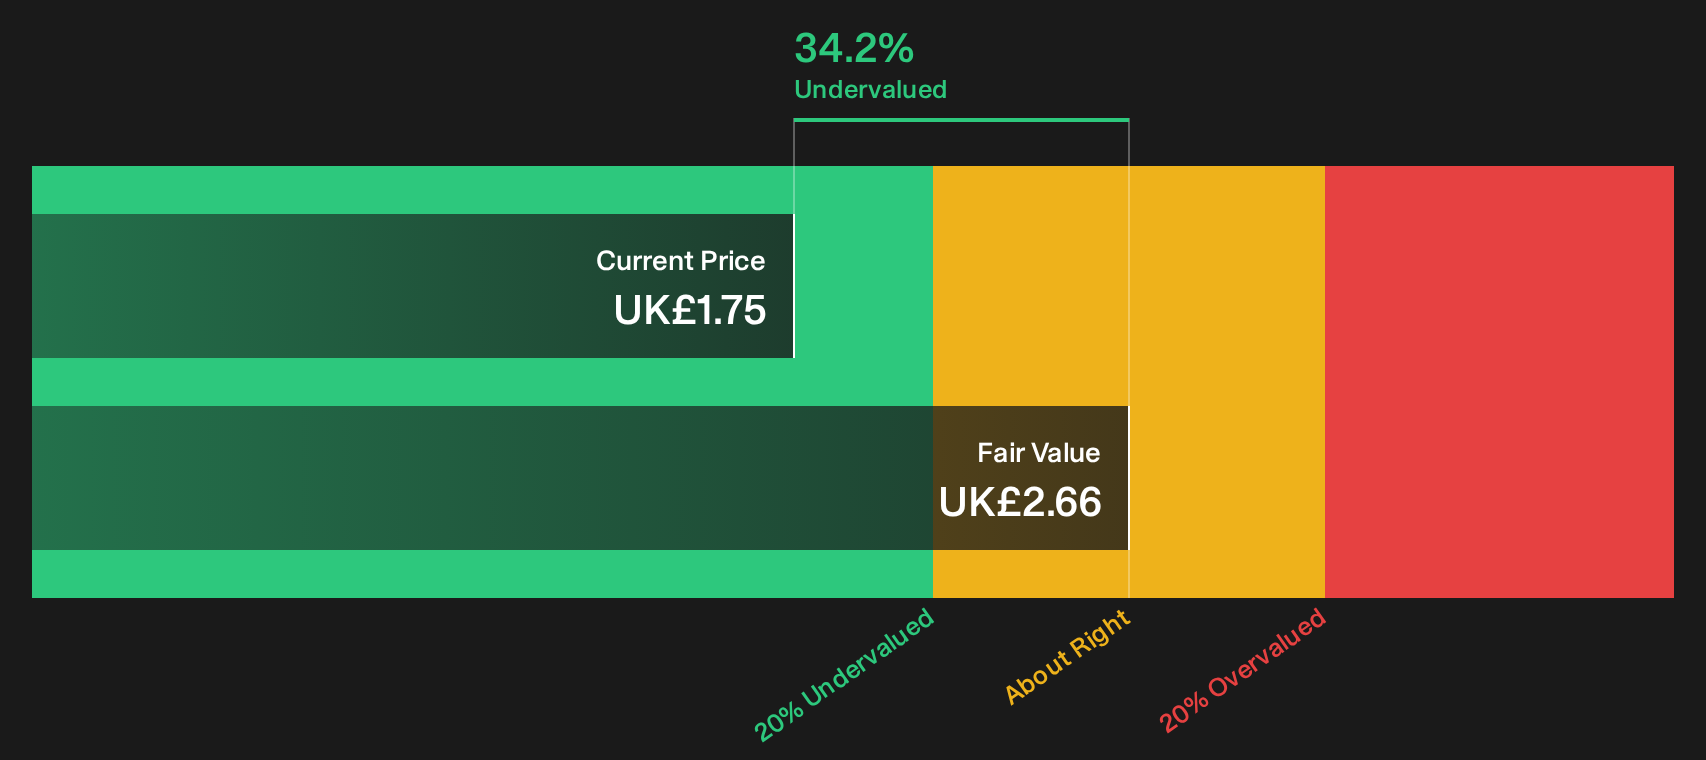
That pressure point is exactly what the DCF valuation analysis for Fonix weighs up, so you can see how Fonix’s current price lines up with those rich margins.
AO World (LSE:AO.)
AO World is plugged directly into the shift from high street counters to online checkouts, using its ecommerce platform and delivery network to sell and service big-ticket household tech as more shoppers order appliances from their sofa instead of a store.
AO World runs UK ecommerce sites for fridges, freezers and other domestic appliances, generating about £1.27b from online retailing of appliances and services, and the stock is valued at roughly £515 million.
Management are rolling out a multi year reduction in cost to serve, including AI enabled systems, low capex warehouse robotics and a shift of most contact centre roles to South Africa. This is already generating annualised savings and is aimed at lifting net margins as volumes grow.
What happens to AO World’s profitability if one key part of that plan does not deliver the savings or service quality management expects?
If that tension between cost savings and service quality is exactly what interests you, the full narrative for AO World shows where AO World could still surprise the market.

PayPoint (LSE:PAY)
PayPoint plugs straight into the UK Digital Commerce & Logistics Enablement theme, wiring card payments, bill settlement, cash access and parcel pickups into everyday retail journeys as more transactions move away from traditional bank and post office counters.
PayPoint generates about £179 million from its core payments and services arm and roughly £158 million from Love2shop vouchers and e-codes, with the group valued at around £421 million.
Although PayPoint is reporting record underlying profit before tax, the decline in PayPoint segment profits to £51.1m in FY'26 while segment revenues rose suggests that mix shift toward digital services is not yet translating into stronger unit economics.
The key question is whether one quieter shift inside PayPoint’s growing digital and parcel rails ultimately sharpens or squeezes those future margins.
Whether that shift sharpens or squeezes PayPoint’s economics, the full narrative for PayPoint maps how parcel rails, vouchers and payments could be quietly accelerating a very different profit mix.

Seeking Alternatives Before The Crowd
Fresh themes move fast. The most interesting stocks can see momentum build, sentiment flip and entry windows close while the data is still under the radar for now, so act now.
- Spot potential turnarounds early and scan the 8 high quality undervalued stocks before prices reflect improving balance sheets and cash flows, then decide which stories deserve a place on your watchlist.
- Track real earnings power and review the 39 profitable AI stocks that aren't just burning cash that pair AI narratives with existing profits, not just promises, before enthusiasm sends valuations flying.
- Target resilient cash generators and use the 5 dividend fortresses while yields stay elevated and payout histories are still being priced as if they might be temporary.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com