


EN
Ondas (ONDS) Could Be 21% Undervalued As Losses And Margin Pressure Test Sentiment
Recent commentary from Ondas (ONDS) management has put operational issues front and center, with ongoing losses, negative operating margins, margin pressure from acquisitions, and supply chain timing risks drawing fresh attention from investors.
Ondas shares have bounced 2.99% on a 1 day basis and 2.65% over the past week. However, the 30 day share price return is down 16.22% and the year to date share price return is down 43.74%. The 3 year total shareholder return is very large, reflecting a jumpy history in which fresh commentary on losses, margins, and supply chain timing quickly shifts how investors price both growth potential and execution risk around the current US$6.20 level.
Compare Ondas with a curated set of peers by scanning 95 robotics and automation stocks, which could be better balancing growth ambitions with cost control and execution risk.
Ondas has slipped hard this year even after the recent bounce, so the real question now is whether current pricing already reflects the execution issues or whether it makes more sense to be patient and wait for a lower entry before looking at valuation.
Most Popular Narrative: 21% Undervalued
According to the most followed valuation narrative, Ondas could be worth closer to $7.89 per share compared with the recent $6.20 close, which puts all the recent talk about execution risk in a different light.
If I consider a 3y growth of 80% (I don't think they can keep the 13 fold growth), which should be possible with a 20% profit margin (currently 49.25%), I think a FV of 7.89 is achievable and makes it 13.2% undervalued with a risk level of 10%.
If you were to adjust the risk to 15% because of the nature of acquisition based growth, then FV would sit at 6.9, which is fairly valued to the current price today (9th October 2026).
See why 13 investors see Ondas as 21% undervalued.
Result: Fair Value of $7.89 (UNDERVALUED)
Still, Ondas relies heavily on acquisitions and a concentrated customer base, so any integration stumble or contract setback could quickly undercut this undervaluation case.
Find out about the key risks to this Ondas narrative.
Another View: What Ondas’s P/E Ratio Is Signalling
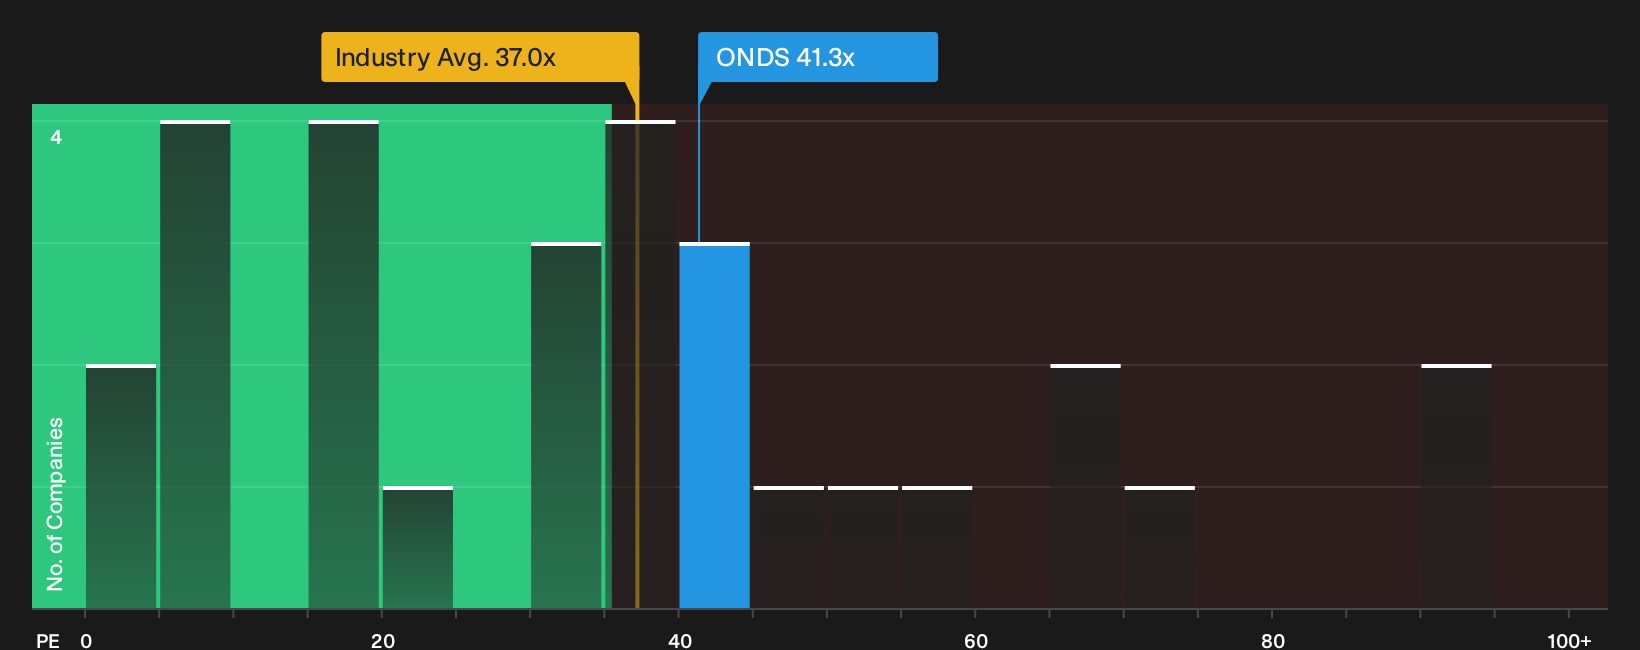
The fair value narrative paints Ondas as undervalued, yet the P/E ratio tells a tougher story. At roughly 41.3x earnings, the stock trades well above its fair ratio of 26.6x and also above the broader US Communications sector on 37x. That gap points to real valuation risk if expectations cool.
Against closer peers on about 48.8x, the multiple looks more middle of the pack. This raises the key question for you as an investor: Is Ondas priced for fragile optimism, or simply in line with a high growth, high execution risk peer set?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by mixed signals on Ondas and what they imply for risk and opportunity? Move quickly, review the underlying numbers, and weigh the 3 key rewards and 4 important warning signs.
Looking for more Ondas investment ideas beyond this stock?
If you stop with Ondas, you risk missing other opportunities that better match your risk comfort, return goals, and appetite for balance sheet strength.
- Target potential value opportunities early by scanning the 27 high quality undervalued stocks that combine quality fundamentals with pricing that may not fully reflect them yet.
- Prioritise durability and capital protection by reviewing a 30 resilient stocks with low risk scores that screens for resilience when markets turn volatile.
- Raise the bar on financial strength by focusing on a list of solid balance sheet and fundamentals (25 results) that filters for healthier leverage and liquidity profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com