


EN
Paychex (PAYX) Could Be 36% Below Fair Value As Q1 Beats Lift Momentum
Paychex (PAYX) has been in focus after fiscal Q1 2027 results topped earnings and revenue expectations, supported by stronger guidance for its PEO and Insurance Solutions business and the ongoing rollout of new WISE-powered services.
The stronger fiscal Q1 and a cluster of WISE-driven product launches have coincided with a shift in sentiment, with Paychex’s 30-day share price return of 12.97% and 7-day gain of 5.74% pointing to building momentum, even as 1-year total shareholder return slipped 1.09% and the 5-year total shareholder return sits at 11.22%.
Scan how Paychex’s AI and HCM momentum compares with a curated group of peers by reviewing the 39 profitable AI stocks that aren't just burning cash that pair real earnings with similar themes.
Bulls see Paychex’s WISE rollouts and PEO guidance as the start of a stronger earnings story. Bears point to modest long term returns and recent gains. Which case does the current valuation lean toward?
Most Popular Narrative: 4% Overvalued
Paychex closed at $118.04, a little above the most followed narrative fair value of $113.93. This fair value is based on a 7.6% discount rate and a detailed set of growth and margin assumptions.
The ongoing mix shift as Paychex upgrades clients from ASO into higher revenue PEO offerings, with ASO to PEO conversions running at about 2x internal expectations and each upgrade generating roughly 3.5x more revenue per client, creates room for future PEO and Insurance Solutions revenue growth and higher profit contribution.
See why 54 investors see Paychex as 4% overvalued.
Result: Fair Value of $113.93 (OVERVALUED)
Still, the Paychex story can crack if Paycor integration underdelivers or if slower Management Solutions growth drags overall revenue below what the narrative assumes.
Find out about the key risks to this Paychex narrative.
Another View: SWS DCF Flags PAYX As Undervalued
The analyst narrative pegs Paychex at 4% overvalued relative to a $113.93 fair value, yet the Simply Wall St DCF model paints a different picture. On that cash flow view, PAYX at $118.04 trades about 36.1% below an estimated value of $184.84. Which yardstick do you trust more: the earnings multiple or the cash generation math?
Look into how the SWS DCF model arrives at its fair value.
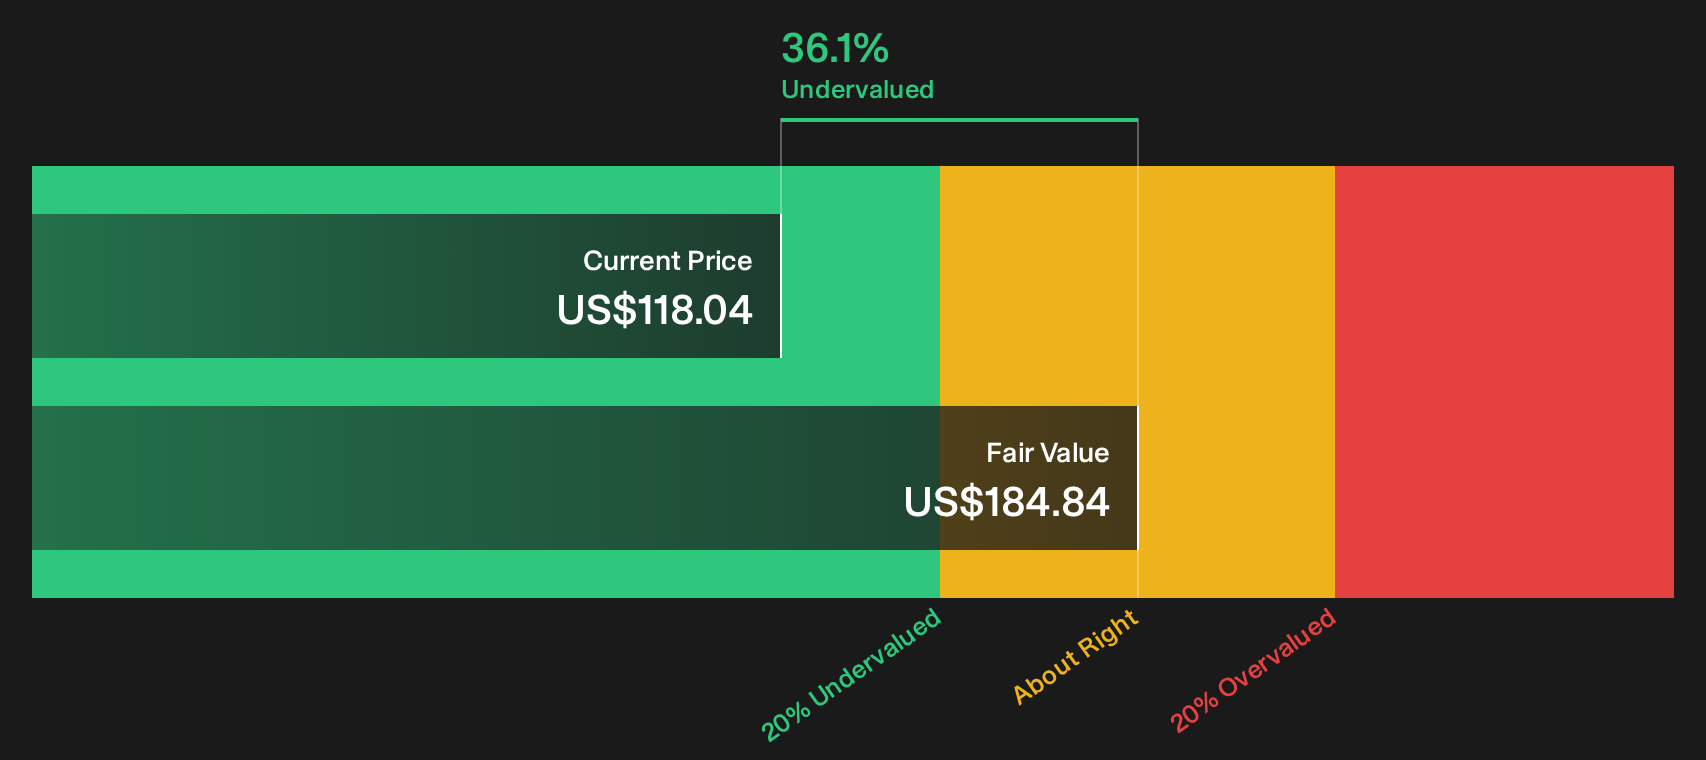
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paychex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Paychex’s value and outlook make this a good moment to examine the numbers and sentiment more closely. To see both sides of that debate in one place, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paychex?
Do not stop with Paychex. Broaden your watchlist with fresh opportunities so you are not caught watching from the sidelines when the next move happens.
- Target potential mispricing by scanning companies that pass rigorous value and quality checks through the 27 high quality undervalued stocks.
- Strengthen income potential by reviewing the 5 dividend fortresses that combine elevated yields with an emphasis on durability.
- Add resilience to your watchlist by assessing the 30 resilient stocks with low risk scores that score well on financial stability and downside risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com