


EN
Corning (GLW) Gains Attention On AI Demand, Is It Still 35% Undervalued?
Recent enthusiasm around Corning (GLW) has centered on its role in AI infrastructure, with investors watching how upcoming earnings and long-term supply deals with major tech customers might influence the stock’s risk and reward profile.
Corning’s recent pullback, with the share price down 6.3% over the past week and almost 20% over 30 days, comes after a sharp rally that still leaves the year-to-date share price return at 36.4% and the 3-year total shareholder return close to 4x. This suggests momentum has cooled, even as investors weigh AI-driven growth expectations, the at-the-market equity offering, and upcoming earnings against that strong longer-term performance.
Spot fresh AI-infrastructure opportunities around Corning by scanning our hand-picked list of 55 AI infrastructure stocks.The share price reset, the analyst target and intrinsic value estimates now point in different directions. For Corning, which of these benchmarks is closest to a reasonable fair value today?
Most Popular Narrative: 34.9% Undervalued
Corning’s most followed narrative pegs fair value at $189.94, well above the recent $123.69 close. This puts the current pullback against a thesis built on long duration AI, solar and photonics demand.
The main thing that has to go right is that Corning converts its large optical and solar order book, customer prepayments and long duration supply agreements into the Springboard 20 30 40 plan outcomes with higher operating margins and return on invested capital.
The numbers imply that Corning’s current valuation treats the stock as if execution risk, equity issuance and mixed end market conditions fully offset the multibillion long term growth opportunities in AI data centers, U.S. solar and photonics. This underpins the view that the shares are undervalued.
See why 105 investors see Corning as 35% undervalued.
Result: Fair Value of $189.94 (UNDERVALUED)
Still, the story around Corning can change quickly if solar execution stumbles again or if further equity issuance leads to heavier earnings dilution than investors expect.
Find out about the key risks to this Corning narrative.
Another View: What Corning’s P/E Is Saying
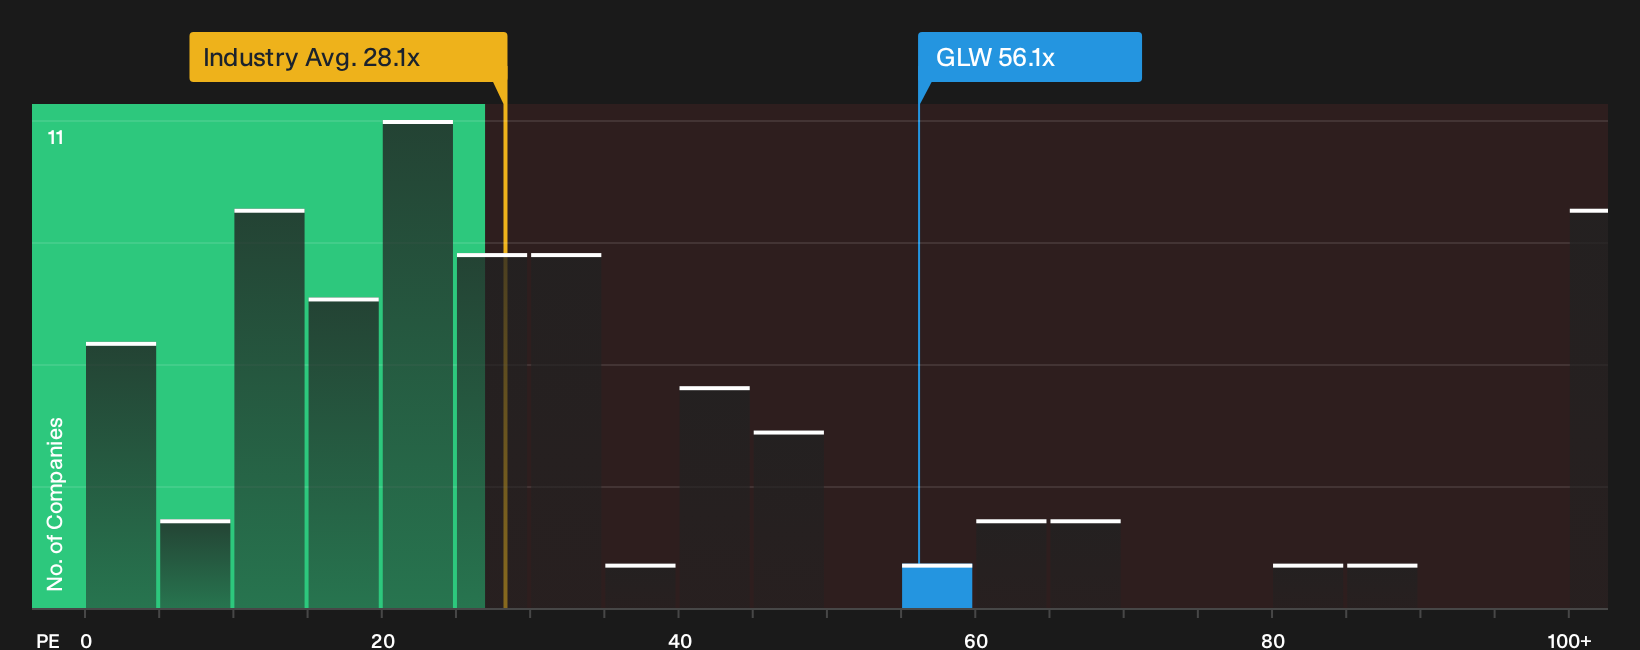
There is a very different message coming from Corning’s valuation on simple earnings multiples. The stock trades on a P/E of 56.1x, which is roughly double the US Electronic industry at 28.1x and slightly above an estimated fair ratio of 52.6x. That mix points to a rich price where any stumble on earnings or AI infrastructure demand could matter a lot for future returns.
For investors weighing those signals against the narrative fair value, the key question is whether today’s rich multiple reflects future growth or just stretches the margin for error too far. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Corning is split, and you do not have to pick a side blindly when real data is available to you in one place. Move quickly and review the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Corning?
If you stop with Corning, you miss the chance to scan other clear setups where quality, value, and resilience might better match your own playbook.
- Target resilient upside by checking companies flagged in the 30 resilient stocks with low risk scores that may handle shocks more steadily than the wider market.
- Hunt for quality at a sensible entry point by scanning the 27 high quality undervalued stocks that filters for fundamentals first, excitement second.
- Build a sturdier core in your portfolio by reviewing the list of solid balance sheet and fundamentals (25 results) that screens for stronger finances and cleaner balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com