


EN
What Bank OZK (OZK)'s Earnings Beat Means For Shareholders
- Bank OZK reported third quarter 2026 basic earnings per share of US$1.50 from continuing operations, above analyst expectations, alongside slight year-on-year declines in net income and net interest income for both the quarter and year-to-date period.
- The bank highlighted rapid repayments in its Real Estate Specialties Group and pointed to Corporate & Institutional Banking as a key future growth engine, signaling an active shift in how it earns interest income and fees.
- We will look at how Bank OZK's investment narrative is affected by outperformance on earnings per share and planned Corporate & Institutional Banking expansion.
Bank OZK Investment Narrative Recap
To own Bank OZK, you need to be comfortable with a bank that is shrinking its large Real Estate Specialties Group while trying to build a more diversified Corporate & Institutional Banking engine. The short term swing factor is whether loan repayments stay unusually high, which would keep earning assets flatter and make it harder for net interest income to meaningfully improve.
The most immediate risk remains commercial real estate concentration and problem credits, including foreclosed assets and large legacy projects that can pressure provisions. The latest quarter did not radically change that equation, so the story still hinges on how cleanly OZK can rebalance its loan book while holding earnings steady.
The Q3 2026 update is central here. Bank OZK reported basic earnings per share from continuing operations of US$1.50, which beat some expectations even as net interest income and net income sat below the prior year for both the quarter and the first nine months. That mix of resilience and pressure frames how much room management has to keep shifting the business.
Rapid repayments in the real estate group, a lower 2026 loan growth range of 3% to 5%, and higher foreclosed assets show how repayment and credit trends can pull against the Corporate & Institutional Banking buildout. For catalysts to matter, investors will likely watch whether new CIB lending and fee income can gradually offset these repayment headwinds without requiring materially higher loss charges.
What Analysts Are Building Into The Bank OZK Story
Analysts are effectively sketching out a slower but still constructive transition period for Bank OZK, where the loan book reshuffle coexists with measured growth rather than a surge in activity. Their models plug in 9.5% annual revenue expansion over the next three years, paired with a step down in profit margins from 43.5% today to 33.8% by around 2029. That combination assumes the bank can grow its top line while carrying a leaner profitability profile as the mix shifts toward Corporate & Institutional Banking and away from the heavier Real Estate Specialties Group exposure.
On the earnings line, the consensus view points to profit of US$690.2 million by around 2029, compared with US$675.1 million today. The change is modest in absolute dollar terms, which underlines how much of the thesis rests on the quality and composition of earnings rather than a dramatic surge in profit. Analysts also factor in share count shrinking by 2.54% per year over the next three years, so part of the per share earnings story comes from buybacks rather than only from higher aggregate income.
Valuation assumptions then build off that earnings path. The analyst group is using those 2029 numbers to anchor a P/E of 9.7x, which compares with an estimated 7.0x today for Bank OZK and 11.4x for the broader US banks peer set cited in the report. That still embeds a discount to the industry level while assuming the multiple rises from the current starting point. The market view sketched here therefore depends on investors assigning a higher price tag to each dollar of future earnings if the business mix looks cleaner and more diversified.
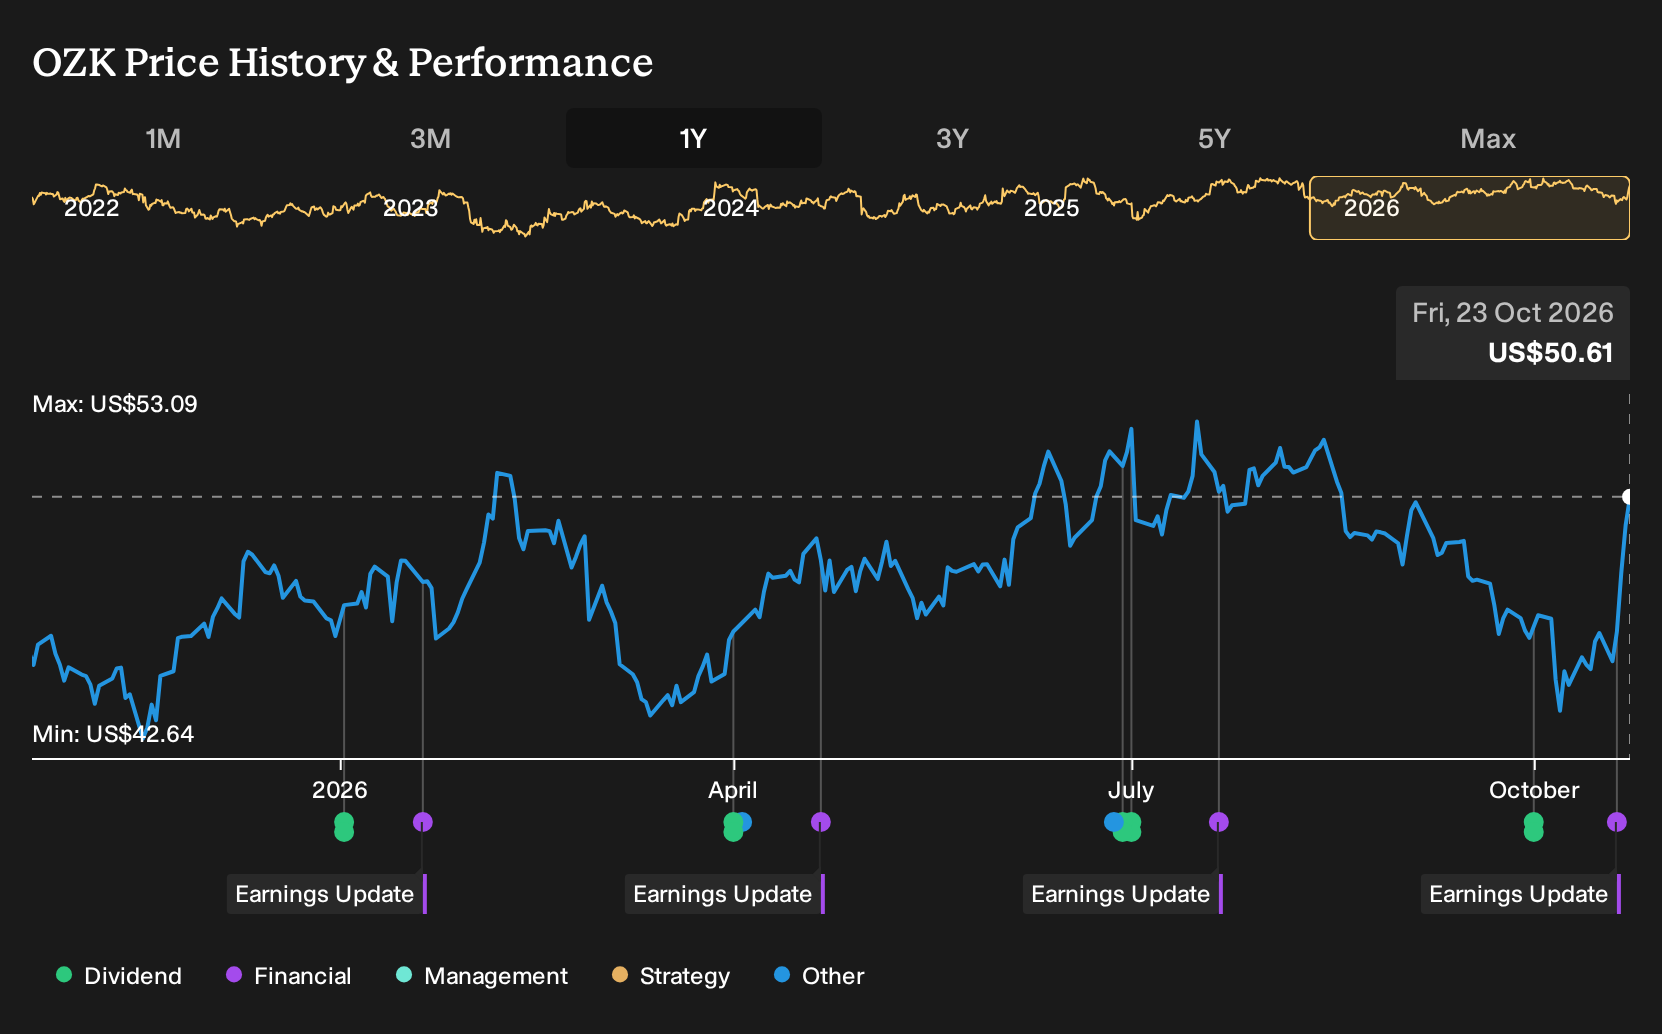
The same framework bakes in revenues of about US$2.0 billion and earnings of US$690.2 million by 2029, then layers on a discount rate of roughly 7.2% to bring those future figures back to today. With a consensus price target of US$53.78 versus a current share price of US$43.56, the implied upside in that model sits at about 19%, although individual analyst targets stretch from US$40.00 up to US$65.00. For you as an investor, the real question is whether the assumed revenue growth, margin compression, and CIB driven loan mix actually feel realistic when mapped against your own view of credit risk and repayment trends.
Bank OZK's narrative projects US$2.0 billion revenue and US$690.2 million earnings by 2029. This requires 9.5% yearly revenue growth and an earnings increase of about US$15 million from current earnings of US$675.1 million.
Uncover why Bank OZK's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view places Bank OZK’s share repurchase plan at the center of the story. The most optimistic analysts were estimating about US$2.1b of revenue and US$674.3 million of earnings by 2029 before this earnings release, and they viewed buybacks and CIB growth as the key potential upside factors. That is a much more optimistic angle than the baseline. Use this latest quarter as a prompt to compare those assumptions with your own and decide which narrative feels closer to your expectations.
Explore 4 other Bank OZK fair value estimates, including one that suggests as much as 132% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank OZK research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Bank OZK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank OZK's overall financial health at a glance.
Looking for more investment ideas beyond Bank OZK?
If the Bank OZK story has sharpened your thinking about risk, reward, and balance sheet strength, use that same lens to widen your opportunity set with the Simply Wall St Screener.
- For investors who want steadier sleep-at-night holdings, start by scanning a 30 resilient stocks with low risk scores that focus on resilience when conditions get choppy.
- If your priority is financial strength and flexibility, sort through a list of solid balance sheet and fundamentals (25 results) that can handle tougher credit cycles without relying on aggressive funding.
- When you are hunting for under-the-radar opportunities, work through a 21 high quality undiscovered gems that pair strong fundamentals with relatively low attention from the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com