


EN
How Investors May Respond To Owens Corning (OC) Weaker Earnings Outlook
- Recent coverage on Owens Corning highlights softer earnings expectations for the current quarter, with analysts pointing to a projected year-over-year decline and weaker demand in key housing and renovation markets.
- An additional angle is how this softer outlook arrives just as Owens Corning is funding new roofing and insulation capacity while still targeting resilient EBITDA margins through the cycle.
- We will now examine how Owens Corning's investment narrative holds up in light of softer near term earnings expectations.
Stress test your thesis on Owens Corning by comparing it with a curated list of solid balance sheet and fundamentals (25 results) that may handle softer demand and margin pressure differently.
Owens Corning Investment Narrative Recap
To own Owens Corning, you need to believe the residential focused Roofing, Insulation and Doors portfolio can keep generating solid cash flow even when housing and renovation demand cools. The big near term swing factor is how quickly volumes and pricing in North America and Europe stabilise. Recent softer earnings expectations mostly reinforce that end market conditions remain tough rather than changing the core thesis.
The biggest operational risk right now is pressure on pricing and margins in what has been described as an oversupplied industry, especially with new capacity coming. A secondary concern is whether Owens Corning can comfortably fund both planned cash returns and growth projects if softness in Roofing volumes and revenue persists.
The most relevant piece of context for this news is management’s decision to commit about US$800 million of 2026 capital, with more than half earmarked for productivity and growth projects, including the Kansas City fiberglass line and an Alabama roofing plant. Those builds matter because they add capacity into markets already facing weaker demand and pricing pressure.
If execution goes to plan, these projects could support Owens Corning’s aim to keep enterprise EBITDA margins in the low to mid 20% range through the cycle by lowering unit costs and supporting future volume. The flip side is that, in a softer demand backdrop, extra supply can amplify pricing risk and make it harder to balance debt levels, dividend commitments and that roughly US$2b capital return plan for 2025 and 2026.
Owens Corning’s current analyst blueprint points to revenues of US$10.7b and earnings of US$1.6b by 2029. These projections are built on assumed yearly top line growth of 2.8% and a shift from today’s earnings loss of US$429.0m to that US$1.6b profit, which is an increase of roughly US$2.0b over the period.
Uncover why Owens Corning's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
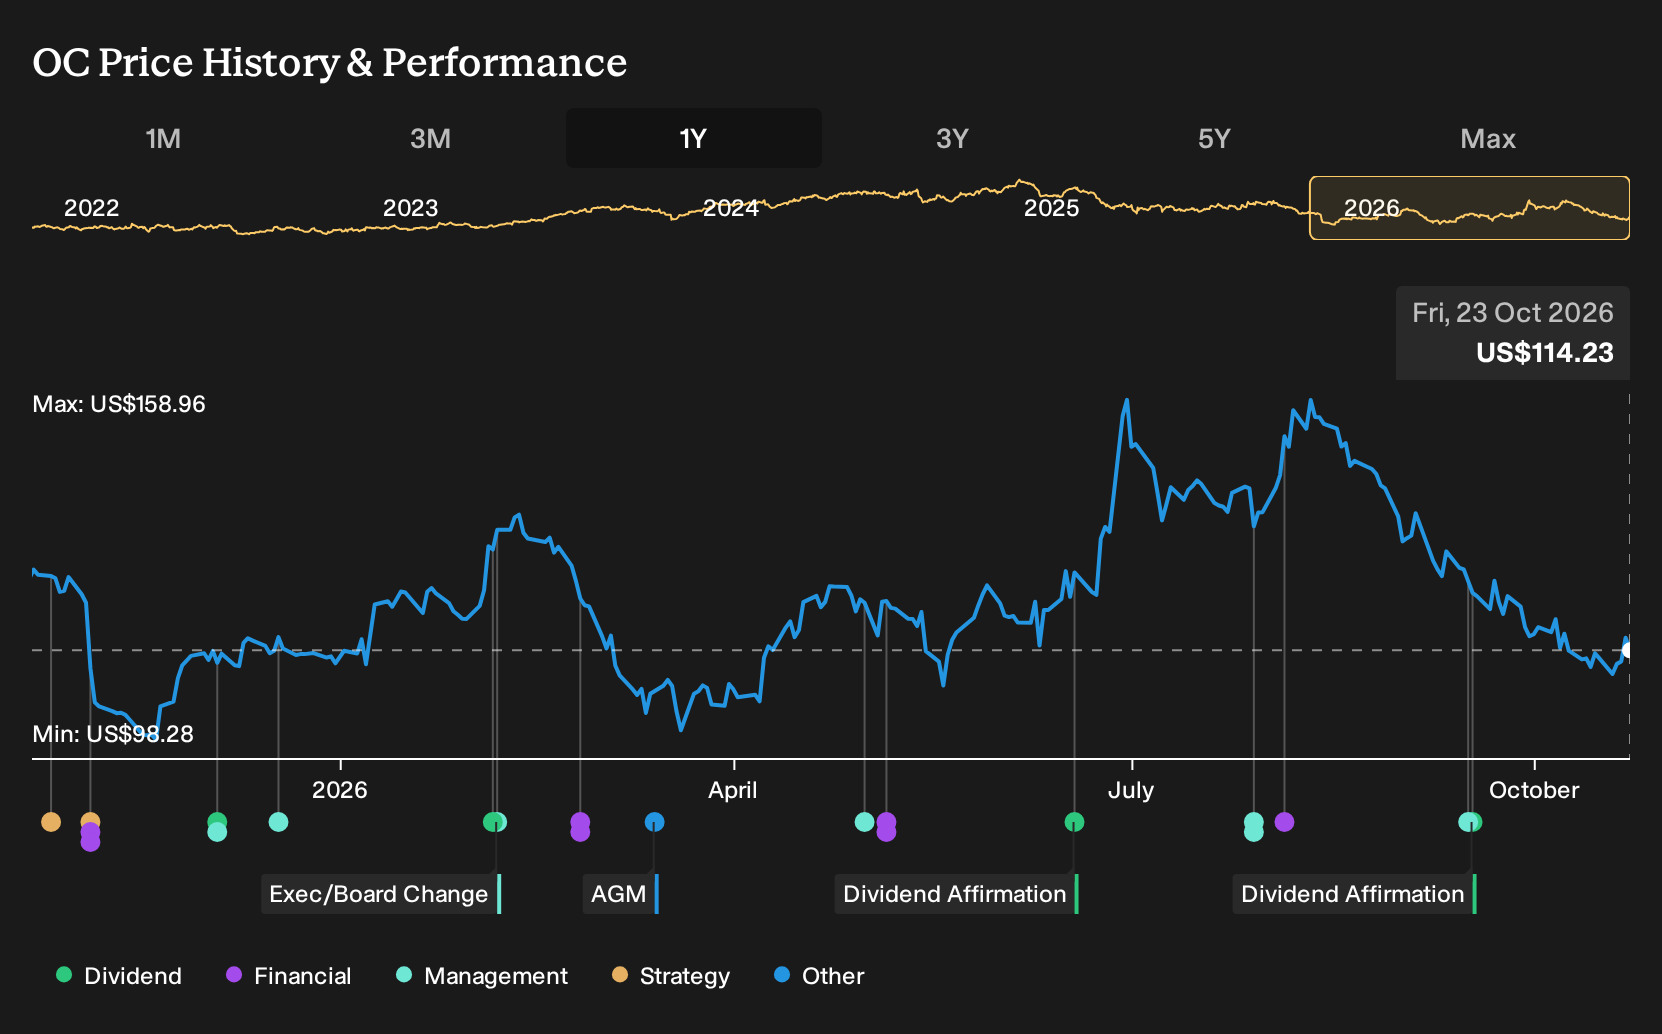
Exploring Other Perspectives
You are seeing two very different stories about Owens Corning. The bullish analysts lean on future roofing capacity as a key positive, backing 5.0% yearly revenue growth and earnings of about US$1.7b by 2029, versus the broader group closer to US$1.6b. With the latest weaker earnings signals, both narratives may shift.
Explore 2 other Owens Corning fair value estimates, including one that suggests as much as 58% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Owens Corning research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Owens Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Owens Corning's overall financial health at a glance.
Looking for more Owens Corning style investment ideas?
If the Owens Corning story has you thinking about balance sheets, income resilience and where to put fresh capital to work, it can help to scan a wider field of opportunities using a consistent framework.
- If you want potential upside with stronger financial footing, start by reviewing a curated 27 high quality undervalued stocks that may align better with your risk and return preferences.
- If capital preservation matters just as much as return potential, focus on steadier profiles through a targeted 30 resilient stocks with low risk scores that filters out weaker balance sheets.
- If you are hunting for less crowded opportunities, widen your search with a focused 21 high quality undiscovered gems that surfaces companies many investors might not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com