


EN
Nucor (NUE) Is Getting Fresh Attention, But What Is Behind It?
Nucor (NUE) just put more capital behind its utility infrastructure push, committing fresh money to expand its Towers & Structures operations in Indiana and Alabama as grid spending gathers momentum.
Nucor’s latest grid focused investment lands after a powerful run in the stock, with the share price delivering a 52.37% year to date share price return and a very strong 88.27% total shareholder return over the past 12 months, signalling momentum that investors are now testing against the upcoming 26 October earnings update and earlier decisions to pour more money into long lead utility infrastructure projects.
Spot emerging grid and infrastructure plays alongside Nucor by scanning our hand picked 42 power grid technology and infrastructure stocks.Nucor now trades only a single digit percentage below the average analyst target, yet well above some intrinsic value estimates. Is the recent grid fueled surge already pricing in most of the upside, or is it not nearly enough?
Most Popular Narrative: 9% Undervalued
Nucor’s most followed narrative pegs fair value at about $283.63, above the last close of $258.11. This frames the current grid build out against a larger multiyear capital story that investors are still pricing through.
Nucor's multiyear capital program of roughly US$15b to US$20b, with several mills and downstream assets already EBITDA positive and capital expenditure guiding to about US$2.5b in 2026, is moving from the build phase toward cash generation, which can support higher earnings and free cash flow.
See why 104 investors see Nucor as 9% undervalued.
Result: Fair Value of $283.63 (UNDERVALUED)
Still, the bullish Nucor narrative can crack if nonresidential and infrastructure demand softens, or if big projects like the West Virginia mill stumble on execution.
Find out about the key risks to this Nucor narrative.
Another View On Nucor’s Valuation
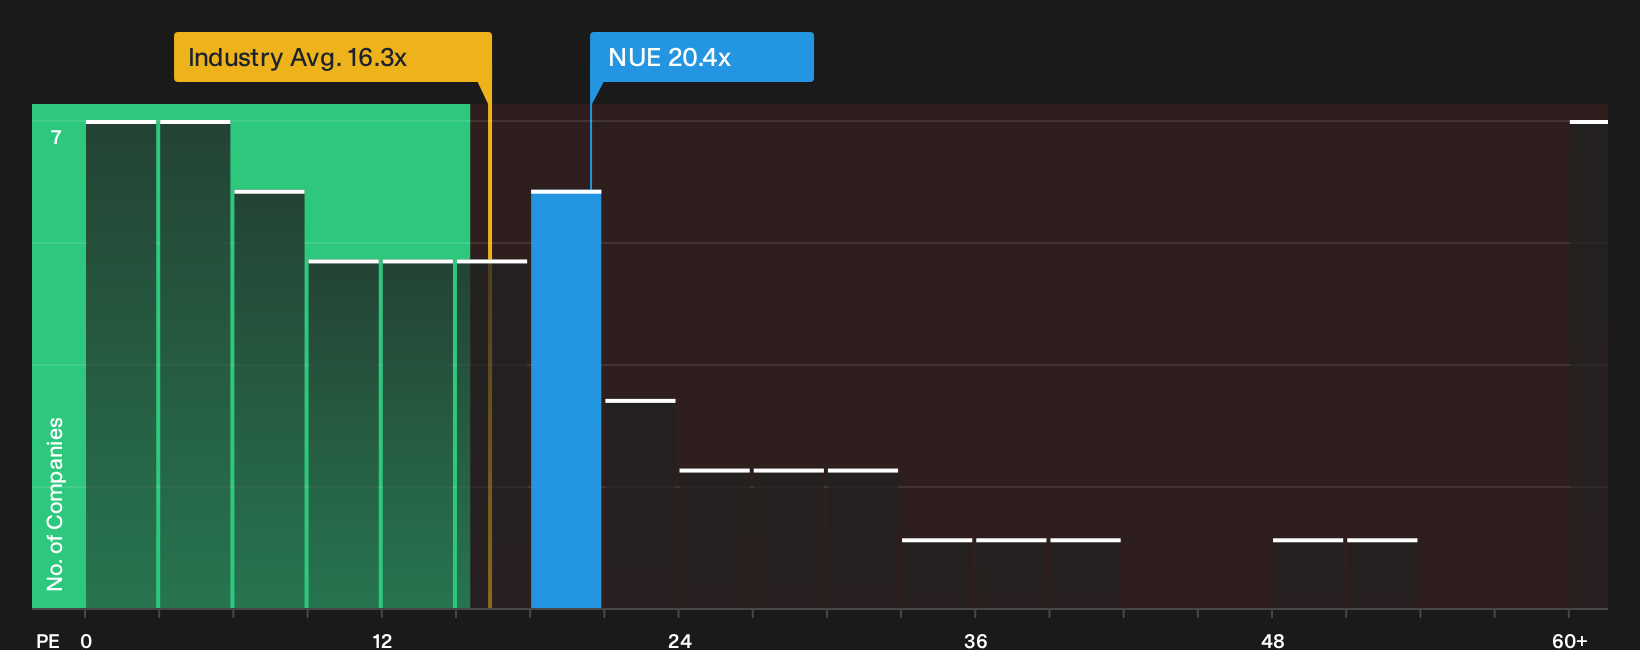
The narrative model sees Nucor as about 9% undervalued at a fair value near $283.63. Step back to simple pricing though and the picture shifts. Nucor trades on a 20.4x P/E, richer than both peers at 15.8x and the US Metals and Mining group at 16.3x, even though the fair ratio is 22.5x. That premium suggests the market is already paying up for quality, so the question is whether you see that as valuation risk or a gap that could still close.
See what the numbers say about this price in more detail by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in the Nucor story is split, with enthusiasm for the grid build out sitting right beside pockets of concern about execution and demand. Act while the data is fresh and weigh both sides for yourself by running through the 3 key rewards and 1 important warning sign
Looking For More Nucor-Style Investment Ideas?
If Nucor has you thinking more broadly about grid, infrastructure and resilient balance sheets, do not stop at a single ticker. Fresh ideas are often just one screen away.
- Target potential mispricing by scanning a curated pool of resilient businesses with solid fundamentals through the 27 high quality undervalued stocks.
- Build a more predictable income stream by searching for resilient payers in the 5 dividend fortresses.
- Reduce portfolio stress by focusing on financially conservative operators using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com