


EN
Is Ingram Micro Holding (INGM) A Bargain Following Its Xvantage Patent And Earnings Setup?
Why the new Xvantage patent matters for Ingram Micro Holding
The catalyst around Ingram Micro Holding (INGM) is clear. A new U.S. patent underpins its Xvantage AI platform, while investors also watch for a year-over-year earnings increase in the September 2026 quarter.
This pairing of a protected technology framework and an upcoming earnings release gives you two angles to think about: product optionality on one side, and shorter term profitability expectations on the other.
Recent trading around Ingram Micro Holding at US$27.69 reflects that the strong year to date share price return of 29.94% has cooled a little after a 90 day share price decline of 5.94%, even as the 1 year total shareholder return of 29.17% points to momentum that has built over a longer stretch.
Scan how Ingram Micro Holding compares with other AI infrastructure plays and see which peers are already pricing in similar earnings and product catalysts using our curated 55 AI infrastructure stocks.With Ingram Micro Holding up almost 30% over the past year yet easing back in recent months, the real decision is whether that sets up a reasonable entry now or argues for patience and a cheaper shot later.
Most Popular Narrative: 16.5% Undervalued
Against the last close at $27.69, the most followed valuation narrative for Ingram Micro Holding pins fair value at $33.17. This frames the recent pullback as a pricing gap that hinges on how the Xvantage and AI infrastructure story plays out.
Rapid adoption of AI driven enterprise solutions, supported by Xvantage, IDA and the new Sales Briefing Assistant, is expected to convert current proof of concept activity into scaled deployments that lift advanced solutions and services revenue while supporting higher quality earnings over time.
See why 1 investors see Ingram Micro Holding as 17% undervalued.
Result: Fair Value of $33.17 (UNDERVALUED)
Still, the Ingram Micro Holding story can break if low margin GPU and server deals crowd out richer SMB and cloud activity, or if Xvantage adoption stalls.
Find out about the key risks to this Ingram Micro Holding narrative.
Another View on Ingram Micro Holding: DCF Says Overvalued
The popular narrative tags Ingram Micro Holding as 16.5% undervalued at a $33.17 fair value. A different lens tells a very different story. Our DCF model estimates future cash flow value at $17.70 per share, which is well below the current $27.69 price and points to an overvalued reading instead.
The gap between a DCF value of $17.70 and a narrative fair value of $33.17 raises a basic question for you as an investor. Which set of assumptions about margins, reinvestment needs and long term cash generation feels closer to what Ingram Micro Holding can realistically deliver?
Look into how the SWS DCF model arrives at its fair value.
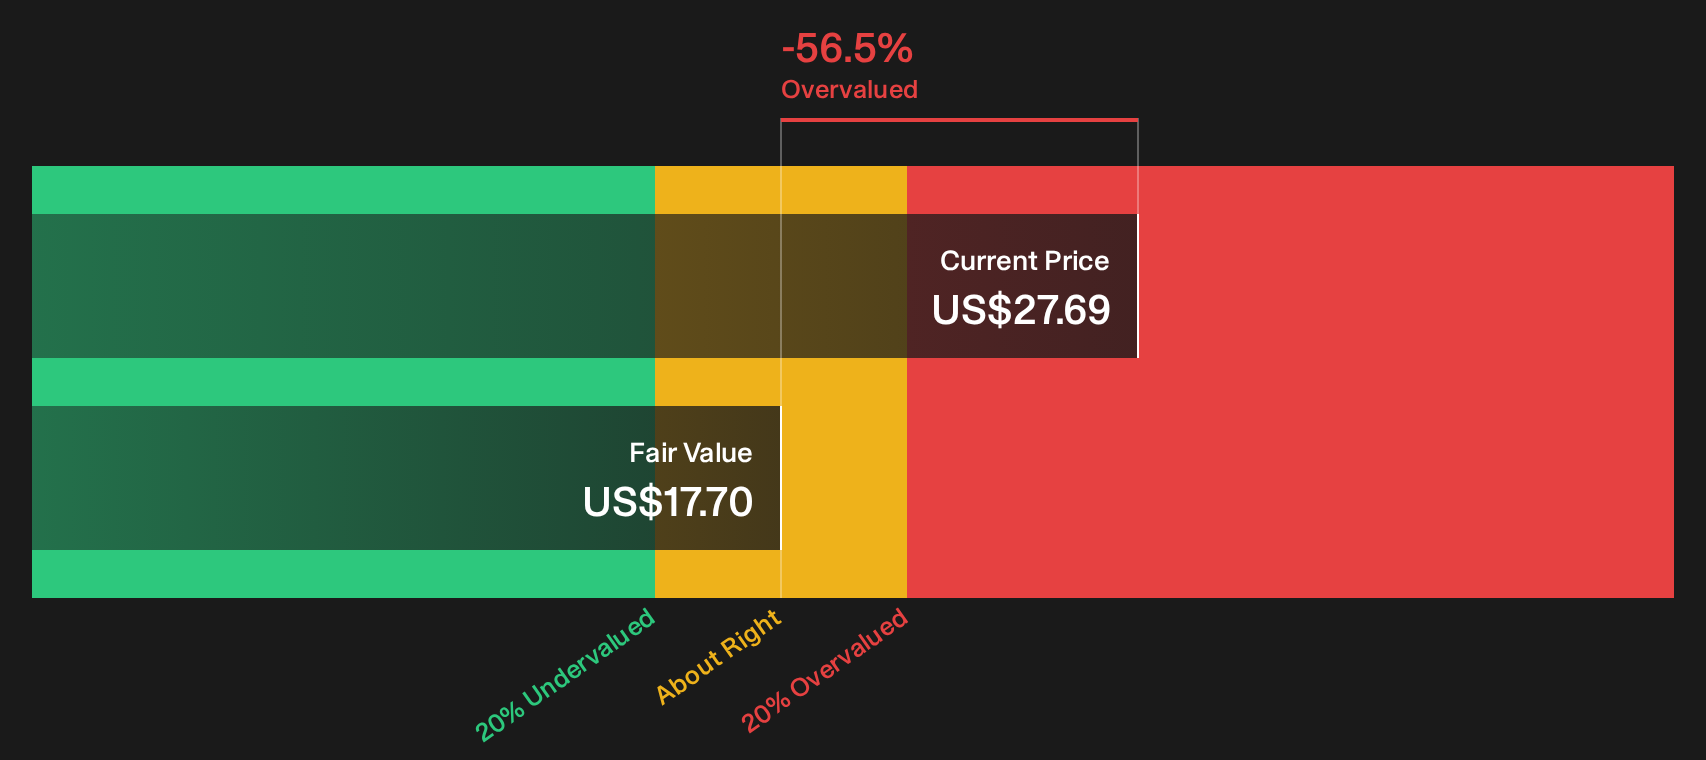
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ingram Micro Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ingram Micro Holding so far, right. If you want to move fast but still think for yourself, weigh both sides of the story through 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ingram Micro Holding?
Do not stop with a single ticker. Broaden your watchlist with fresh ideas surfaced by the Simply Wall St screener so you are not late to the next move.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (25 results) that filters for companies with stronger finances and cleaner fundamentals.
- Hunt for quality at a discount through the 27 high quality undervalued stocks that spotlights financially solid businesses trading below their assessed worth.
- Prioritise staying power with the 30 resilient stocks with low risk scores that highlights stocks flagged with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com