


EN
Meitu (SEHK:1357) Jumped, So What Is Driving Attention Now?
Meitu (SEHK:1357) has put AI content tools in the spotlight after Wink rolled out its HD Video Converter and MVLAND launched its Music Ads feature for rapid, social-first marketing videos.
The fresh AI releases arrive after a mixed run for Meitu, with the HK$3.655 share price jumping 6.56% on the day and 2.10% over the past week, yet sitting on a year-to-date share price loss of 50.81%. Over the past five years the total shareholder return is 133.46%, which suggests recent product momentum is being weighed against a longer, still positive investor journey.
Scan beyond Meitu and compare this AI content push with other hand-picked creators of digital tools using the 39 profitable AI stocks that aren't just burning cash as a starting universe.
After a sharp swing in Meitu’s share price against a backdrop of heavy year-to-date losses, the question now is simple: Does the current valuation still reward investors for leaning into this AI push, or has the easy upside already gone?
Most Popular Narrative: 53% Undervalued
Against Meitu's last close at HK$3.655, the most widely followed narrative pegs fair value around HK$7.72, which implies a steep valuation gap that hinges on how durable its AI and subscription story really is.
Successful integration of advanced AI features (AI Wardrobe, AI Flash, and RoboNeo) has significantly improved user engagement and willingness to pay, demonstrated by a 45.2% year-on-year revenue growth in the core Photo, Video, and Design (PVD) segment and a rising subscription rate, pointing to higher future ARPU and improved gross margins.
See why 6 investors see Meitu as 53% undervalued.
Based on this framework, analyst assumptions in the narrative tie that HK$7.72 fair value to forecast revenue growth of about 22.2% a year, earnings growth around 26.7% a year and a discount rate of roughly 9.1% applied to those future profits. The idea is that recurring income from AI driven imaging tools, higher subscription penetration and a forecast profit margin of about 27.4% eventually support a P/E multiple of 17.8x by around 2029.
Those inputs are not one way traffic. The same narrative flags risks around tougher competition in AI imaging, reliance on external large models, softer profitability outside Mainland China and structurally higher spend on talent and R&D, all of which could make that earnings path bumpier than modeled.
Result: Fair Value of HK$7.72 (UNDERVALUED)
Still, if competition in AI imaging accelerates or Meitu’s overseas monetization remains weak, the bullish narrative could quickly look too optimistic.
Find out about the key risks to this Meitu narrative.
Another View: What Meitu’s P/E Is Signalling
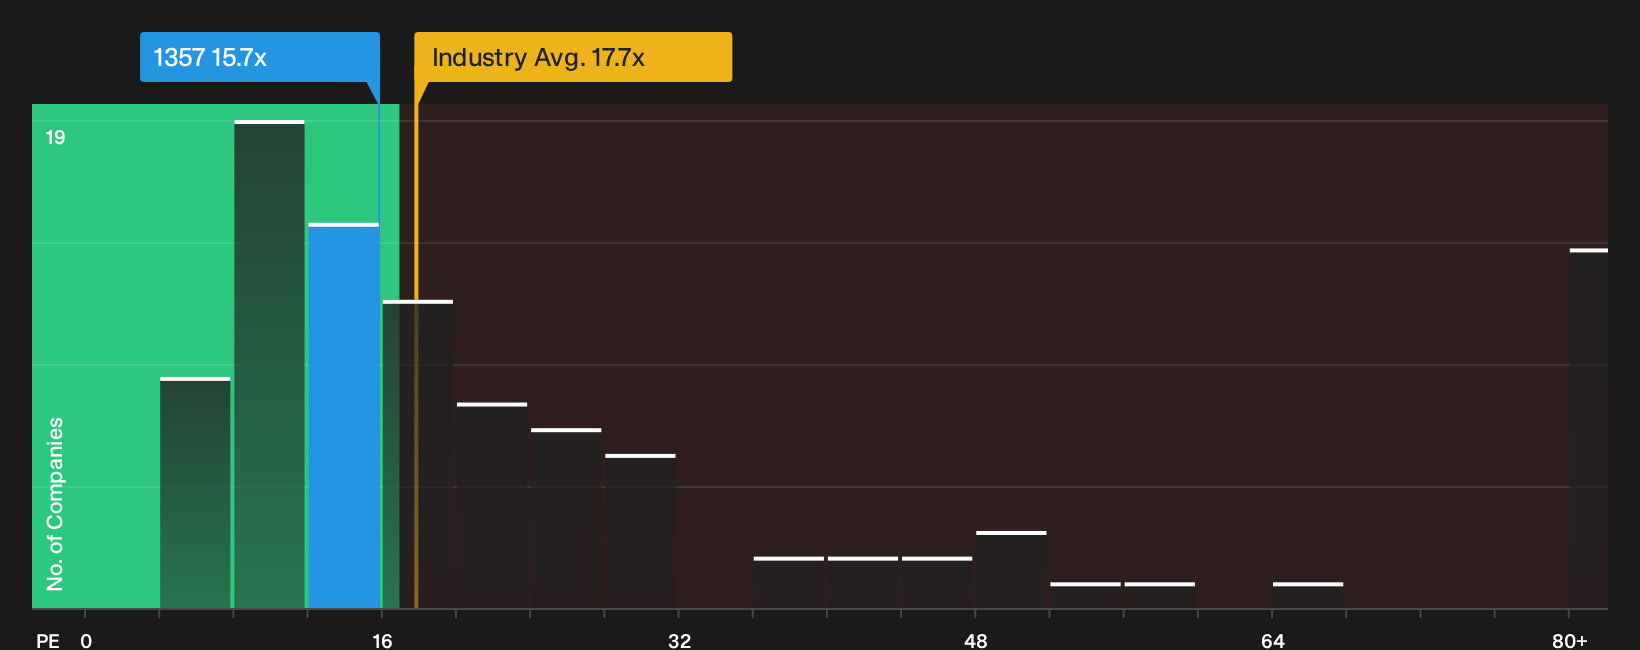
On simple earnings multiples, Meitu tells a different story to the bullish narrative. The shares trade on a P/E of 15.7x, which is cheaper than the wider Asian Interactive Media and Services group on 17.8x, but richer than both its peer average on 10.6x and its own fair ratio of 14.7x. That mix points to some optimism already embedded in the price, even as the broader peer set trades on lower expectations, so the question is how much room is left if sentiment cools?
For a closer look at how this earnings multiple stacks up against what the numbers imply as a fair ratio, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on Meitu's AI push and current share price are clear, so move quickly, review the full data set yourself, and weigh up the 2 key rewards and 1 important warning sign.
Looking for more Meitu sized investment ideas?
If Meitu has sharpened your focus on pricing, do not stop here. Use fresh stock shortlists to test your thesis and pressure check your next move.
- Target resilient value by reviewing companies that combine quality fundamentals with attractive pricing using the 192 high quality undervalued stocks.
- Prioritise staying power and sleep better at night by scanning a list of solid balance sheet and fundamentals (204 results) that can handle tougher conditions.
- Spot potential breakout stories early by working through 615 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com