


EN
Why Everyone Is Watching Marathon Petroleum (MPC) Right Now
Marathon Petroleum (MPC) drew fresh attention after Zacks assigned the stock a Rank #1 Strong Buy. The current year earnings estimate has been raised 36.3% over the past two months.
Recent trading has been choppy for Marathon Petroleum, with the share price down 4.4% over the past week after a strong 17.7% one-month share price return and a 47.9% three-month share price return. At the same time, the 1-year total shareholder return of 136.9% and 5-year total shareholder return of about 6.8x suggest powerful longer term momentum. This helps explain why any shift in earnings expectations quickly feeds into changing views on the risk and opportunity around the stock.
Scan other refiners and energy names that show similar earnings sentiment shifts and price momentum using our curated list of 27 high quality undervalued stocks.
After a 1 year return above 100% and a share price hovering near analyst targets, Marathon Petroleum now sits at a crossroads. Is the bulk of the upside already logged, or does valuation still leave meaningful room ahead?
Most Popular Narrative: 5.5% Overvalued
On Simply Wall St's most followed narrative, Marathon Petroleum screens as slightly above fair value, with a fair value estimate of about $433.44 against a last close of $457.22. That gap is shaped by how long current refining strength can hold.
The numbers suggest that a fairly valued, bearish view on Marathon Petroleum already reflects strong refining margins, substantial cash returns, and continued MPLX growth, which limits the potential upside for the share price if conditions simply remain where they are.
See why 69 investors see Marathon Petroleum as 5% overvalued.
Result: Fair Value of $433.44 (OVERVALUED)
Still, this narrative can unravel quickly if U.S. diesel export restrictions tighten or if wider crude supply squeezes Marathon Petroleum's crack spreads and refining earnings power.
Find out about the key risks to this Marathon Petroleum narrative.
Another View: SWS DCF Points To Undervaluation
The analyst narrative pegs Marathon Petroleum as about 5.5% above its $433.44 fair value, yet Simply Wall St's DCF model tells a different story. On that approach, the shares trade around $457.22 versus an estimated future cash flow value of $530.57, which screens as undervalued. Which lens do you trust more, earnings multiples or cash flows?
For a closer look at how those projected cash flows stack up against the current share price, and how sensitive that is to small shifts in assumptions, Look into how the SWS DCF model arrives at its fair value.
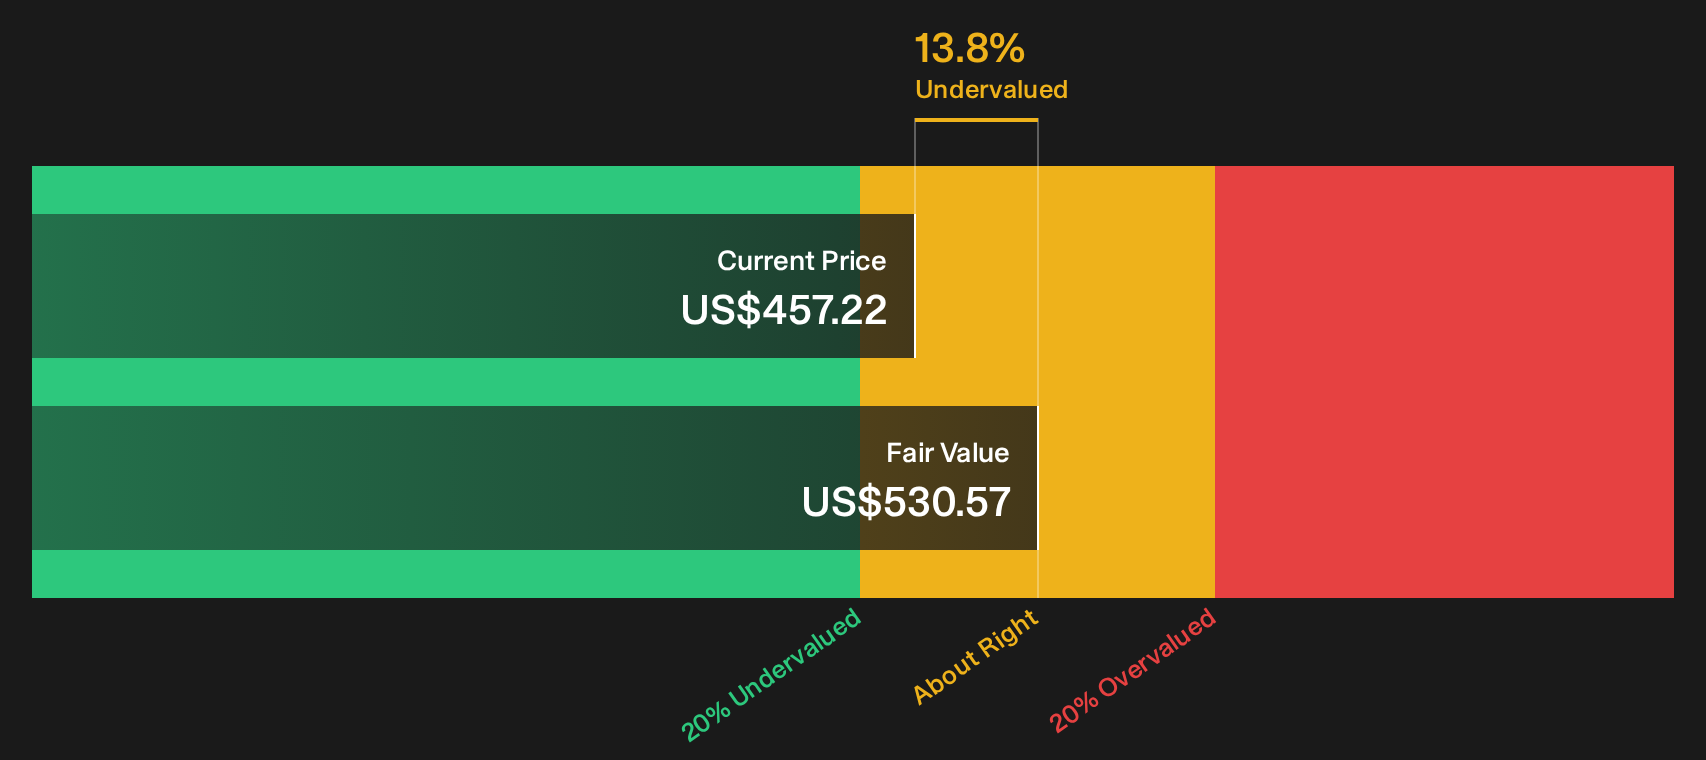
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marathon Petroleum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data so far? If you want a clear view on Marathon Petroleum, move quickly to weigh up the 2 key rewards and 3 important warning signs.
Looking for more Marathon Petroleum sized ideas?
If Marathon Petroleum has sharpened your focus, do not stop here. Use the Simply Wall St screener to uncover fresh opportunities before everyone else catches on.
- Target resilient compounding potential by scanning companies that score well on balance sheet strength through our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a sensible entry point by reviewing the 27 high quality undervalued stocks that currently screen well on fundamentals and pricing.
- Prioritise income today and sustainability tomorrow by checking companies featured in our 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com