


EN
i-80 Gold (TSX:IAU) Reorders Its Nevada Pipeline, Is The 51% Undervaluation Case Convincing?
i-80 Gold (TSX:IAU) just reshuffled its Nevada playbook, putting the Mineral Point open pit ahead in its project queue after outlining progress on its underground hub and Lone Tree processing plant.
Recent trading has been choppy. The share price has slipped over the past month, with a 30 day share price return of an 18.15% decline and a 7 day share price return of a 5.14% decline. However, i-80 Gold still shows a 90 day share price return of 6.28% and a 1 year total shareholder return of 48.18%, suggesting longer term holders have fared much better than short term traders.
Spot 35 elite gold producer stocks that, like i-80 Gold, are pushing ahead with large-scale Nevada and North American projects that could reshape their future production profiles.That kind of pullback can reflect real concern about i-80 Gold’s project risk, or just sentiment cooling after a strong year. The valuation work starts with separating those two stories.
Most Popular Narrative: 51% Undervalued
Against a last close of CA$2.03, the most followed narrative pegs i-80 Gold’s fair value at about CA$4.12, which frames the recent pullback as a valuation gap rather than a complete rethink of the Nevada build out.
The ramp-up of high-grade underground mining at Granite Creek, combined with unexpectedly higher oxide ore volumes and strong grades, positions the company for increasing gold production and improved revenue growth as resource modeling upgrades support future output targets.
Progress towards commissioning the refurbished Lone Tree autoclave by 2027 (potentially earlier), which will drive much higher gold recovery rates (from approximately 55–60% to approximately 92%) and lower operating costs per ounce compared to third-party toll milling, should significantly expand net margins and operational cash flow.
See why 14 investors see i-80 Gold as 51% undervalued.
Result: Fair Value of CA$4.12 (UNDERVALUED)
Still, the story for i-80 Gold can change quickly if big capex projects slip on timing or if further equity raises dilute existing shareholders.
Find out about the key risks to this i-80 Gold narrative.
Another View On i-80 Gold’s Valuation
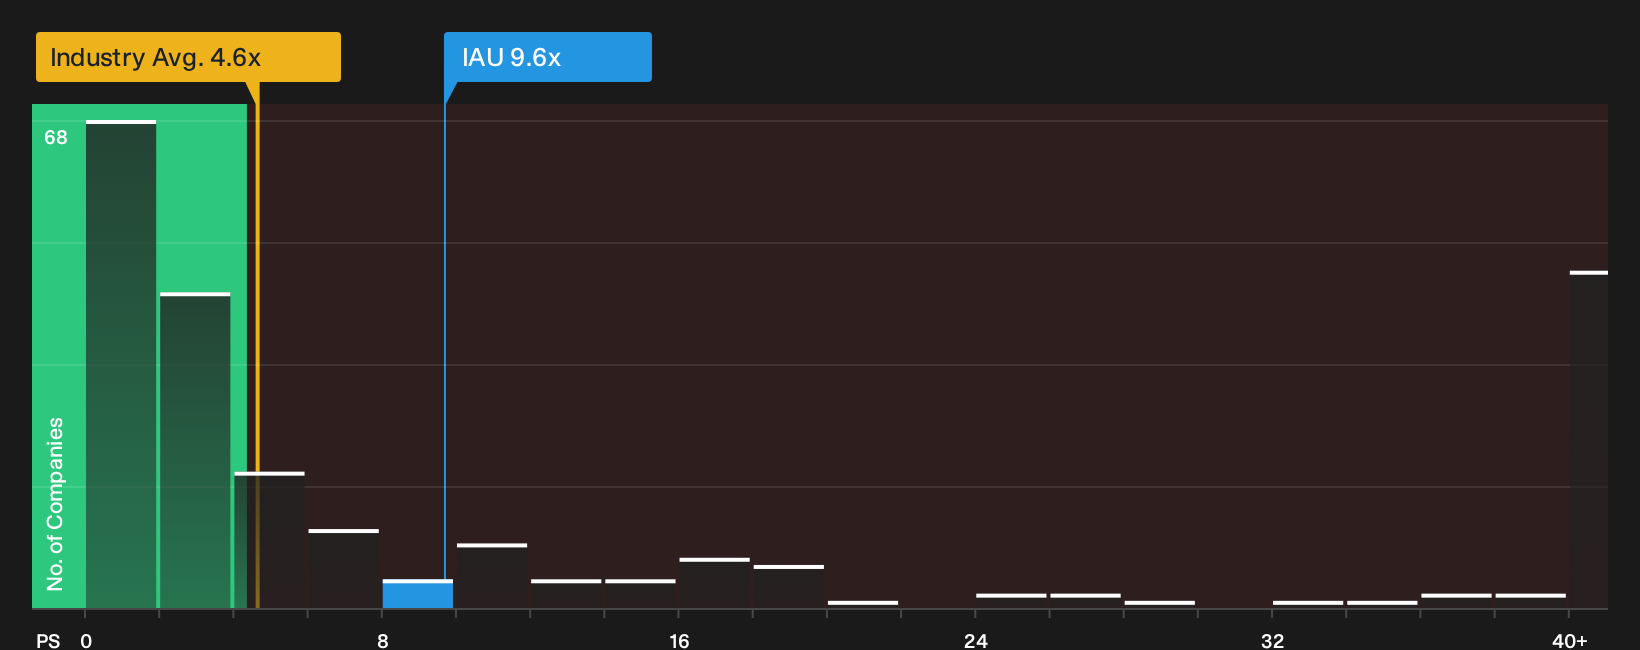
The analyst narrative suggests i-80 Gold has a fair value of CA$4.12, which implies the current CA$2.03 price is cheap. Yet the P/S ratio of 9.6x sits well above both the Canadian metals and mining group at 4.6x and the peer average at 5.4x, while the fair ratio sits closer to 4.4x. If the share price ever gravitates toward that fair ratio instead, how comfortable are you with the valuation risk that gap implies?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece leans cautious, yet the data around i-80 Gold clearly leaves room for both upside and risk in your own judgement. Move quickly, review the full picture, and weigh those potential upsides for yourself by reviewing the 1 key reward.
Looking for more investment ideas beyond i-80 Gold?
Do not stop your research with a single miner. Broaden your watchlist with other opportunities that match your risk appetite and return expectations using focused stock screens.
- Target overlooked potential by reviewing 9 high quality undiscovered gems that pair cleaner balance sheets with business models many investors still ignore.
- Lock in more predictable outcomes by focusing on 8 resilient stocks with low risk scores designed to highlight companies with steadier financial profiles and fewer red flags.
- Zero in on resilient fundamentals with a list of solid balance sheet and fundamentals (7 results) so you are not caught out holding fragile stories when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com