


EN
Equinor (OB:EQNR) Pushes Into Lithium, Is The Stock Fully Priced?
Equinor (OB:EQNR) just moved deeper into critical minerals as partner Standard Lithium filed a Preliminary Economic Assessment for the Franklin lithium project in East Texas, outlining large scale battery grade lithium carbonate production.
Equinor’s recent news flow around U.S. gas exposure, the Wisting oil project and now the Franklin lithium PEA has arrived alongside strong price gains, with a 1 month share price return of 11.72% and a year to date share price return of 87.83% suggesting momentum has been building. Over a longer stretch, total shareholder return of 94.12% over one year and 215.02% over five years points to a market that has increasingly priced in both energy transition projects and the existing oil and gas portfolio as these developments have unfolded.
Capture this move into lithium by scanning a hand picked set of energy transition players with 16 top copper producer stocks for ideas beyond Equinor’s current portfolio.Equinor looks like a stronger, more diversified energy business today, yet the recent rally and lithium excitement raise a blunt question. Is this a solid operation now pricing in too much good news, or not enough?
Most Popular Narrative: 20% Overvalued
Equinor last closed at NOK453.80, while the most followed narrative pegs fair value at NOK378.73 using a 6.79% discount rate. As a result, the lithium story is playing out against an already full valuation framework.
Expectations are high for Equinor's rapid expansion and value creation in renewables, especially offshore wind. Yet, recent impairments on U.S. wind projects highlight regulatory and margin headwinds, indicating that future earnings and net margins from renewables may not offset waning oil & gas cash flows as quickly as the market currently anticipates.
See why 98 investors see Equinor as 20% overvalued.
Result: Fair Value of NOK378.73 (OVERVALUED)
Still, a faster than expected ramp in major Norwegian projects, or stronger cash generation from long term gas contracts, could challenge the idea that Equinor is already fully priced.
Find out about the key risks to this Equinor narrative.
Another View: What Equinor’s P/E Is Saying
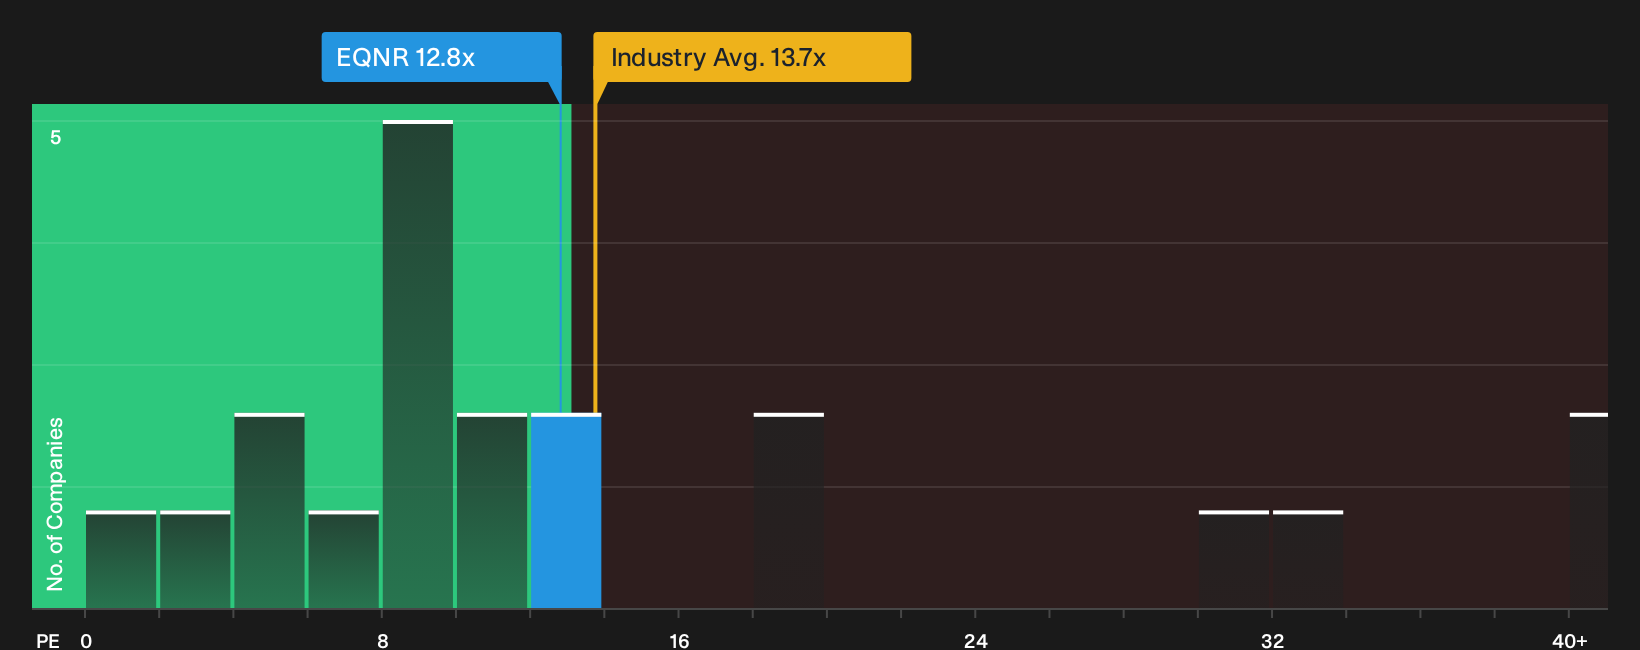
Equinor screens differently when the focus shifts from fair value models to the simple P/E ratio. The stock trades on 12.8x earnings, below the European oil and gas group on 13.7x and peers on 16.7x, yet above a fair ratio of 11x that the market could move toward.
This mix of discount to sector and premium to fair ratio points to less of a clear bargain and more of a valuation swing zone. It raises a practical question for investors: Is the current price compensating enough for forecast declines in revenue and earnings, or leaning too heavily on recent return strength?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on valuation and project risks do not need to leave you on the fence. Move quickly, review the data, and weigh both sides through 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Equinor?
If Equinor has sharpened your focus on quality and pricing power, do not stop here. Broaden your watchlist now and give yourself better choices.
- Target resilient value by scanning companies that combine solid cash generation with discounted valuations through the 192 high quality undervalued stocks.
- Lock in potential income streams by searching for businesses with higher yields and sturdier payouts using the 226 dividend fortresses.
- Protect the downside first by filtering for financially healthier opportunities with the list of solid balance sheet and fundamentals (204 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com