


EN
Did Earnings Guidance Raise Just Shift EastGroup Properties' (EGP) Investment Narrative?
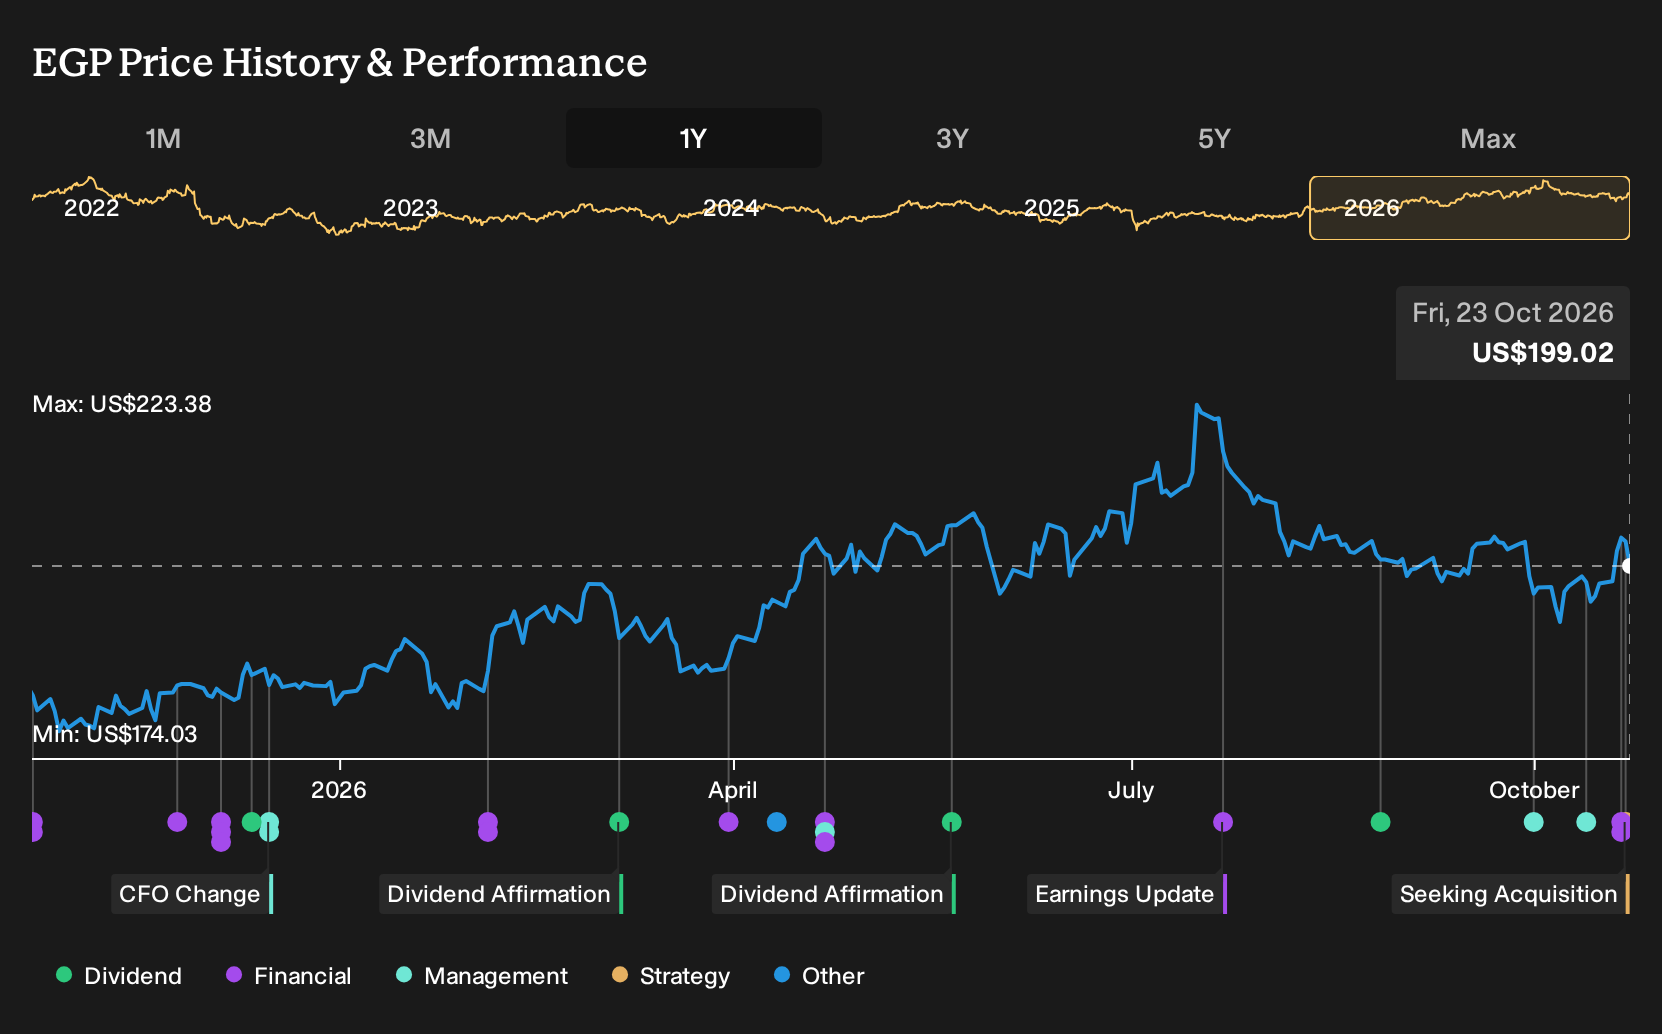
- EastGroup Properties reported third quarter 2026 revenue of US$199.4 million and net income of US$78.4 million, raised full year earnings guidance, and lifted full year acquisitions guidance to US$360 million, supported by US$485 million of forward equity raised to fund development and purchase activity.
- Management pointed to record leasing and a balance sheet with 14.6% debt to total market capitalization and 3.2x debt to EBITDA. This gives EastGroup Properties room to pursue more industrial projects while competitors face tighter financing and higher construction costs.
- We will look at how EastGroup Properties’ investment narrative is affected by stronger guidance alongside an expanded acquisition and development plan.
Scan other industrial REITs deploying capital aggressively while keeping leverage in check with our curated 30 resilient stocks with low risk scores poised for the next phase of project driven momentum.
EastGroup Properties Investment Narrative Recap
For an investor in EastGroup Properties, the core belief is that infill industrial demand, especially in Sunbelt markets, stays healthy enough to support leasing, development and acquisitions without stressing the balance sheet. The short term swing factor is execution on that broadened pipeline. Record leasing and raised earnings guidance support this, but do not remove the need for disciplined underwriting.
The biggest near term risk is that easing re leasing spreads and softer West Coast conditions meet a much larger project and purchase plan at the wrong time. The higher 2026 development and acquisitions targets amplify that exposure. Recent results and low leverage metrics help, yet they do not fully offset that timing risk.
The most relevant update here is the third quarter 2026 guidance raise. Management now expects full year net income attributable to common stockholders of US$322.8 million to US$326.0 million, or US$5.99 to US$6.05 per diluted share. That sits alongside quarterly revenue of US$199.4 million and net income of US$78.4 million, which together frame the current earnings base supporting the growth agenda.
Those figures matter because EastGroup Properties has lifted both development start guidance and acquisitions plans to US$360 million, funded in part by US$485 million of forward equity. Strong coverage ratios and a debt to EBITDA ratio of 3.2x provide capacity to pursue that program. The key potential catalyst is successful lease up at attractive spreads. The main risk is committing too much capital if tenant appetite cools faster than expected.
EastGroup Properties’ current analyst narrative points to forecast revenue of US$985.7 million and projected earnings of US$367.7 million by 2029, based on an assumed 9.5% yearly revenue growth rate and an earnings increase of about US$62.9 million from US$304.8 million today.
Uncover why EastGroup Properties' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community range from US$139.14 to US$227.90, which highlights how varied retail views on EastGroup Properties can be. You are weighing that uncertainty against a larger acquisition pipeline, fresh board oversight on the audit committee, and an active equity funding program that could reshape future returns.
Explore 2 other EastGroup Properties fair value estimates, including one that suggests potential upside of as much as 15% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your EastGroup Properties research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for EastGroup Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EastGroup Properties' overall financial health at a glance.
Looking for more EastGroup Properties sized ideas?
If the EastGroup Properties story has sharpened your thinking on risk, growth and balance sheets, use that same lens on a wider watchlist with the Simply Wall St Screener.
- For investors who want quality on sale, start by reviewing 27 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If steady income matters most to you, focus on reliable payers in our 5 dividend fortresses that pair higher yields with resilient profiles.
- When capital protection comes first, narrow your search to companies in the list of solid balance sheet and fundamentals (25 results) so you can concentrate on businesses with financial cushions already in place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com