


EN
Why Yue Yuen Industrial (Holdings) (SEHK:551) Is Back In Focus
Fresh revenue update puts Yue Yuen in focus
Yue Yuen Industrial (Holdings) (SEHK:551) has released unaudited figures for September, reporting net consolidated operating revenue of US$668.6m for the month and US$5.89b for the year to date.
The fresh revenue update lands as Yue Yuen’s share price trades at HK$14.36, with a 30 day share price return of 13.88% yet a year to date share price decline of 10.08%, while the 3 year total shareholder return above 100% signals momentum built over a longer horizon.
Scan how Yue Yuen Industrial (Holdings) stacks up against hand-picked peers facing similar consumer demand trends by checking the 192 high quality undervalued stocks in this corner of the market.
After a sharp 30 day rebound yet a year to date drop, Yue Yuen Industrial (Holdings) now trades above the average analyst target while still screening at a large intrinsic discount. Where does fair value really sit in that spread?
Price-to-earnings of 10.4x: Is it justified for Yue Yuen Industrial (Holdings)?
On the surface, Yue Yuen Industrial (Holdings) looks cheap against the SWS DCF fair value estimate, yet its P/E ratio of 10.4x screens as expensive relative to several benchmarks. That tension is what matters for you as a shareholder.
The P/E multiple compares the current share price with earnings per share, so you are effectively paying 10.4 times recent profits for this footwear manufacturer and retailer. For a business tied to global consumer demand and branded sportswear orders, that metric often reflects how confident the market is in the durability of its earnings profile.
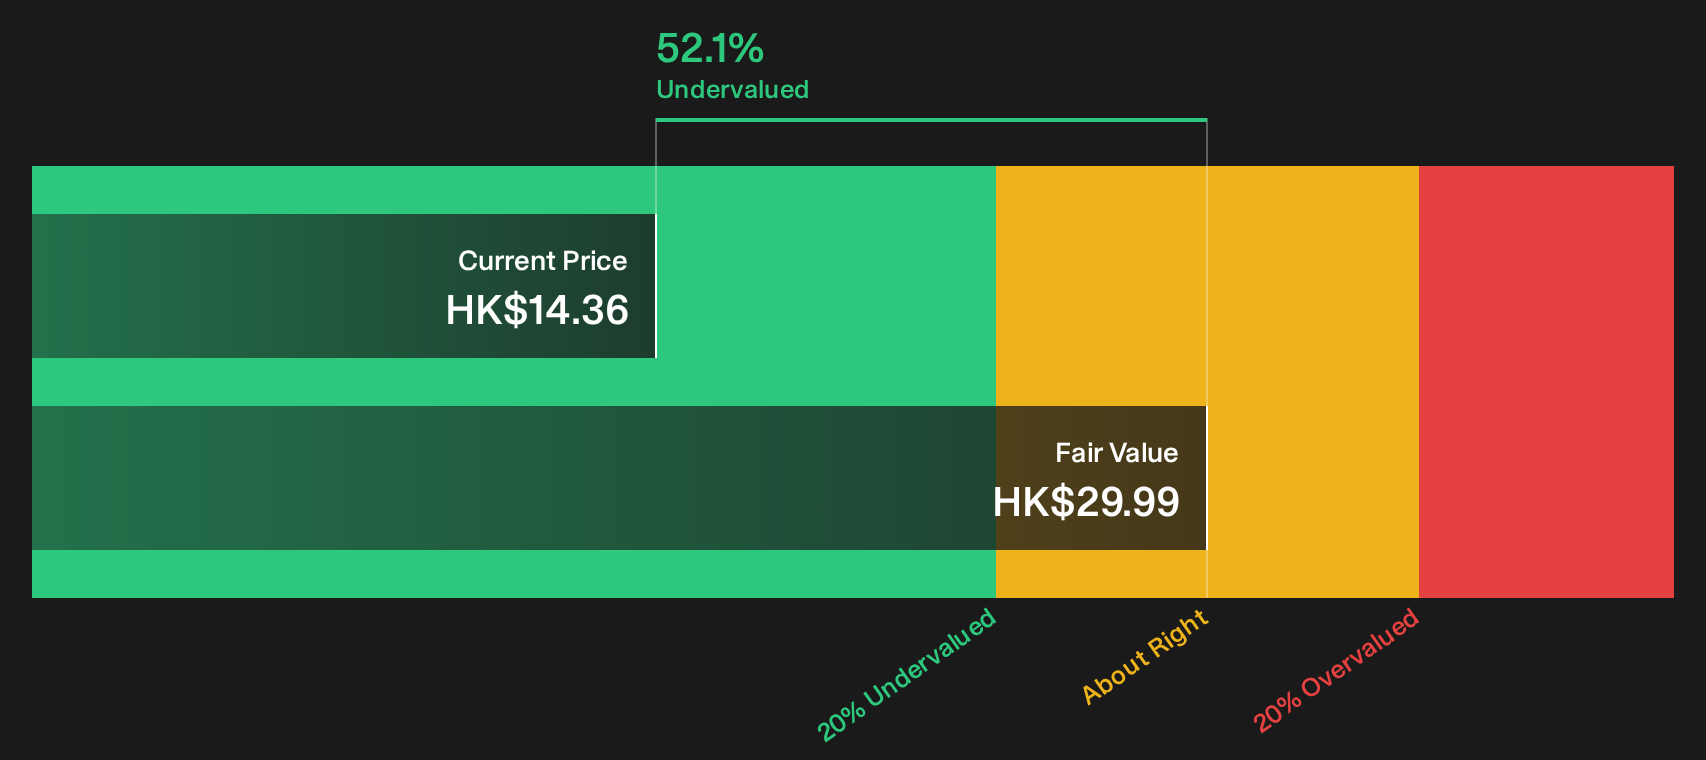
Here, the signals point in different directions. The SWS DCF model indicates Yue Yuen is trading at a 52.1% discount to an estimated future cash flow value of roughly HK$29.99, while the current price of HK$14.36 suggests the market is much more cautious. Earnings are forecast to grow 12.6% per year, compared with the wider Hong Kong market at 10.4%. Recent net profit growth has been weak, with a decline of 25.7% over the past year and net profit margins at 3.5% compared with 4.6% a year earlier.
Compared to peers, the stock carries a richer tag. Management is running on a P/E of 10.4x, above both the peer average of 9.8x and the Hong Kong Luxury industry at 7.6x, so investors are currently paying more per dollar of earnings than for similar stocks. Against the SWS fair P/E estimate of 9.2x, the current multiple also screens as elevated. This suggests the market could eventually lean toward a lower ratio if earnings delivery does not catch up with expectations.
Explore the SWS fair ratio for Yue Yuen Industrial (Holdings).
Result: Price-to-earnings of 10.4x (OVERVALUED)
Still, Yue Yuen’s reliance on major global sportswear brands and its relatively low net margin leave the story exposed if orders soften or costs rise again.
Find out about the key risks to this Yue Yuen Industrial (Holdings) narrative.
Another view on Yue Yuen’s valuation
Where the P/E ratio paints Yue Yuen Industrial (Holdings) as expensive against peers, the SWS DCF model points in the opposite direction. At HK$14.36, the shares sit about 52.1% below an estimated future cash flow value of HK$29.99, which presents a very different risk reward trade off.
For anyone considering that gap between earnings multiple and cash flow estimate, it helps to see exactly how the model compares with your own assumptions. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yue Yuen Industrial (Holdings) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Yue Yuen’s value case and risk profile can feel messy, so move fast, pull up the data, and weigh both sides of the story with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Yue Yuen?
If Yue Yuen Industrial (Holdings) has you thinking harder about value and risk, do not stop here. Broader opportunities are only a few smart filters away.
- Target stronger balance sheets by applying a list of solid balance sheet and fundamentals (204 results) that highlights businesses with sturdier financial foundations.
- Zero in on quality at a discount with a 615 high quality undiscovered gems that flags stocks the market may be overlooking.
- Stack your income options by reviewing a 226 dividend fortresses built around higher yield payouts with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com