


EN
How Investors May Respond To Union Pacific Stock After Earnings Beat
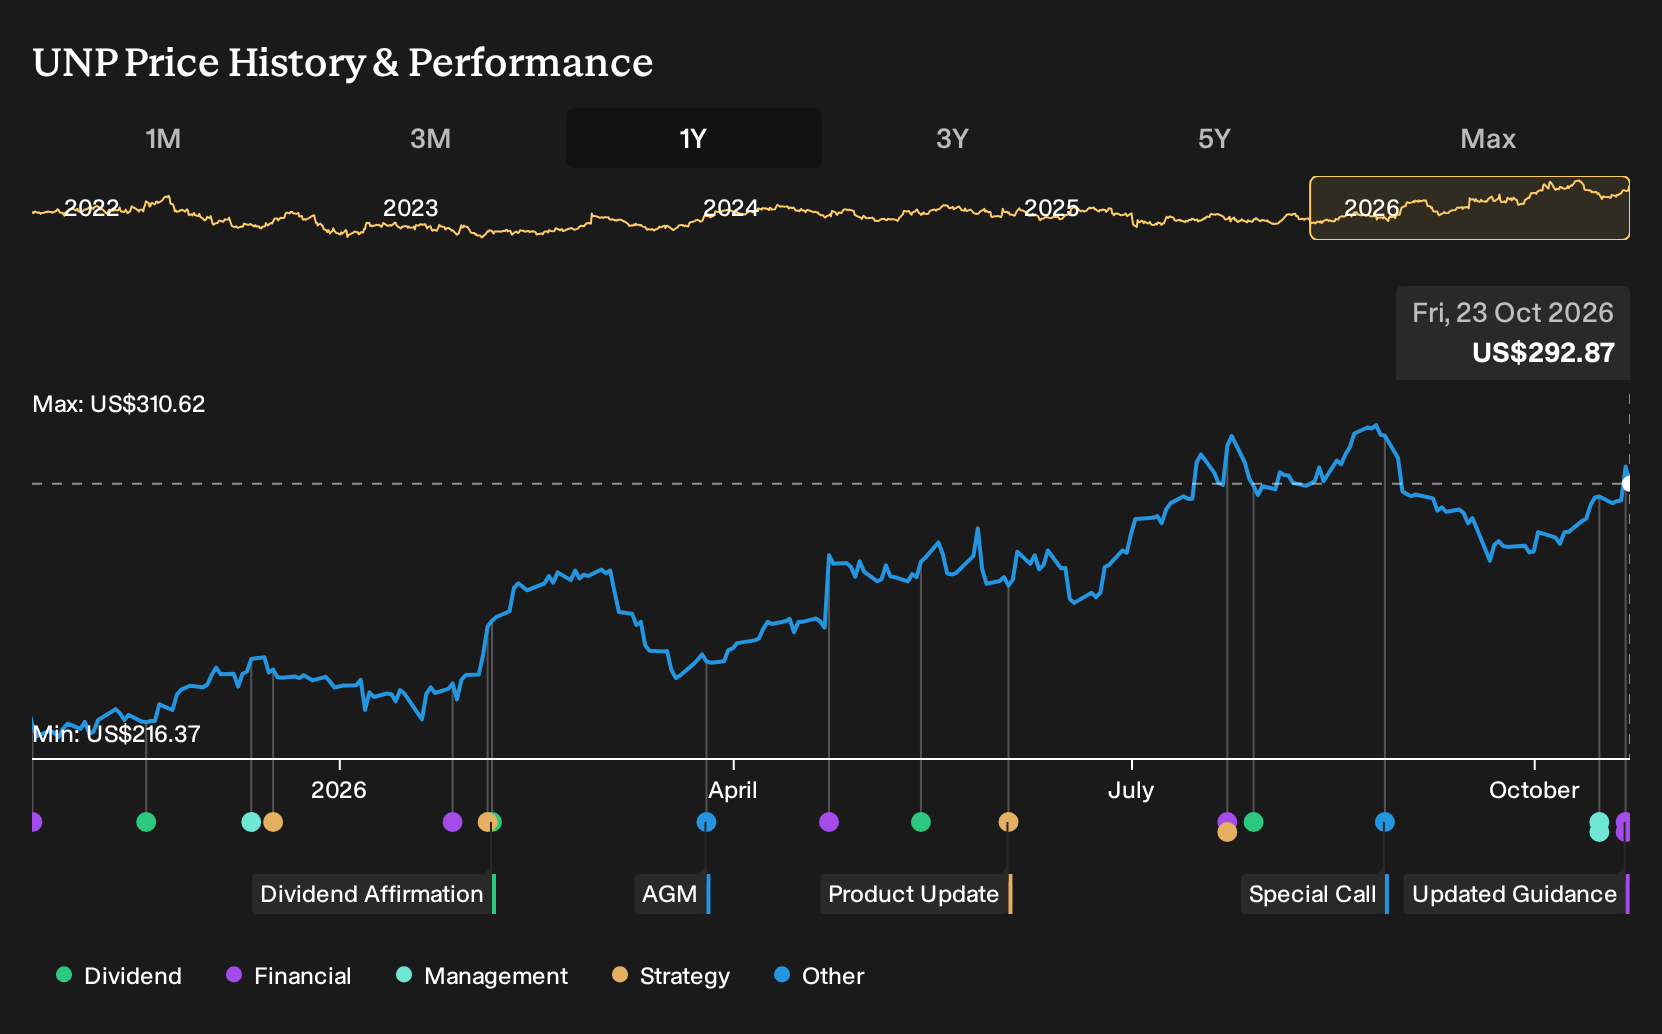
- Union Pacific reported third quarter 2026 results with revenue of US$7.2b and net income of US$2.1b, affirming high single digit EPS growth guidance for the full year.
- Stronger freight volumes, pricing gains and sizable fuel surcharge income are now combining with a US$3.5b capex plan and a large Norfolk Southern merger proposal to reshape Union Pacific's operating profile.
- This article reviews how Union Pacific's investment narrative could be influenced by this earnings beat and reaffirmed guidance.
Scan how Union Pacific's earnings beat and merger plans compare with other rail and infrastructure plays by reviewing the curated 42 power grid technology and infrastructure stocks that could benefit from similar freight and energy trends.
Union Pacific Investment Narrative Recap
To stay comfortable as a Union Pacific shareholder, you need to believe the railroad can keep turning solid freight demand into consistent earnings while absorbing higher fuel and labor costs. The Q3 beat and reaffirmed high single digit EPS growth guidance suggest the core network, including intermodal and bulk, is handling volume and pricing reasonably well in the near term.
The key short term catalyst is execution on higher volumes and pricing while deploying the US$3.5b capex plan without eroding returns. The biggest current risk is cost creep from diesel and wages outpacing efficiency gains. The latest results and outlook confirmation do not materially change that risk balance.
The most relevant recent announcement for this setup is the affirmation of high single digit reported EPS growth for 2026. That commitment, alongside record quarterly earnings and freight revenue strength across bulk, industrial and premium segments, keeps the focus on operational delivery rather than a reset of expectations. It indicates that management is comfortable with the current run rate.
For you, the question is whether Union Pacific can keep executing through the Norfolk Southern merger process and elevated fuel costs without losing discipline on margins or capital spending. The guidance, the US$3.5b capex update and the merger timeline together frame the near term scorecard, with regulatory outcomes and cost control as the main swing factors.
Union Pacific's narrative projects US$29.9b revenue and US$9.4b earnings by 2029. This assumes 5.5% yearly revenue growth and an earnings increase of about US$2.1b from US$7.3b today.
Uncover why Union Pacific's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$259 to US$330 per share, giving Union Pacific a wide retail investor range even before the recent guidance and merger updates. You are weighing those pre news views against rising diesel and wage pressures, as well as merger execution risk that could reshape future performance. Explore both angles.
Explore another Union Pacific fair value estimate, including one that suggests as much as 13% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Union Pacific research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Union Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Union Pacific's overall financial health at a glance.
Looking for more investment ideas beyond Union Pacific?
If Union Pacific has sharpened your thinking on freight, infrastructure and cash generation, use that same lens to size up other opportunities using the Simply Wall St Screener.
- For investors who want income with a buffer, scan for sturdy payers in our curated 5 dividend fortresses that pair higher yields with fundamental checks.
- If capital protection comes first for you, focus on stability by reviewing a 30 resilient stocks with low risk scores that filters for businesses with lower overall risk scores.
- When you want potential upside without ignoring balance sheet quality, search through a 21 high quality undiscovered gems that highlights under-followed companies with solid financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com