


EN
Castle Biosciences (CSTL) Shares New TissueCypher Data, Is The Stock 42% Below Fair Value?
New clinical data on Castle Biosciences (CSTL) TissueCypher test for Barrett's Esophagus, presented at the ACG 2026 meeting in Nashville, moves the story toward practical adoption and real-world physician behavior.
For investors watching Castle Biosciences, the recent TissueCypher data lands against a mixed trading backdrop, with the share price at US$33.08 and a 90 day share price return of 34.01% but a year to date share price return that is down 14.17%.
Spot 34 healthcare AI stocks that, like Castle Biosciences, are using advanced diagnostics and data-driven tools to reshape how clinicians assess risk and make treatment decisions.The share price has climbed 34.01% over 90 days, yet it remains below both recent highs and analyst targets. Where does fair value for Castle Biosciences really sit in that gap between price and estimated worth?
Most Popular Narrative: 41.7% Undervalued
At a last close of $33.08 versus a most-followed fair value estimate of $56.72 based on a 7.24% discount rate, the current Castle Biosciences share price sits well below the narrative view of intrinsic worth and places significant emphasis on whether its testing portfolio can scale profitably.
The launch of AdvanceAD-Tx into a large atopic dermatitis testing opportunity that management sizes at about US$33b in the U.S. creates a new revenue stream that can build on existing dermatology relationships and infrastructure, which can support long term top line growth.
See why 0 investors see Castle Biosciences as 42% undervalued.
Result: Fair Value of $56.72 (UNDERVALUED)
Still, that 41.7% gap to fair value depends on big assumptions holding up, and slower reimbursement progress or sustained losses could quickly weaken the positive Castle Biosciences narrative.
Find out about the key risks to this Castle Biosciences narrative.
Another View: What Multiples Say About Castle Biosciences
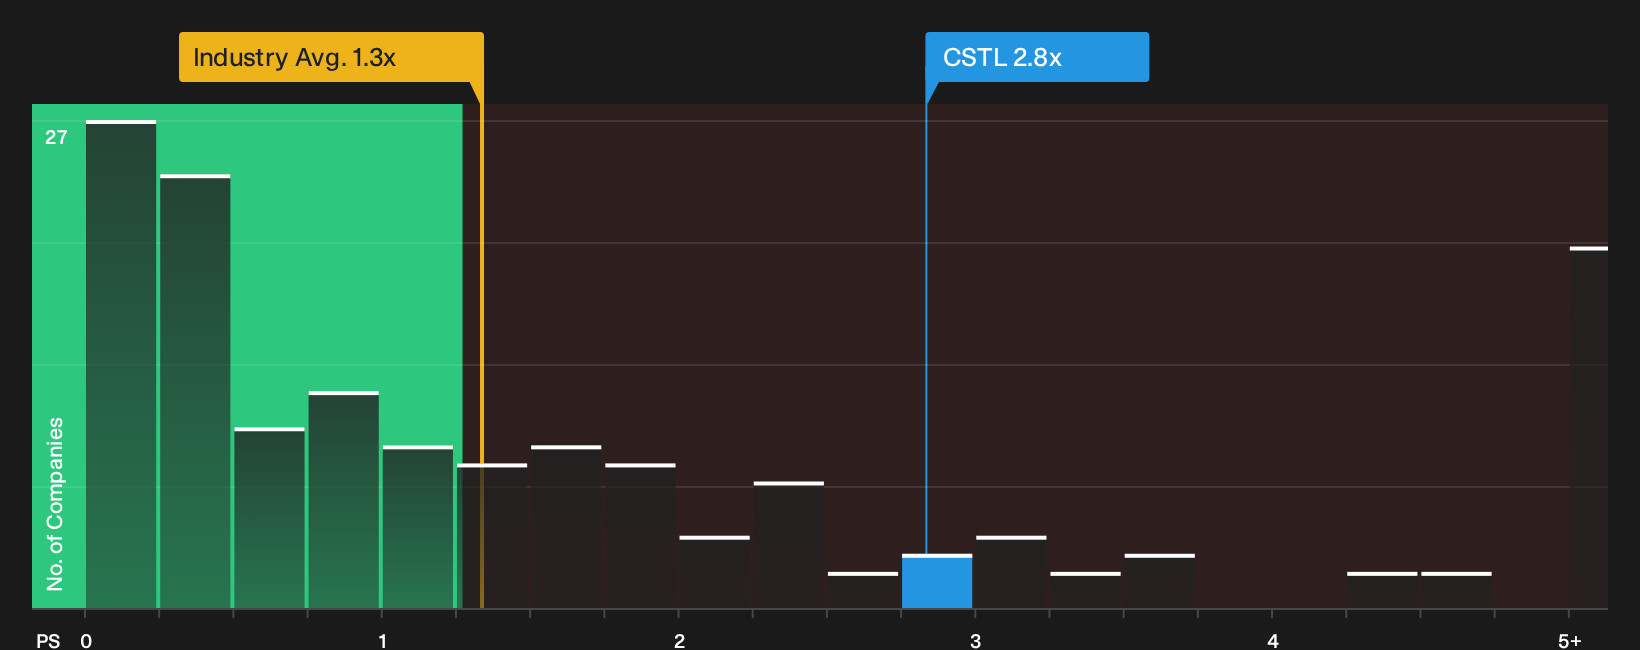
The story looks different once price is tied back to sales. Castle Biosciences trades on a P/S ratio of 2.8x, which is higher than both its peer group at 1x and the broader US Healthcare sector at 1.4x, even though the fair ratio is estimated at 3.1x.
That mix of being expensive versus peers but still below the fair ratio points to a tighter margin of safety, and puts more weight on how comfortable you are paying up for growth that is forecast at 9.4% a year with earnings expected to improve. Is that premium worth it for you at this stage of the story, or does it nudge you to compare alternatives first with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Castle Biosciences can easily pull you in opposite directions. Move quickly from headline impressions to the underlying numbers and weigh both sides of the story using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Castle Biosciences?
If Castle Biosciences has sharpened your focus on quality setups, do not stop here. Broaden your watchlist now to help you identify additional opportunities.
- Target potential mispricings by scanning 27 high quality undervalued stocks that combine solid fundamentals with prices that lag behind underlying business quality.
- Stabilize your income stream by reviewing 5 dividend fortresses that pair higher yields with balance sheets built to handle tougher conditions.
- Reduce portfolio stress by filtering for 30 resilient stocks with low risk scores that show lower risk scores while still offering room for sensible upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com