


EN
How Investors May Respond To Aeon (TSE:8267) Half Year Earnings And Dividend Reset
- Aeon Co., Ltd. reported half year results to August 31, 2026 with JPY 5,428,125 million in sales, JPY 5,904,157 million in revenue and JPY 13,321 million in net income, alongside earnings per share of JPY 4.81 from continuing operations.
- The retailer paired these figures with a recalibrated dividend framework that distinguishes ordinary and commemorative payouts after its recent 3 for 1 stock split. This gives investors a clearer line of sight on how cash returns align with the current share structure.
- Market participants can now assess how Aeon's half year earnings and recalibrated ordinary dividend fit into the existing investment narrative around profitability and returns.
Aeon Investment Narrative Recap
To own Aeon, you need to be comfortable with a low margin retailer that is leaning on private brands, joint procurement and data projects to do more with a huge revenue base. The latest half year numbers show the business continuing to generate scale, although the modest net income and earnings per share underline how sensitive the story is to small changes in operating efficiency.
The key near term swing factor remains whether those digital and productivity efforts translate into cleaner cost lines and better group margins. Execution risk sits in the background, especially with debt only partly covered by operating cash flow. This earnings release does not fundamentally change that overall risk and reward equation.
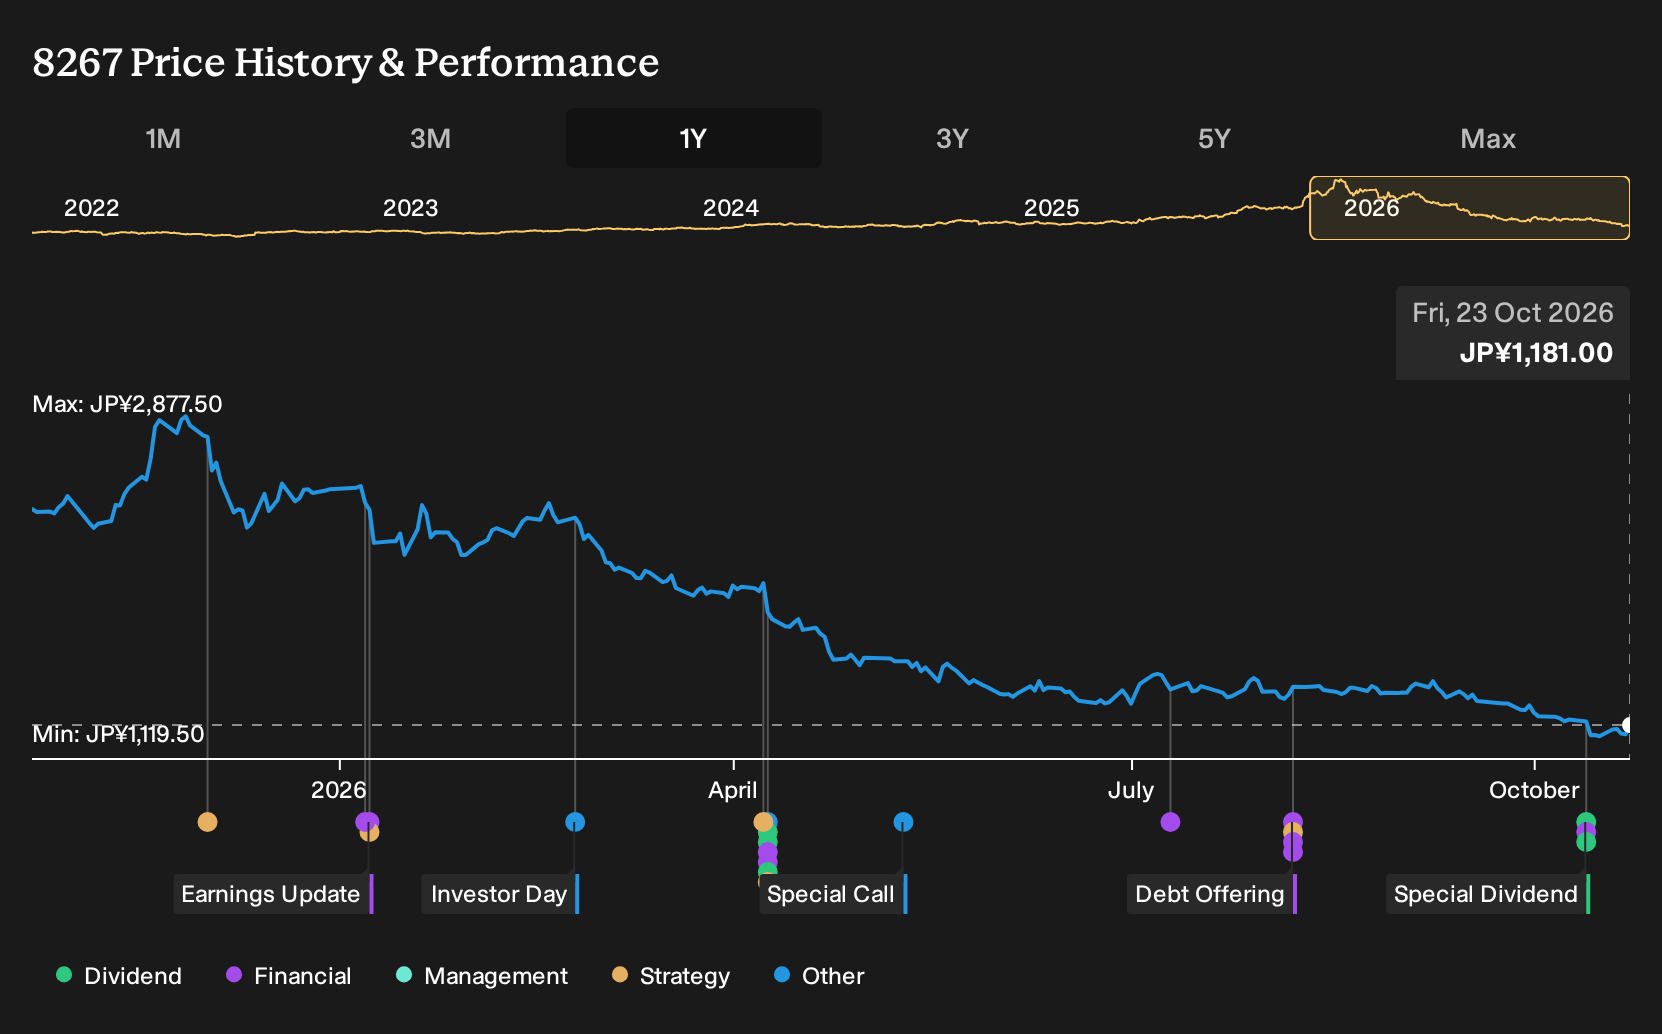
The most relevant update for you as a shareholder watching near term catalysts is the dividend reset. Aeon declared a second quarter ordinary dividend of ¥7.00 per share, down from ¥20.00 a year earlier on a pre split basis, and added a commemorative ¥0.50 per share payout. Both are payable from October 28, 2026.
This framework matters because it separates recurring cash returns from one off commemorative elements, which helps you judge how future profit delivery might flow into income. With earnings still thin relative to the scale of the group, that clarity around ordinary dividends, together with the link to the recent 3 for 1 split, provides a clearer view on sustainability and payout risk.
Aeon's narrative projects ¥12,606.4b revenue and ¥125.9b earnings by 2029. That profile reflects analyst assumptions of 3.3% yearly revenue growth and an earnings increase of about ¥43.9b from ¥82.0b today.
Uncover how Aeon's fair value indicates a 17% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Some of the most optimistic Aeon analysts were already leaning hard into Vietnam expansion as a swing factor, pencilling in revenue of ¥12,996.0b and earnings of ¥166.0b by 2029 with a P/E of 44.0x. You can now weigh these upbeat expectations against the fresh earnings and dividend reset and explore how those views might shift.
Explore 3 other Aeon fair value estimates, including one that suggests there could be as much as 85% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aeon research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aeon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aeon's overall financial health at a glance.
Looking for more Aeon sized income ideas?
If Aeon has prompted you to rethink how dividends, balance sheets and valuation all fit together, it can help to line it up against a wider set of companies using the Simply Wall St Screener.
- For investors who want yield without ignoring quality, compare Aeon's payout profile against a curated 29 dividend fortresses that lean on consistent income and balance sheet strength.
- If capital preservation sits high on your checklist, stress test Aeon beside a 22 resilient stocks with low risk scores that score well on volatility and financial risk metrics.
- When you want to broaden the watchlist beyond well covered stocks, set Aeon alongside a 72 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com