


EN
Is Alstom (ENXTPA:ALO) Undervalued After Its New Hanoi And Greater Anglia Contracts?
Alstom (ENXTPA:ALO) is back in focus after two sizeable rail contracts: an approximately €800 million Metropolis train order for Hanoi and a 15 year services extension with Greater Anglia in the UK.
The fresh contract flow appears to be arriving as Alstom stock tries to rebuild momentum, with an 8.53% 1 month share price return and a small 0.53% gain over 3 months. This is set against a year to date share price decline of 37.35% and a 1 year total shareholder return that is down 26.67%, while the 3 year total shareholder return of 41.39% points to a much stronger longer run picture than the 5 year total shareholder return, which is down 43.45%.
Compare Alstom’s latest contract wins with other rail and infrastructure players by scanning our hand picked 42 power grid technology and infrastructure stocks that are also tied into long term transport and grid projects.
Fresh contracts, a recovering share price and a still weak long term chart put Alstom at an awkward crossroads. Does the current valuation still skew the risk reward towards buyers after this latest bounce?
Most Popular Narrative: 22% Undervalued
Alstom’s most followed valuation narrative places fair value at €20.7 per share, which is well above the recent €16.10 close. That gap reflects a view that the rail specialist carries real execution risk, but also that its order book and earnings profile could justify a higher price if things go to plan.
The main thing that has to go right is fixing execution issues in rolling stock industrialization and project delivery so that margins and free cash flow more consistently reflect the higher quality order book.
The current valuation implies the market is treating Alstom’s record €104b backlog, improved embedded gross margin and reduced net financial debt of about €400m as carrying meaningful execution and cash flow risk, while some investors may view this as indicating that the shares are undervalued.
See why 29 investors see Alstom as 22% undervalued.
Result: Fair Value of €20.7 (UNDERVALUED)
Still, the Alstom story rests on fixing rolling stock execution and avoiding a deeper than planned €600m to €700m free cash flow shortfall.
Find out about the key risks to this Alstom narrative.
Another View: What Multiples Say About Alstom
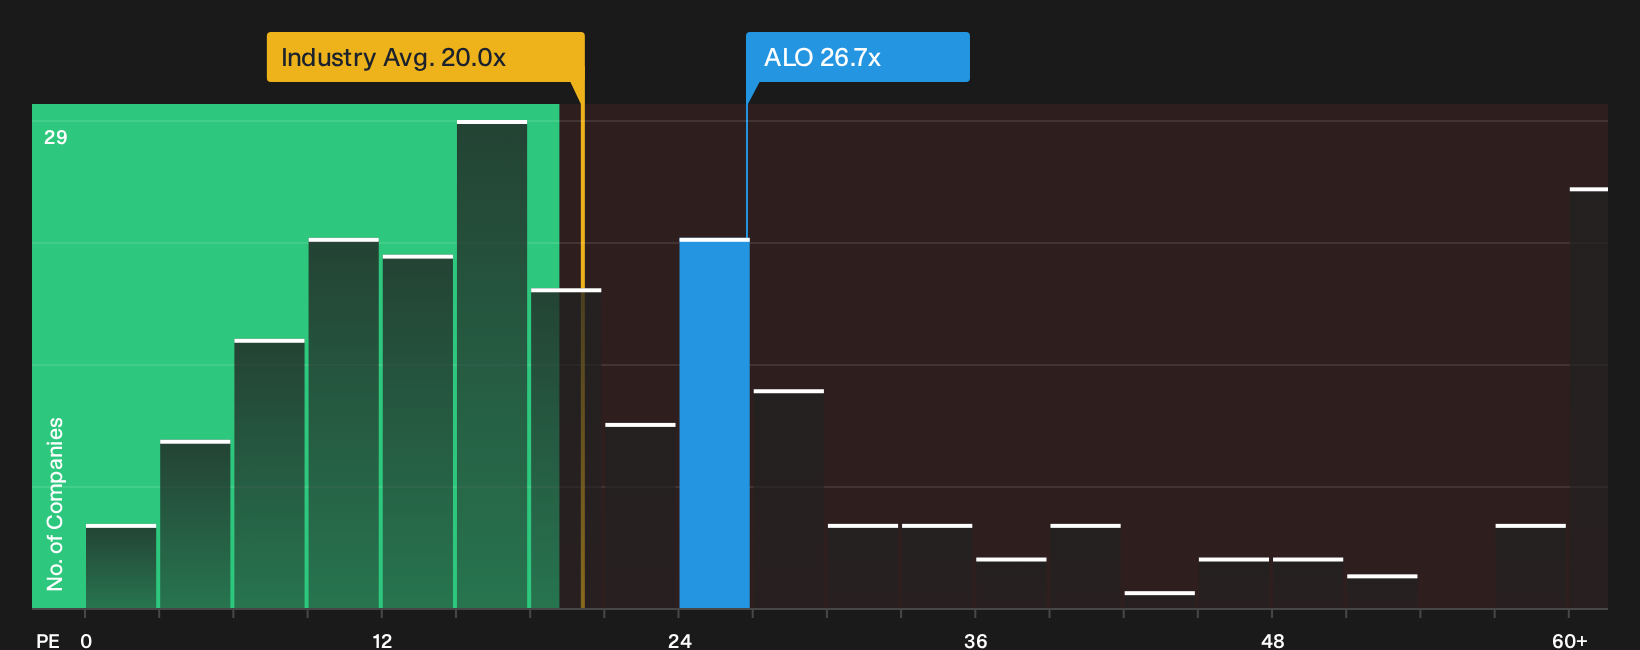
Alstom looks cheap against the €20.7 fair value narrative, yet its P/E of 26.7x is high next to European machinery peers on 20x and its own fair ratio of 31.7x. The stock screens as expensive versus the sector but not versus that fair ratio, which raises a simple question for investors: Which reference point really matters to you.
To see how this valuation gap lines up with earnings quality, sector peers and that fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether this mixed picture on Alstom leans more toward worry or optimism? Act while the data is fresh and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alstom?
Do not stop your research at Alstom. Fresh opportunities often show up where pricing, balance sheets and dividends line up more cleanly for new capital.
- Target potential mispricing by scanning companies on our 192 high quality undervalued stocks that pair solid fundamentals with valuations some investors may be overlooking.
- Strengthen portfolio resilience by focusing on businesses screened for financial sturdiness through the list of solid balance sheet and fundamentals (204 results) before the crowd catches on.
- Boost your income playbook by reviewing companies in the 226 dividend fortresses that combine higher yields with disciplined payout histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com