


EN
Are Earnings Upgrades Altering The Investment Case For Crescent Energy Stock (CRGY)?
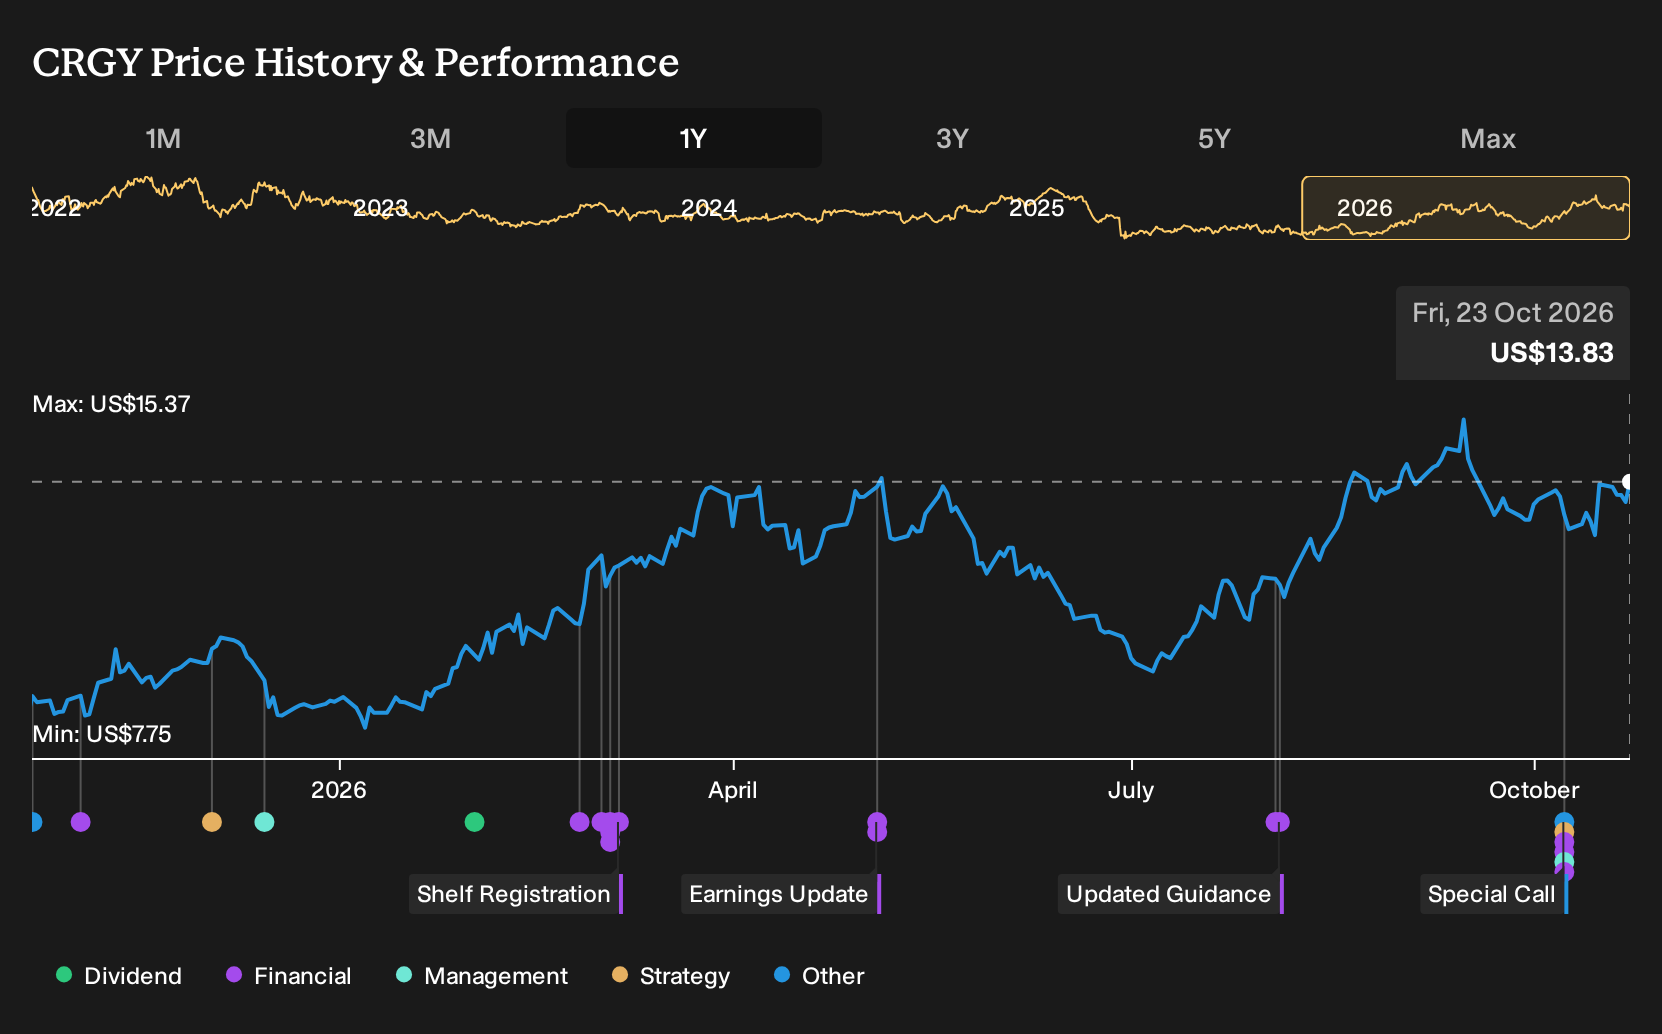
- Crescent Energy has recently attracted stronger analyst confidence, with the consensus EPS estimate for the current year revised higher by 36.2% over the past three months, and the stock delivering a 60.9% year to date return within the Oils Energy sector.
- The combination of a top ranked analyst rating and sharply higher earnings expectations highlights how Crescent Energy's operational and acquisition choices are feeding into a materially improved profit outlook compared with sector peers.
- We will now assess how Crescent Energy's sharply higher earnings outlook could reshape its investment narrative for long term holders.
Scan how Crescent Energy's sharp earnings upgrades compare with other potential outperformers by reviewing the hand picked 27 high quality undervalued stocks now shaping analyst expectations.
Crescent Energy Investment Narrative Recap
To own Crescent Energy, you need to be comfortable with an operator that leans hard on acquisitions, cost efficiency and a minerals and royalties platform to drive earnings. The big near term swing factor is how smoothly the Devon Eagle Ford assets fold into the portfolio, because synergy delivery and well performance tie directly into free cash flow and debt reduction.
The biggest risk is that these acquired barrels or planned efficiencies underdeliver, especially with Crescent Energy trading on a high P/E multiple relative to peers. That combination leaves less room for operational hiccups, but the latest earning upgrades do not radically change the core execution challenge.
Recent commentary around the approximately US$3.85b Devon Eagle Ford transaction is the clearest operational anchor for today’s stronger outlook on Crescent Energy. The deal brings about 68,000 Boe/d of extra output plus more than 600 Tier 1 locations, which gives management more inventory depth to work with across cycles.
Execution on those acquired pads and the roughly US$140 million of identified annual synergies now sits at the center of the near term story. Delivery here matters for keeping leverage on the glidepath management has outlined, supporting the growing minerals and royalties contribution, and helping justify both the recent share price performance and the richer earnings multiple.
Crescent Energy Forecasts And Implied Earnings Step Up
Crescent Energy's current profit base is small relative to what analysts are pencilling in over the next few years, which makes the forecast jump in earnings do a lot of heavy lifting in the story. Expectations on revenue, margins and valuation all tie back to these projected numbers, so it is worth laying out the assumptions clearly before deciding how comfortable you are with them.
Analysts are working off earnings today of about US$54.8 million and assume revenue expands at roughly 12.3% a year over the next three years. Their models point to Crescent Energy producing about US$1.5b of earnings by 2029, with profit margins moving from 1.3% to 24.4% over that window if everything goes to plan. That implies earnings rising by roughly US$1.45b in value, which is a very large increase from the starting point.
Putting those profit expectations against the current share price, the analyst group is anchoring on a 2029 scenario where Crescent Energy generates around US$6.1b of revenue and about US$1.5b of earnings. On those numbers the stock would be trading at a P/E of 6.2x, compared with a reported multiple today of 97.9x and a cited US Oil and Gas industry level of 12.3x. The jump in earnings is doing most of the work in bringing the P/E down in those scenarios, not a low implied valuation on today's profitability.
Crescent Energy's narrative projects about US$6.1b of revenue and roughly US$1.5b of earnings by 2029. This assumes roughly 12.3% yearly revenue growth and an earnings increase of about US$1.45b from roughly US$54.8 million today.
On top of the growth assumptions, the analyst framework bakes in several moving parts that matter for longer term shareholders. Profit margins are projected to expand as the Devon Eagle Ford assets are integrated, synergies of roughly US$140 million a year are delivered, and the minerals and royalties platform adds more high margin income. The models also assume the share count grows around 7% annually for three years, which spreads those projected earnings over a larger base and makes execution on both margins and volumes more important for per share outcomes.
Valuation work in the consensus report then layers these operational inputs into a discounted cash flow style view. Using a discount rate of about 7.9% to 7.91% and the 2029 revenue and earnings markers, analysts arrive at a consensus price target of US$18.06 for Crescent Energy, compared with a current share price quoted at US$13.06. Individual views vary, with targets ranging from US$12 at the low end to US$22 at the high end, which signals different levels of conviction on acquisition quality, integration timing and how achievable those margin gains look.
Uncover how Crescent Energy's fair value indicates a 31% potential upside to its current price, which could narrow quickly if Crescent Energy keeps executing on its plan.
Exploring Other Perspectives
One alternate view focuses less on Crescent Energy’s acquisition synergies and more on hedge cash drag. The most cautious analysts were working off roughly US$5.3b of 2029 revenue and US$1.3b of earnings, yet still saw only a modest upside. That is a far more skeptical story than today’s strong EPS revisions suggest. Treat this news as a reason to compare both playbooks and decide which assumptions you find more realistic.
Explore 4 other Crescent Energy fair value estimates, including one that suggests it could be worth just $18.06!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Crescent Energy research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crescent Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crescent Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Crescent Energy?
Once you have formed a view on Crescent Energy, it can help to widen the lens and compare it with other businesses that match your risk tolerance, income needs, or balance sheet preferences using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, scan for resilient payers through 5 dividend fortresses that have the potential to support a steadier stream of cash returns.
- When capital preservation matters most, narrow your search to companies with sturdier finances by using the 30 resilient stocks with low risk scores and focus on businesses where balance sheet strength and risk scores are front and center.
- For investors hunting for quality that has not attracted much attention yet, cast a wider net with the 21 high quality undiscovered gems and spot candidates that pair solid fundamentals with lighter coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com