


EN
Reliance (RS) Looks Fully Valued After Earnings And Dividend Update
Why Reliance just moved back into focus
Reliance (RS) is back on investor radars after third quarter earnings and a fresh dividend declaration, which combined strong reported sales and profit figures with a clear signal on capital returns.
Over the past year Reliance has shifted from a quiet compounder to a clear momentum story, with a 40.5% year to date share price return and a 52.23% total shareholder return, which frames the latest earnings jump and dividend decision as part of a longer upswing in investor confidence.
Capitalize on Reliance’s earnings and dividend momentum by scanning a curated set of metal and materials leaders with resilient balance sheets and cash generation using list of solid balance sheet and fundamentals (25 results).After a surge like Reliance has just delivered, the question is simple. Are you looking at a stock that has already cashed in most of the upside, or one still mispriced on the latest numbers?
Most Popular Narrative: 1% Undervalued
Reliance closed at $415.62 against a widely followed fair value estimate of $418.67, which puts the current momentum in context as almost fully reflected in the price but not quite capped.
Heightened data center construction, public infrastructure work and power grid projects are currently supporting strong non residential construction demand that represents roughly one third of Reliance sales. This can continue to feed volumes and support revenue and operating leverage.
See why 7 investors see Reliance as 1% undervalued.
The narrative uses an 8.95% discount rate and ties that fair value of $418.67 to revenue assumptions of $17.5b and earnings of $1.1b by 2029, with a P/E of 23.3x on those earnings. With the share price only about 1% below that mark, the story hinges less on a big valuation gap and more on whether those end market drivers in infrastructure, data centers and government contracts keep justifying a premium multiple over the broader US Metals and Mining sector.
Result: Fair Value of $418.67 (ABOUT RIGHT)
Still, tariff swings and higher LIFO expenses sit in the background as real threats to Reliance margins if input costs continue to move against the current assumptions.
Find out about the key risks to this Reliance narrative.
Another Look At Reliance’s Valuation
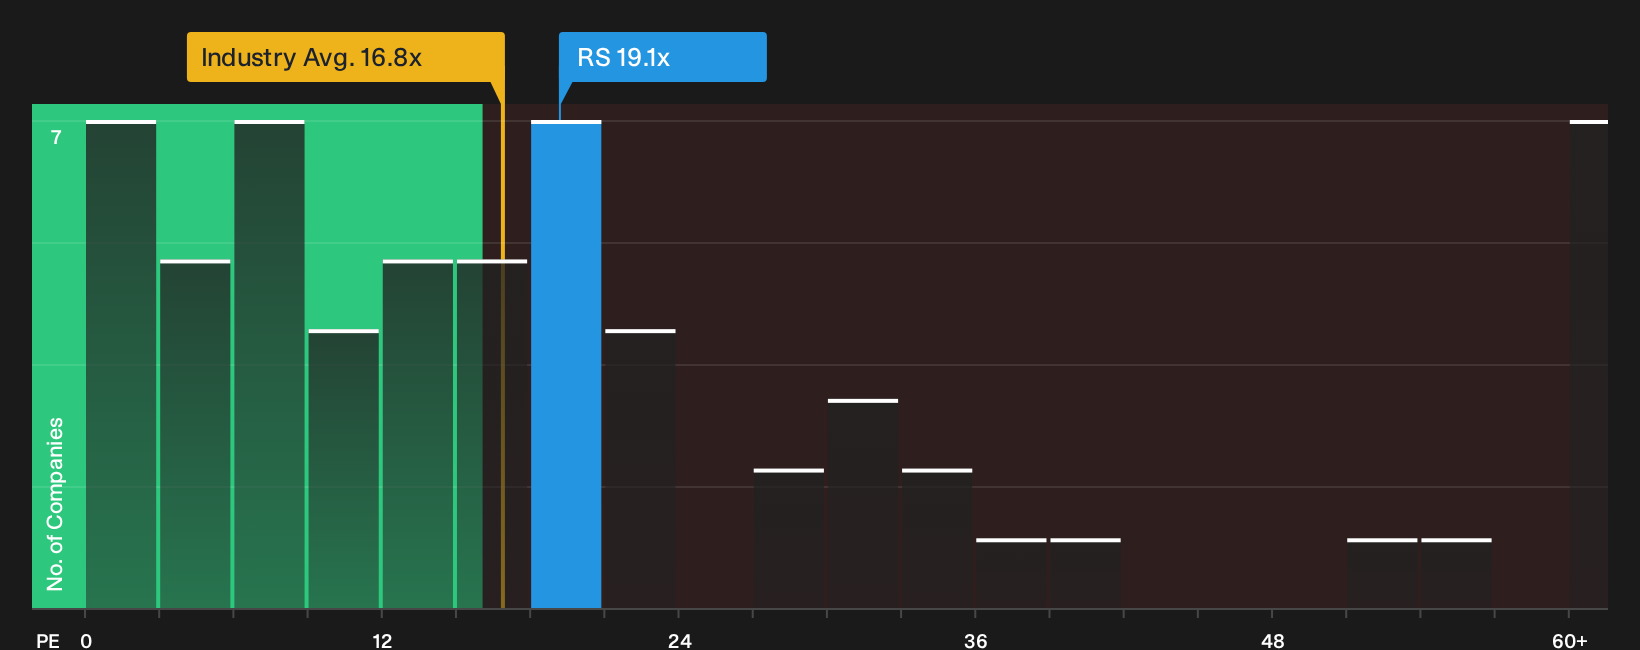
On the first cut, Reliance looked roughly in line with fair value. Using a simple P/E lens tells a different story. The stock trades at 19.1x earnings, compared with 16.8x for the US Metals and Mining industry, 16.1x for peers, and a fair ratio of 15.3x. That gap points to meaningful valuation risk if sentiment cools.
For investors who want to see how this price stacks up against underlying earnings power, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Impressed by how the Reliance story stacks up so far, or still unsure about the risk reward trade off? Put the data in context for yourself by reviewing the 2 important warning signs.
Looking for more investment ideas beyond Reliance?
If Reliance has sharpened your focus, do not stop there. Use curated screeners to spot other opportunities that fit your risk level and income goals.
- Target durable quality by reviewing a 30 resilient stocks with low risk scores that filters for resilience when conditions turn rough.
- Hunt for mispriced strength through a 27 high quality undervalued stocks built to surface companies with strong fundamentals at restrained valuations.
- Aim for income plus staying power by scanning a 5 dividend fortresses that pairs higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com