


EN
Fortive (FTV) Puts Data Center Reliability In Focus On A Valuation Gap
Fortive (FTV) is back on investors radar after subsidiary Fluke Networks rolled out new FI-3000 FiberInspector Pro tips that let technicians inspect crowded data center fiber connections without disconnecting live links.
Against that backdrop, Fortive’s recent Fluke Networks update lands while the shares trade at US$60.25. The 30 day share price return is 7.09% and the year to date share price return is 8.77%. However, the 90 day share price return declined 3.31% and the 1 year total shareholder return is 22.33%, suggesting momentum has picked up again after a softer patch.
Scan beyond Fortive and this Fluke Networks update by reviewing other infrastructure focused plays in the 55 AI infrastructure stocks that tap into data center and AI build outs.
The recent move to US$60.25 leaves Fortive only a few dollars below analyst targets, yet still at a wider discount to some intrinsic value estimates. Which reference point really anchors fair value as you weigh the next leg?
Most Popular Narrative: 5.9% Undervalued
Fortive’s most followed valuation narrative points to a fair value of $64.00 compared with the latest close at $60.25, so the story hinges on whether recurring revenue, AI tools and healthcare exposure can justify that gap.
Fortive's increasing mix of recurring revenues, now at roughly 50% of company revenue with strong growth in healthcare consumables, services, hardware-as-a-service and software subscriptions, continues to support higher revenue visibility and the potential for further EBITDA margin and earnings expansion.
See why 1 investors see Fortive as 6% undervalued.
Result: Fair Value of $64.00 (UNDERVALUED)
Still, Fortive’s story can wobble if lower margin products keep diluting profitability or if future acquisitions and buybacks fail to lift per share results.
Find out about the key risks to this Fortive narrative.
Another View: Fortive Through The P/E Lens
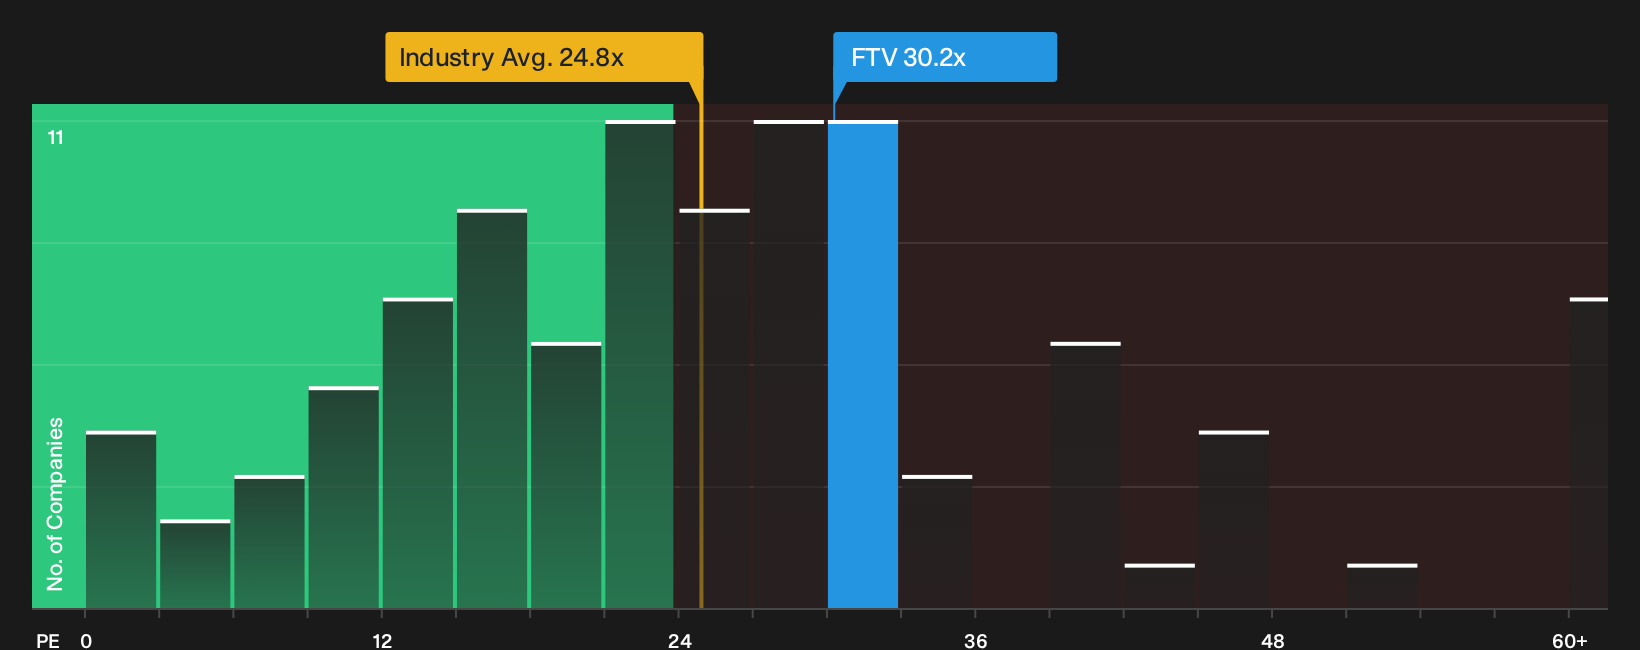
Fortive might look undervalued on fair value estimates, yet the market is asking a rich price on earnings. The stock trades on a 30.2x P/E versus 24.8x for the US Machinery group and a fair ratio of 21.9x, which points to meaningful valuation risk if sentiment cools.
That is where a simple earnings multiple cuts against the bullish story. A move toward the 21.9x fair ratio or even closer to peers would require either faster profit growth than forecast or a lower share price. Which side of that tradeoff do you think is more realistic for Fortive over time, given its 9% expected earnings growth.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Fortive feels familiar, do not sit on the fence. Instead, take a closer look at the numbers, pressure test the data, and weigh both sides using the 3 key rewards and 1 important warning sign.
Looking for more Fortive style investment ideas?
Do not stop your work at Fortive alone. Broaden your watchlist with fresh opportunities surfaced by the Simply Wall Street Screener so you keep seeing the full field.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that highlight businesses built to handle tougher conditions.
- Hunt for potential mispricings by reviewing a curated 27 high quality undervalued stocks that couples strong underlying quality with prices that may lag fundamentals.
- Prioritise stability and staying power with a 30 resilient stocks with low risk scores that filters for companies scoring well on key risk checks before trouble shows up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com