


EN
NKT (CPSE:NKT) Has A Fresh Update, But What Is The Market Missing?
NKT (CPSE:NKT) has just completed a €50 million expansion of its medium and high voltage power cable plant in Esposende, Portugal, adding new production lines, testing facilities and more than 150 employees.
The Esposende expansion comes at a time when NKT’s momentum has cooled in the short term, with the share price down 13.84% over the past month and 9.34% over 90 days. However, the 1-year total shareholder return of 8.33% and very strong 3 and 5 year total shareholder returns indicate that long term holders have still seen meaningful gains.
Scan other grid and infrastructure players that are responding to the same energy transition themes by reviewing our curated list of 42 power grid technology and infrastructure stocks alongside NKT.
Short term sentiment around NKT has cooled just as fresh capacity comes online in Portugal. Does that recent share price pullback already reflect the risks, or are you still paying up for the growth story when you run the numbers?
Most Popular Narrative: 18% Undervalued
NKT closed at DKK806, while the most followed narrative points to a fair value of DKK988.58. As a result, the market price sits well below that estimate and puts execution of the growth plan under the spotlight.
The €2b capex program running from 2025 to 2028, including large-scale high-voltage expansions, multiple medium-voltage plant upgrades and the Eleonora vessel and T3600 trencher, is designed to increase capacity and support vertical integration, which can support higher revenue, asset utilization and margin quality once these assets move from ramp-up to steady-state.
Find out how 28 investors see NKT as 18% undervalued.
Result: Fair Value of DKK988.58 (UNDERVALUED)
Still, the narrative around NKT could crack if transmission revenue softness extends beyond 2026 or if higher ramp-up costs continue to pressure group EBITDA margins.
Find out about the key risks to this NKT narrative.
Another View: What NKT’s Market Pricing Is Saying
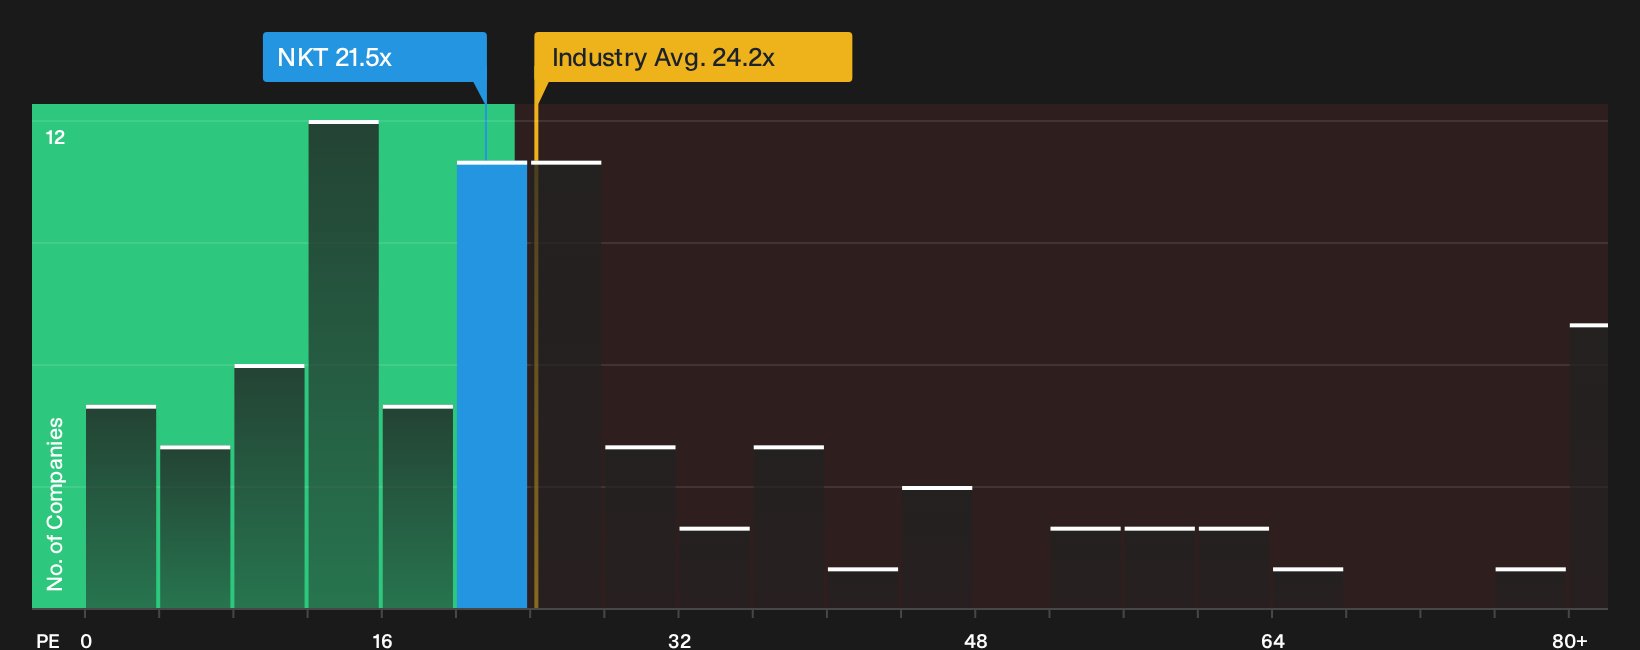
NKT screens as undervalued on the fair value estimate, with DKK806 trading 55.3% below the DKK1,803.21 future cash flow value. Yet the current P/E of 21.5x is only slightly above the 21x fair ratio and below the European Electrical sector on 24.2x. Is the market already pricing in part of that upside, or is the discount pointing to something the cash flow model misses?
To stress test the story from a different angle, review how the earnings multiple, peer comparison and fair ratio interact in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around NKT can feel confusing, so treat this as your cue to move quickly, review the underlying data, and consider both perspectives. Weigh the potential upside against the concerns using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NKT?
If NKT has you thinking more broadly about where to put fresh capital to work, now is the moment to widen your radar and pressure-test other opportunities.
- Spot potential bargains early by scanning our universe of mispriced quality using 192 high quality undervalued stocks.
- Strengthen your income stream by analysing companies in our hand picked set of 226 dividend fortresses.
- Dial down portfolio risk by focusing on durable businesses surfaced in the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com