


EN
Citizens & Northern (CZNC) Stock Climbs On Strong Q3 Earnings Power
Citizens & Northern just posted Q3 2026 results and the market loved it on first read. The stock jumped 4.2% to US$27.75, extending gains from the past month. That reflects the initial emotion in the market. The anchor is earnings per share of about US$0.92 on revenue of roughly US$42.7 million, supported by a net interest margin of 4.13% that many regional lenders would likely view as attractive in the current environment.
Price is reacting to the earnings headline. The key question for investors is whether this level of profitability supports a P/E of around 14x in a sector where some peers trade at lower multiples and where concerns about credit quality remain an important consideration.
Like the earnings power at Citizens & Northern but uneasy about paying a mid-teens P/E while credit risk still hangs over regional lenders? You may want to explore our list of solid balance sheet and fundamentals stocks (25 results) for banks and financial stocks that pair profitability with sturdier balance sheets.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$42.73 million vs. US$27.40 million (sharply higher year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$16.29 million vs. US$6.50 million (strong year on year uplift)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.92 vs. US$0.42 (solid improvement per share)
- Net Interest Margin, or NIM, (Q3 2026 vs Q3 2025): 4.13% vs. 3.62% (firmer lending spread)
Citizens & Northern’s earnings growth flipped sharply over the last year. Ask Charlie what drives Citizens & Northern’s jump in earnings growth.
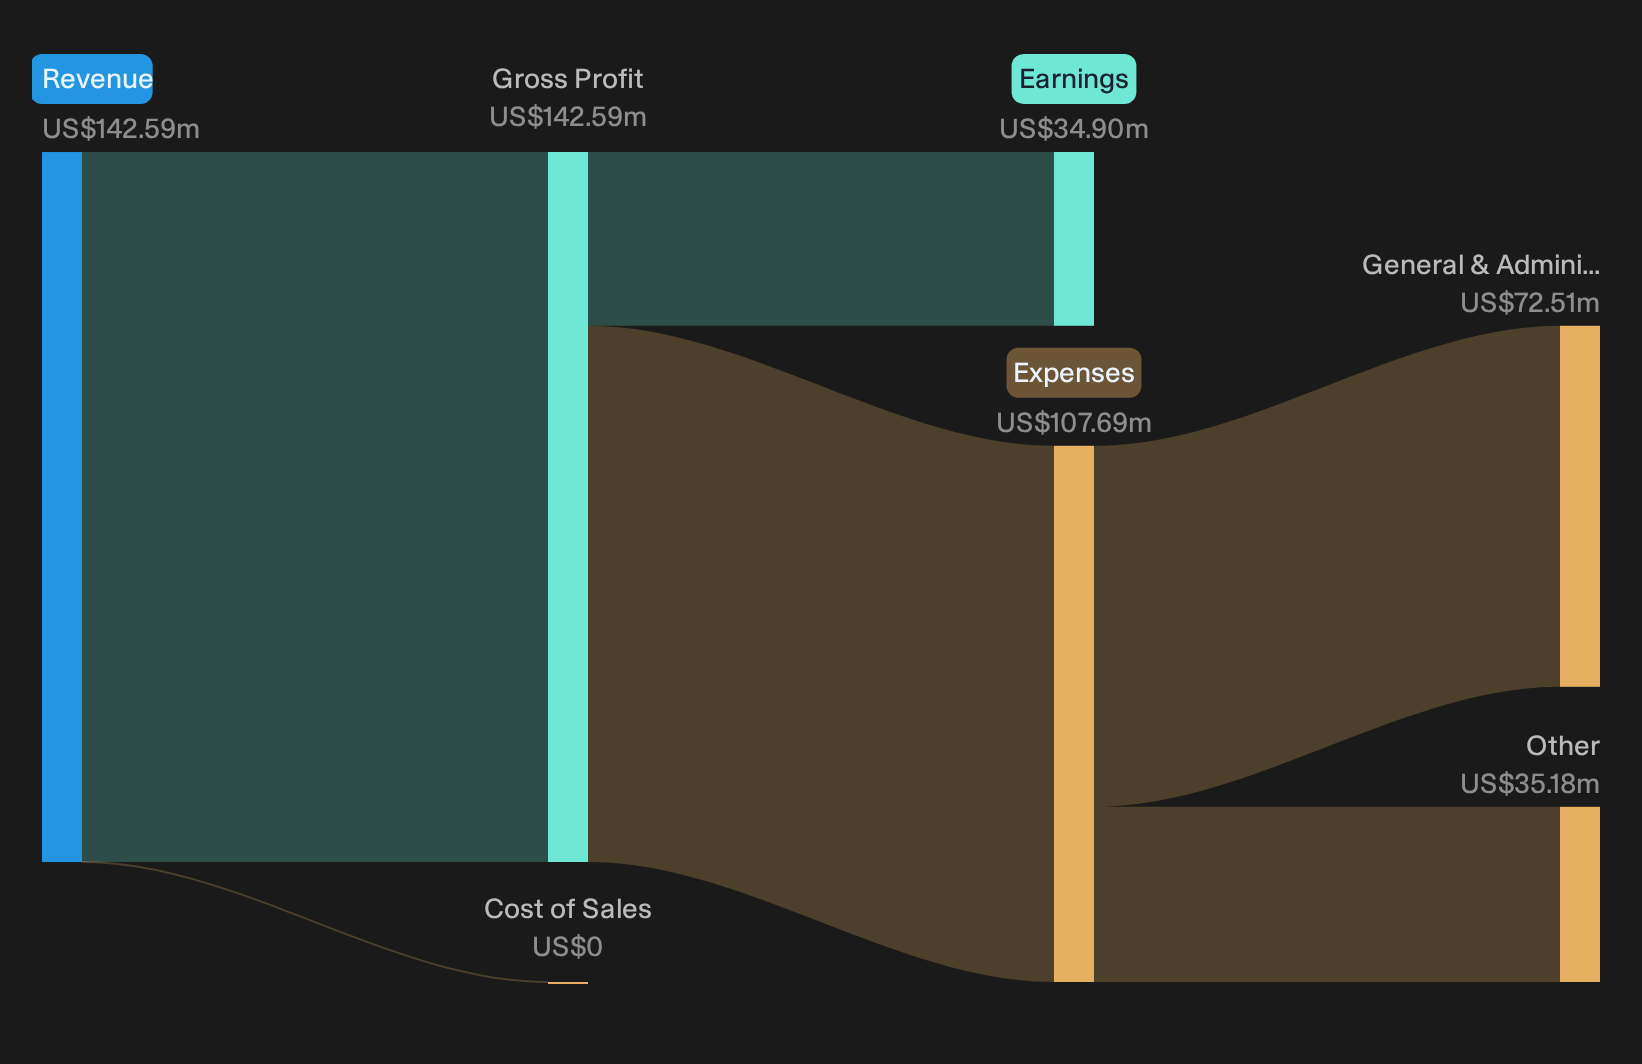
CZNC earnings that back the community-bank story
Citizens & Northern just put hard numbers behind the steady community bank image. Revenue and net income are well above Q3 2025 levels, and earnings per share almost doubled. That kind of step up usually points to better earning power rather than just cost cutting noise. A 4.13% net interest margin also fits the story of a bank that knows its local lending turf and is still earning a solid spread. For investors who see CZNC as a relationship lender with multiple product lines, this quarter lands on the supportive side.
Where the cautious CZNC thesis still bites
The brighter income picture does not automatically erase the usual worries around a smaller regional lender. Results do not say much about loan quality or any concentration in specific sectors, which are exactly the pressure points cautious investors flag. The strong jump in profitability can ease immediate concern about earnings resilience, yet it does not directly answer questions about future credit costs or regional economic shocks. For now, the data softens the near term bear case on earnings power while leaving the broader risk narrative largely intact.
Reveal where the calm headline reaction in Citizens & Northern could fracture over the next few reporting cycles by accessing the multi-year analyst estimates for Citizens & Northern.Hunt For The Quiet Disconnects
Citizens & Northern just reminded investors that sentiment can shift quickly when earnings power appears more secure. The real opportunity is spotting stocks that could be undervalued before the market fully reassesses them.
- Company 1 - 36% below our estimate - uses expanded engine capacity to pursue long-duration power projects linked to rising data center electricity needs.
- Company 2 - 24% below our estimate - embeds artificial intelligence tools into daily workflows so established cloud clients adopt more integrated subscription services.
- Company 3 - 28% below our estimate - sells diagnostic equipment and test platforms that utilities and aerospace contractors use as grids and fleets adapt to heavier electric loads.
That is three of the list. See all 27 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com