


EN
Carnival (CCL) Stock Looks Below Fair Value Following Its 138% Run
Carnival has seen its share price move sharply over the past few years, and the recent swing in sentiment now puts the focus squarely on what its current earnings really justify. With fresh headlines around record bookings, shifting ship deployment and debt reduction, the key issue for you is whether the recent price around US$26 is in line with the company’s profit power.
- Over the past 3 years the stock has gained about 138.4%, which puts a lot of weight on the question of whether current earnings can sustain that kind of re-rating.
- Record revenue, stronger net income and ongoing debt reduction can influence how much of Carnival’s current earnings flow to shareholders rather than to lenders, which matters directly for any earnings based valuation.
- The analysts covering Carnival have run their own numbers. See what analysts think Carnival's shares could be worth.
The stock's next move may depend on whether Carnival's current share price is fully supported by the earnings it is generating today.
If you are weighing Carnival against other opportunities tied to earnings power and recent news momentum in cruising and travel, it can help to compare it with 27 high quality undervalued stocks.
Is Carnival a Bargain on Earnings?
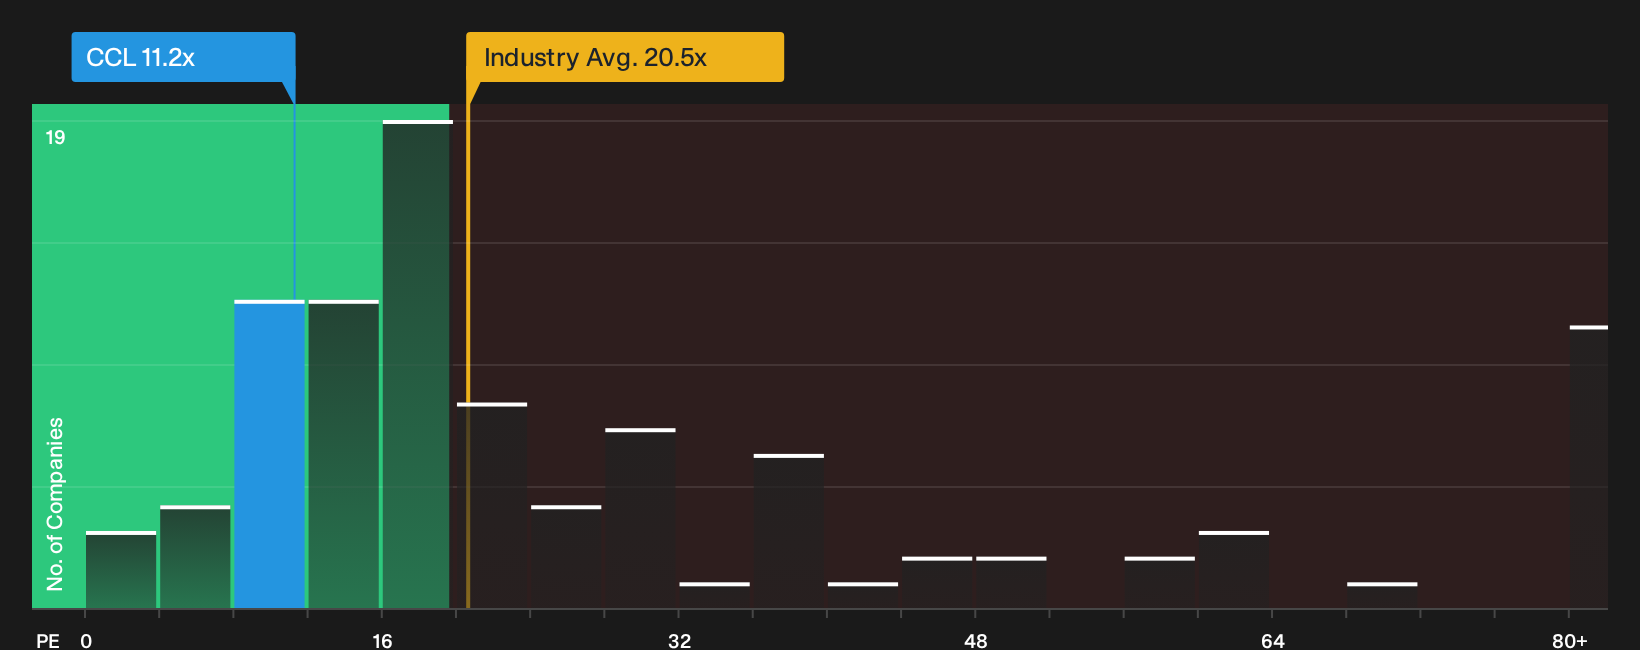
The P/E ratio works well for Carnival because investors are closely watching how much of its cruising demand turns into bottom line profit. At roughly 11.2x earnings, Carnival trades at a clear discount to the wider hospitality sector, where the average P/E is about 20.5x, and also below cruise peers on roughly 17.0x.
That gap is larger than the tailored fair multiple that models would imply once Carnival's margins, risks and size are factored in, which points to the stock screening as undervalued on this metric. Because the recent record bookings and debt reduction headlines have already lifted sentiment, a P/E below both the industry and peer benchmarks suggests the current price does not fully reflect the earnings power the market is already seeing. Explore the numbers behind Carnival's P/E valuation.
The Carnival Narrative: What Would Justify Today's Price?
Narratives for Carnival pick up where the P/E comparison leaves off and outline which paths for cruise demand, profitability and reinvestment would need to occur for the stock to be worth meaningfully more or less than today’s price. Where a single multiple or model gives you one tidy outcome, Narratives break that number into specific future assumptions so you can follow over time whether Carnival’s actual performance supports them, all housed on Simply Wall St’s Community page.
One of the top community narratives on Carnival: 23% undervalued
Further balance sheet repair after cutting total debt from about US$36b in 2023 to below US$24b and lowering net debt to adjusted EBITDA…
Discover why this Narrative puts Carnival at 23% undervalued.
One more Carnival check that belongs next to the earnings multiple
The final piece worth your attention is who is steering Carnival and how their pay lines up with the outcomes you care about as a shareholder. See who runs Carnival and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com