


EN
Boyd Gaming (BYD) Stock Shrugs Off Q3 Earnings Margin Compression
Boyd Gaming stock barely flinched after earnings, slipping 0.8% to close at US$71.69, yet the Q3 2026 print was anything but sleepy. The casino operator posted basic earnings per share of US$1.71 on revenue of US$990.5 million, results that sit inside a much bigger story about profitability pressure. Margins have been squeezed over the past year as one very large one off gain dropped out of the rearview, and that tension between shrinking underlying profitability and a low 10.4x trailing P/E is what will matter for longer term holders.
Love Boyd Gaming's low 10.4x trailing P/E but concerned about margins coming off a one off boost and underlying profitability getting compressed? Check out our screener of resilient companies with both earnings power and stronger balance sheets in the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$990.5 million vs. US$1,004.4 million (slightly lower year over year)
- Net Income (Excl. Extra Items) (Q3 2026 vs. Q3 2025): US$124.9 million vs. US$1,440.0 million (very large decline after a prior-period one-off gain)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.71 vs. US$17.81 (very large drop as the prior-year quarter included a significant one-off benefit)
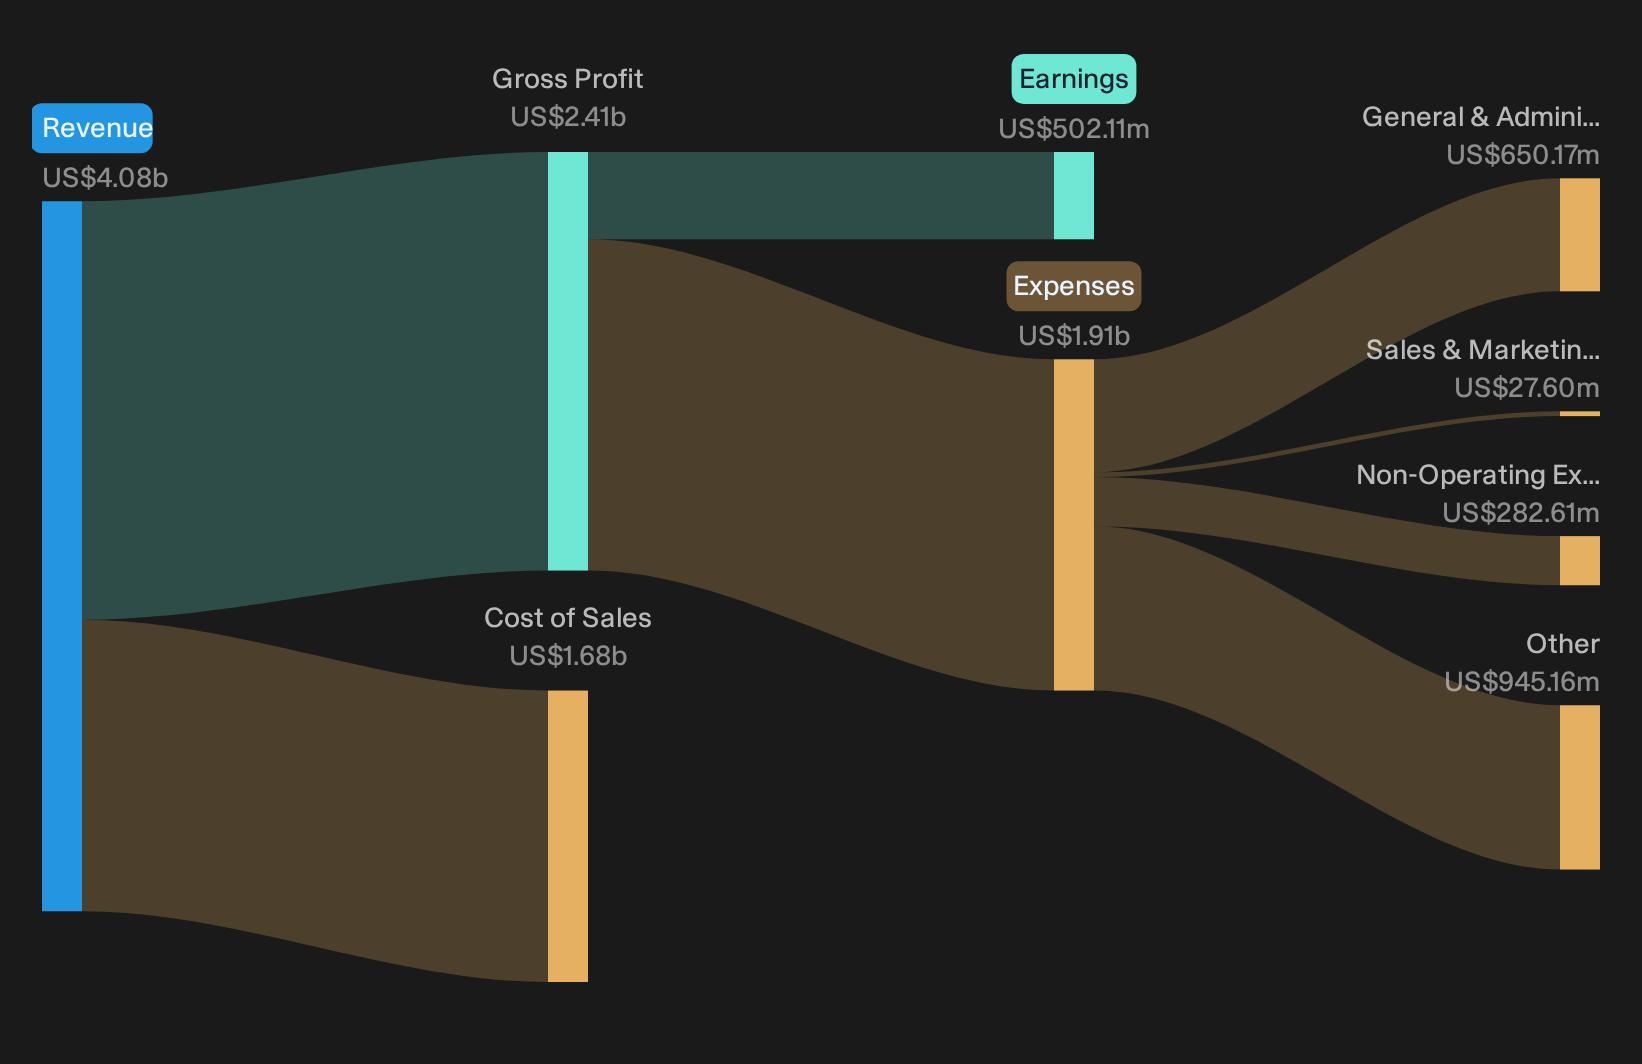
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 12.3% vs. 46% (margin sharply lower following the earlier one-off gain of about US$1.7 billion rolling out)
Boyd Gaming is steering investors to the high end of its online guidance. Ask Charlie what Boyd Gaming sees in its online growth runway.
Boyd Gaming: Testing The Growth Engines
The bullish story leans heavily on local projects, asset light deals and online earnings stepping up over time.
"Ongoing expansion at Cadence Crossing and across the broader Las Vegas locals portfolio, supported by resilient play from core and retail customers and property margins above 50%, can continue to lift revenue and EBITDAR as new properties move from ramp up to steady state earnings."
Q3 shows parts of that playing out, but not uniformly. Midwest & South improved, and Las Vegas locals excluding Orleans and Suncoast grew revenue and EBITDAR about 3% with margins near 47%. That is below the 50% ambition, and destination softness plus construction noise kept the whole locals portfolio from clearly hitting the milestone.
Boyd Gaming: Stress Testing Key Risk Warnings
Bears worry that construction, weaker destination play and limited cash generation could undercut the Boyd Gaming plan.
"Ongoing and future construction projects, including the Suncoast modernization that has already reduced quarterly EBITDAR by roughly US$3 million, could cause longer or wider disruption than expected. This would limit the benefit of the capex program and weigh on property level margins and consolidated EBITDAR."
Q3 numbers echo that concern. Companywide revenue and EBITDAR slipped about 1% on a reported basis and Las Vegas locals were held back by both Suncoast renovation impact and softer Orleans destination demand. At the same time, adjusted figures and strong Sky River and Online growth suggest disruption is material but not yet derailing the broader capex thesis.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Mispricings Now
Boyd Gaming just showed how a stock can barely move even when the story underneath is shifting. The real opportunity is spotting companies that could be mispriced before the rest of the market catches on.
- Company 1 - 45% below our estimate - builds a broader Pacific banking platform as a new acquisition adds low cost deposits and fresh lending capacity.
- Company 2 - 42% below our estimate - expands from solar trackers into storage and inverter equipment so existing customers can scale projects despite grid constraints.
- Company 3 - 25% below our estimate - sells injectable therapies for weight management and diabetes as demand for key treatments reshapes its revenue mix.
That is three of the list. See all 27 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com