


EN
Gjensidige Forsikring (OB:GJF) Stock Can Q3 Earnings Justify A 20.4x P E
Gjensidige Forsikring came into Q3 2026 with a rich reputation as a high quality Nordic insurer and a P/E of 20.4x that already priced in a lot of faith. The headline delivered on that premium story. Profit after tax landed at NOK 2.077b, built on a powerful general insurance service result and an annualized return on equity of about 34.2%.
Yet the share closed at NOK 260 today and has drifted down roughly 6.8% over the past three months. The price flicker looks cautious, the underlying profitability looks anything but.
Love the 34.2% return on equity at Gjensidige Forsikring but concerned about paying a 20.4x P/E for an insurer that the market has started to cool on? Scan our 221 resilient stocks with low risk scores to see how other resilient, lower risk profiles stack up beside OB:GJF.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): NOK 11,806.3m vs NOK 12,234.1m (declined 3.5%)
- Net Income, excl. extra items (Q3 2026 vs Q3 2025): NOK 2,076.7m vs NOK 1,542.4m (up 34.7%)
- Basic EPS (Q3 2026 vs Q3 2025): NOK 4.08 vs NOK 3.05 (up 33.8%)
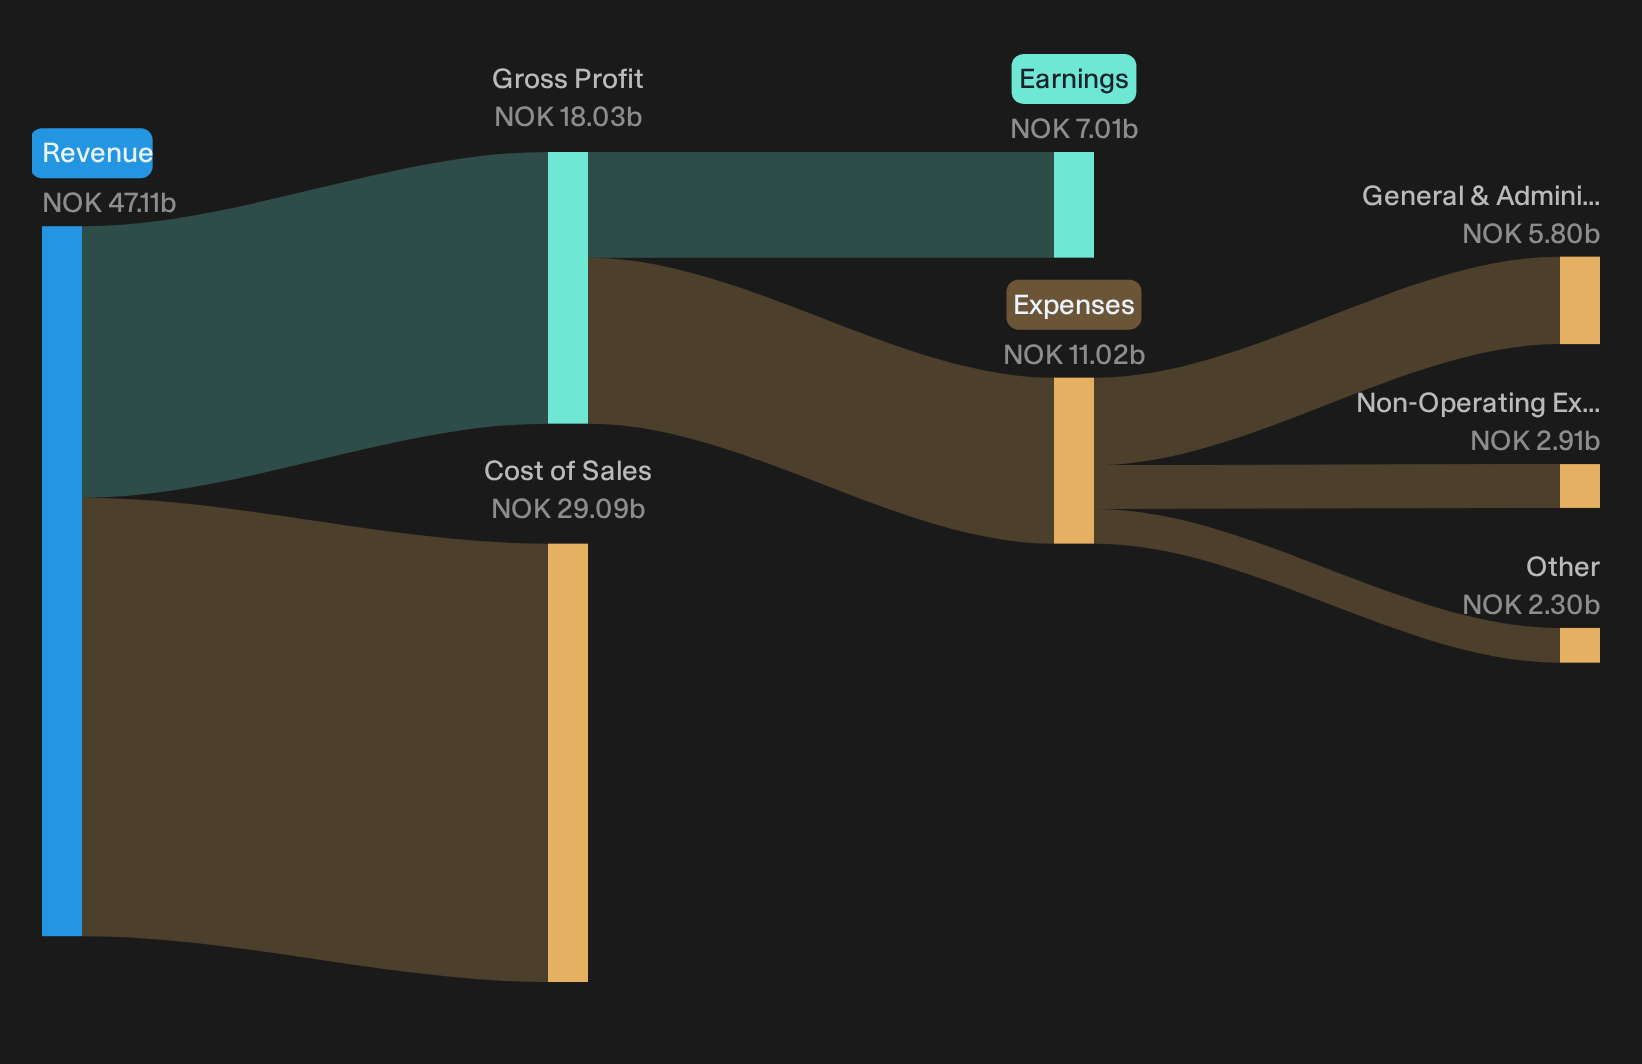
- Trailing 12M Net Income, excl. extra items (Q3 2026 vs Q3 2025): NOK 7,009.8m vs NOK 6,178.6m (up 13.4%)
Earnings prints can look strong on their own, but investors who care about valuation usually want to see whether cash being generated tells the same story. When you focus on Gjensidige Forsikring's cash flows rather than just the income statement, the stock could be a whopping 41% undervalued.
Gjensidige Bull Case: Pricing Power Meets Capital Proof
The bullish story around Gjensidige Forsikring hinges on its ability to harden the book, hold on to customers and turn that into sturdier earnings power over time.
"A key factor is that Gjensidige Forsikring continues to match or exceed claims inflation in its pricing while maintaining high customer retention and progressing digital automation."
Q3 points in that direction. Insurance revenue grew in local currency while management consciously accepted lower volumes in parts of Commercial to defend margins. The combined ratio of 73.6% and a 190% Solvency II ratio show pricing, risk selection and capital strength moving together, supported by higher straight through claims processing and ongoing tech restructuring.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Gjensidige Bear Case: Danish Claims Risk Still Looms
The cautious view argues that Danish workers’ compensation and large loss volatility could quietly eat away at Gjensidige Forsikring's cushion.
"the extra Danish workers’ compensation burden and structurally volatile large loss events leave less room to absorb any mispricing or higher claims frequency in these newer channels, which could dilute the positive impact on revenue and earnings."
This quarter, the combined ratio of 73.6% and materially better frequency loss ratios suggest that pressure has not yet bitten into profitability. Large losses were below the normal level and the Solvency II ratio of 190% signals ample capital. The risk is timing. One strong print does not remove future shock potential from Danish claims or partnership mispricing.
Hunt For Quiet Mispricings Now
Gjensidige Forsikring just showed how strong fundamentals and a cooling share price can move apart. The real opportunity is spotting stocks that could be undervalued before sentiment catches up.
- Company 1 - 49% below our estimate - earns recurring fees from gaming operators as they shift table play to outsourced live casino studios.
- Company 2 - 35% below our estimate - tightens industrial flow control margins as aftermarket service and valve demand increase with long-cycle power projects.
- Company 3 - 45% below our estimate - expands sterile injectable contract manufacturing capacity as clients shift complex drug fill-and-finish work to specialists.
Three companies from the same screener. Open every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com