


EN
Is XtalPi Holdings (SEHK:2228) Fully Priced On Its New siRNA Candidate?
XtalPi Holdings (SEHK:2228) drew fresh investor attention after announcing its first internally developed siRNA preclinical candidate for IgA nephropathy. The candidate was completed in nine months using its Kodexia platform.
The announcement landed against a tricky trading backdrop. XtalPi Holdings has a 1-day share price return of 3.25% and a 7-day share price return of 2.11%. However, the 30-day share price return is down 27.91% and the year-to-date share price return is down 39.49%, while the 1-year total shareholder return has fallen 47.02%. This points to pressure over the longer stretch even as short-term momentum has ticked higher around the siRNA update.
Scan other AI-driven drug discovery stocks that are showing similar potential inflection points with the curated list of 126 healthcare AI stocks while XtalPi Holdings puts its Kodexia platform to work on siRNA.
XtalPi Holdings now trades well below the average HK$9.93 analyst target after that siRNA driven bounce. Does fair value sit closer to the current HK$6.05 price or nearer the upper estimate range?
Preferred Price-to-Sales of 32.6x: Is it justified?
XtalPi Holdings trades on a P/S ratio of 32.6x, which is far higher than both its industry and peer benchmarks. For anyone looking at the recent HK$6.05 share price and the HK$9.93 analyst target, that gap in sales multiple is an important piece of context.
The P/S ratio compares a company’s market value to its revenue. For a platform style drug discovery business like XtalPi Holdings, investors often focus on this measure when earnings are still negative, since it anchors the valuation to actual sales rather than profits that are not yet in place.
In this case the current 32.6x P/S means the market is valuing each HK$1 of revenue at more than seven times the Asian Life Sciences industry average of 4.2x. It is also far above the peer group average of 12.1x. The estimated fair P/S ratio of 8.8x is also materially lower than where the stock trades today, which signals a level the market could potentially move towards if expectations moderate.
Explore the SWS fair ratio for XtalPi Holdings.
Result: Price-to-sales of 32.6x (OVERVALUED)
Still, the recent share price pressure and ongoing net loss of CN¥210.949m leave little room for execution missteps on XtalPi Holdings’ high multiple story.
Find out about the key risks to this XtalPi Holdings narrative.
Another view on XtalPi Holdings’ value
The first check using the rich 32.6x P/S already points to a stretched tag for XtalPi Holdings. A second pass using the SWS DCF model is even harsher. At HK$6.05, the share price sits well above an estimated future cash flow value of HK$0.56, which leans toward an overvalued signal. That split between sales based optimism and cash flow based caution raises a simple question: Which lens do you trust more for a loss making AI drug discovery platform?
For anyone weighing that gap, it can help to see how the underlying assumptions feed through the model output in detail. Look into how the SWS DCF model arrives at its fair value.
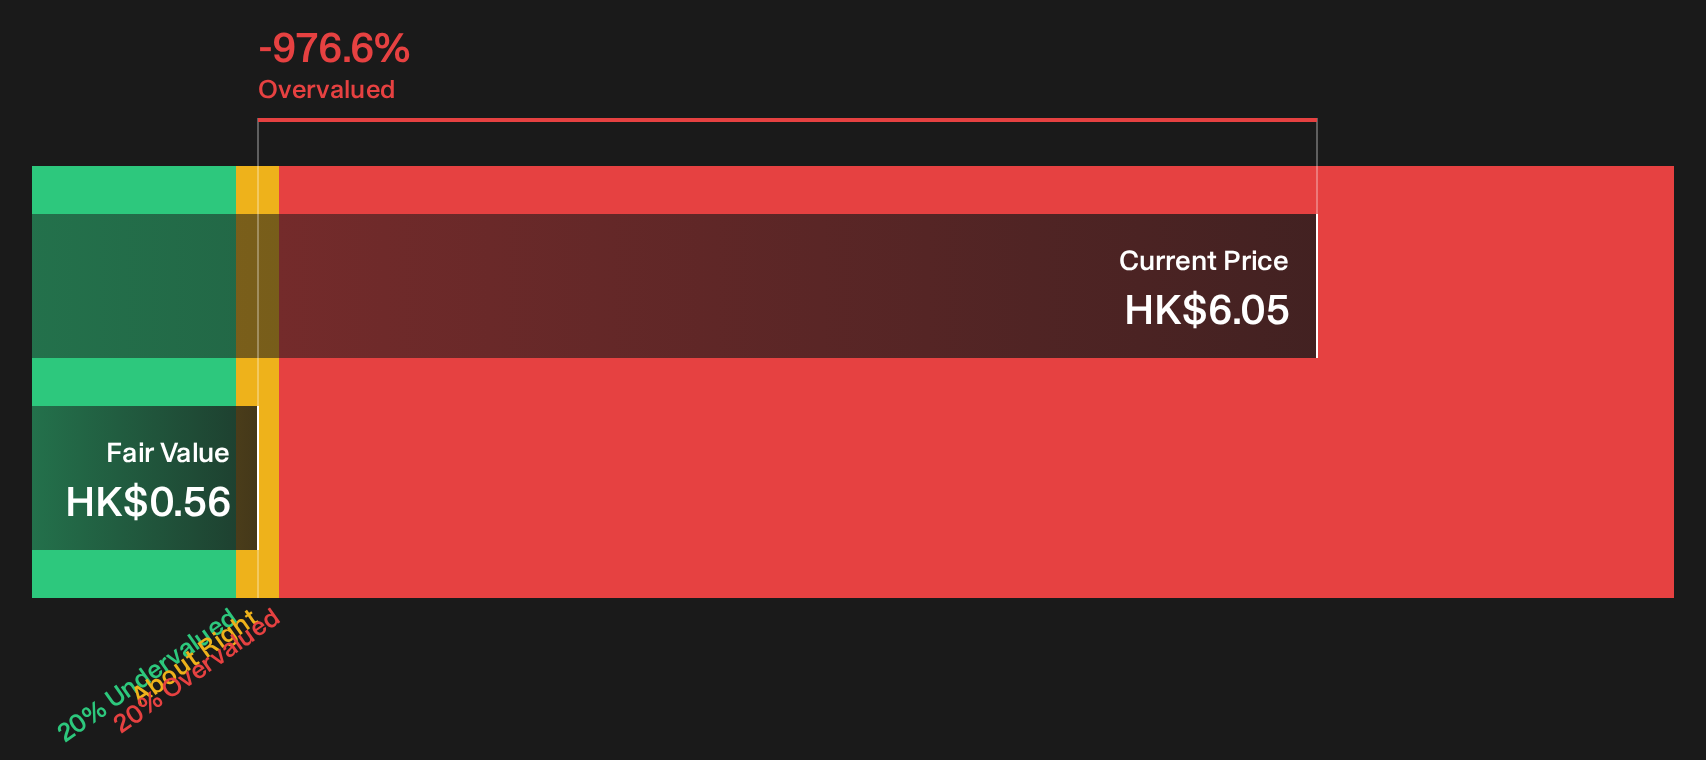
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out XtalPi Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this read on XtalPi Holdings feels mixed, treat it as a starting point and pressure test the numbers yourself before sentiment settles. To balance the risks against the upside investors currently see, review the 1 key reward.
Looking for more investment ideas beyond XtalPi Holdings?
If XtalPi Holdings is already on the watchlist, do not stop there. Broader ideas from different corners of the market can round out the opportunity set.
- Target resilient income by reviewing companies in the 226 dividend fortresses that combine higher yields with a focus on sustaining payouts.
- Hunt for quality at a discount by scanning the 201 high quality undervalued stocks where solid fundamentals meet more modest pricing.
- Spot future contenders early by checking the 615 high quality undiscovered gems before the crowd starts paying closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com