


EN
Cullen/Frost Bankers (CFR) Has Investors Watching Closely, What Is Behind The Attention?
Analyst expectations and recent sentiment
Cullen/Frost Bankers (CFR) heads into its upcoming quarterly update with earnings forecasts revised higher and four straight consensus beats shaping investor expectations about how the next set of numbers might influence the stock.
Recent price action reflects that optimism. Cullen/Frost Bankers has a 1-day share price return of 1.33% and a year-to-date share price return of 23.02%. Its 1-year total shareholder return of 31.39% signals stronger momentum despite a 90-day share price pullback of 3.99%.
Compare how Cullen/Frost Bankers stacks up against other financially solid opportunities, and move quickly on a curated list of solid balance sheet and fundamentals (26 results) that share similar resilience traits.
Bulls point to Cullen/Frost Bankers’ earnings momentum and recent price strength. Bears focus on the pullback and rich expectations. Which side does the current valuation actually support next?
Most Popular Narrative: 10% Undervalued
Cullen/Frost Bankers closed at $157.68, while the most widely followed narrative pegs fair value at about $174.86. This frames analyst optimism around Texas growth, earnings quality and capital returns.
The active use of the US$300m share repurchase program, with US$90m deployed in the second quarter of 2026 after earlier quarters of buybacks, reduces the share count and can increase per share earnings and dividend capacity if the underlying profit outlook for Cullen/Frost Bankers is achieved.
See why 4 investors see Cullen/Frost Bankers as 10% undervalued.
Result: Fair Value of $174.86 (UNDERVALUED)
Still, Cullen/Frost Bankers leans heavily on Texas, so any local real estate stress or sustained deposit pricing pressure could quickly challenge that 10% undervalued thesis.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another view of Cullen/Frost Bankers’ valuation
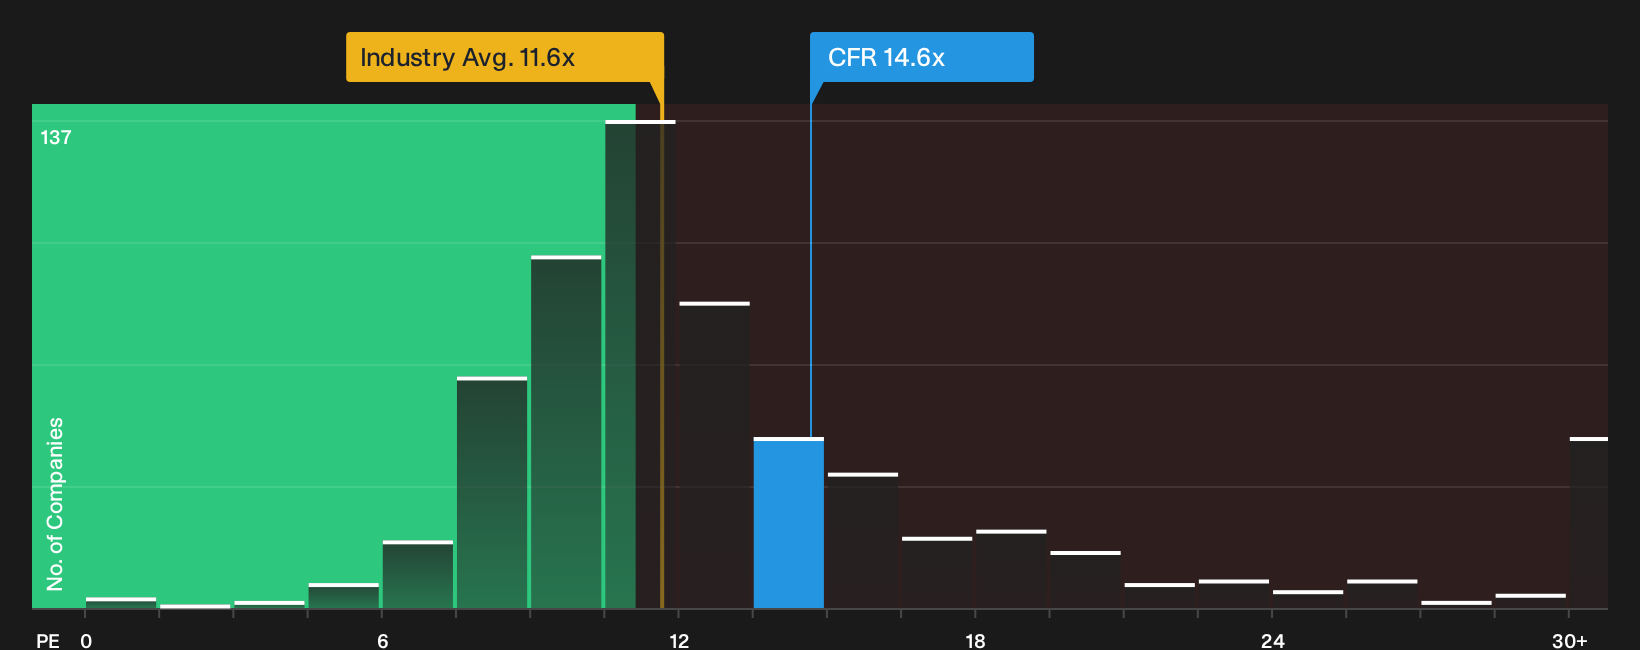
On earnings expectations and fair value models, Cullen/Frost Bankers screens cheap. On simple pricing, it looks expensive. The stock trades on a P/E of 14.6x versus 11.5x for the US Banks industry, a peer average of 11.4x, and a fair ratio estimate of 11.4x that the market could eventually gravitate toward. That gap points to valuation risk if sentiment cools before fundamentals catch up, so how comfortable are you paying a premium for a bank that already screens above its sector on this measure?
To pressure test that premium and see what the numbers imply at different earnings levels, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual check on how that premium compares with the wider sector, review the latest relative valuation snapshot in
Next Steps
Opinion is divided in this Cullen/Frost Bankers story, which makes this a good moment to move quickly and review the numbers yourself. To see what optimists are focusing on, review the 3 key rewards
Looking for more Cullen/Frost Bankers investment ideas?
Do not stop with one bank. Broaden your watchlist using targeted stock filters that surface different types of opportunities across quality, income and risk.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (26 results) that highlights companies pairing financial strength with underlying business stability.
- Hunt for potential mispricing by reviewing a focused 29 high quality undervalued stocks that spotlights quality businesses trading below their assessed worth.
- Build a cash flow stream by assessing a handpicked 6 dividend fortresses designed to surface income ideas with yields that may support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com