


EN
Sberbank Stock And Russian Banks Facing A 14% Rate Test
Russia’s central bank just froze its key rate at a hefty 14%, and that single decision now ripples through every mortgage, deposit and corporate loan in the country. High borrowing costs can hurt growth, yet they can also fatten interest margins for the right financial stocks. This article unpacks how that trade off plays out and walks through three Russian financial stocks closely exposed to this rate shock.
The three stocks covered next are only a small sample of the high-rate exposures filtered by this idea. The full Simply Wall St screen surfaced 0 more Russian financial companies with equally detailed stories that are not covered below. To identify and analyze the wider set of potential high-interest-rate beneficiaries in one place, go straight to the High-Interest-Rate Beneficiaries in the Russian Financial Sector screener.
Bank Saint-Petersburg (MISX:BSPB)
Overview: Bank Saint-Petersburg is a universal Russian lender that serves retail, corporate and private banking clients through physical branches and digital channels.
Market Cap: RUB34.6b
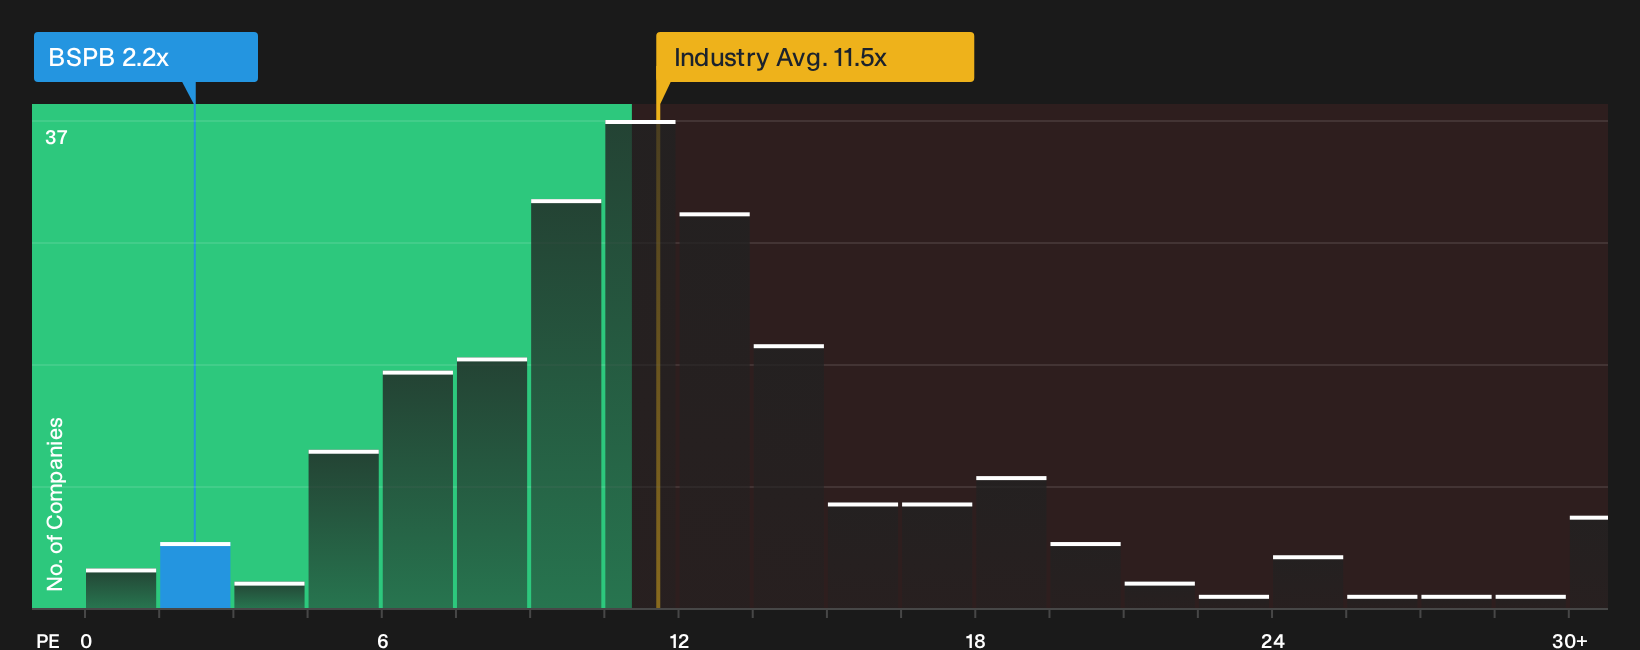
Bank Saint-Petersburg directly fits a high-interest-rate theme because a large regional deposit base can support wider net interest margins when policy stays tight. The stock trades on a very low P/E compared with peers and has recently reported strong net income for 2026. Investor attention now hinges on how one unseen pressure shapes those margins if high rates start to stress borrowers.
If you want to see how that pressure shows up in real numbers, pull up the Bank Saint-Petersburg financial health report for a closer read on Bank Saint-Petersburg’s resilience.
Sberbank of Russia (MISX:SBER)
Overview: Sberbank of Russia is a large universal lender that provides banking, payments, insurance and investment services to households and businesses.
Market Cap: RUB2,993.5b
High policy rates matter for Sberbank of Russia because a huge retail and corporate deposit base can feed wider interest spreads when loans are repriced. Tight monetary policy and a 14% key rate keep that margin story in focus, although the real test arrives if one quiet fault line inside the loan book starts to shift.
If that quiet fault line has your attention, read the 4 key rewards and 4 important warning signs (1 is major!) to see how Sberbank of Russia’s upside compares with its pressure points.

Credit Bank of Moscow (MISX:CBOM)
Overview: Credit Bank of Moscow is a large Moscow based lender offering corporate, retail and investment banking that can benefit from high interest rates.
Market Cap: RUB164.3b
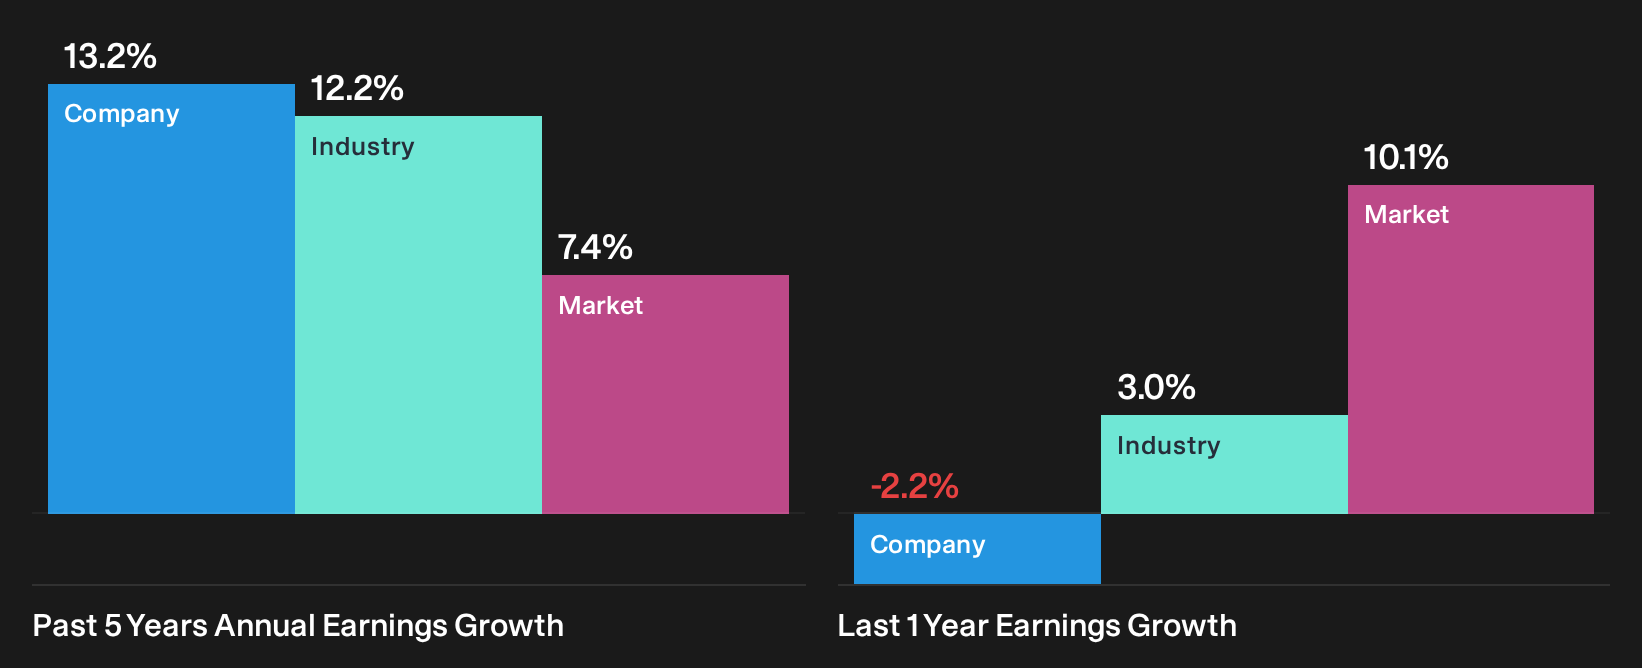
Credit Bank of Moscow sits in this high rate screen because its broad loan book and recent net interest income gains tie directly to a 14% policy rate. H1 2026 net interest income reached RUB55,331 million, with earnings forecast to grow strongly. However, elevated bad loans at 2.5% mean a single shift in credit stress could reshape that margin story.
That credit stress risk is exactly why the 1 key reward and 2 important warning signs (1 is major!) can be so useful for spotting where Credit Bank of Moscow’s story could sharply accelerate or stall.
Seeking Alternatives Before The Crowd?
Fresh ideas move first, and by the time momentum is flying the easiest gains can be gone. Scan these under the radar picks while it matters and consider them early in your research process.
- Spot cash generators that still trade like they have been ignored by the market, starting with the 201 high quality undervalued stocks.
- Track where AI revenue stories already translate into profits rather than promises by scanning the curated 39 profitable AI stocks that aren't just burning cash.
- Follow the cash flows into essential infrastructure for the AI build out, using the focused 55 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com