


EN
Vector (NZSE:VCT) Could Be 8% Undervalued As Electricity Connections Grow
Fresh operating data from Vector (NZSE:VCT) shows electricity connections up 1.6% and new connections up 8.8%, while gas connections and volumes declined, sharpening investor attention on the Auckland focused energy distributor.
Recent trading has been mixed for Vector, with the share price up 3.11% on the day to NZ$4.64, yet down 7.39% over 90 days. The 1-year total shareholder return has slipped 1.96%, while the 5-year total shareholder return has gained 49.52%.
Scan how Vector's mix of growing electricity usage and softer gas demand compares with peers by running the same lens across 42 power grid technology and infrastructure stocks in similar network and infrastructure plays.
Vector’s share price has slipped over 90 days even as electricity metrics improve and analysts sit above the current NZ$4.64. So where does a fair valuation genuinely cluster inside that spread?
Most Popular Narrative: 8% Undervalued
Vector's most followed narrative pegs fair value at NZ$5.05, slightly above the latest NZ$4.64 close. The gap between regulated electricity growth and a declining gas arm becomes the critical swing factor.
Higher expected long term electricity demand from Auckland's urban growth and wider electrification of transport, heating and industry is aligned with Vector's 20 year, roughly $10b electricity network investment plan. This plan is intended to support a larger regulated asset base and future regulated revenue and EBITDA.
See why 7 investors see Vector as 8% undervalued.
Result: Fair Value of NZ$5.05 (UNDERVALUED)
Still, the narrative can unravel if gas distribution keeps shrinking faster than expected, or if the planned $10b electricity investment strains cash flow and funding capacity.
Find out about the key risks to this Vector narrative.
Another View: Vector Through The Earnings Lens
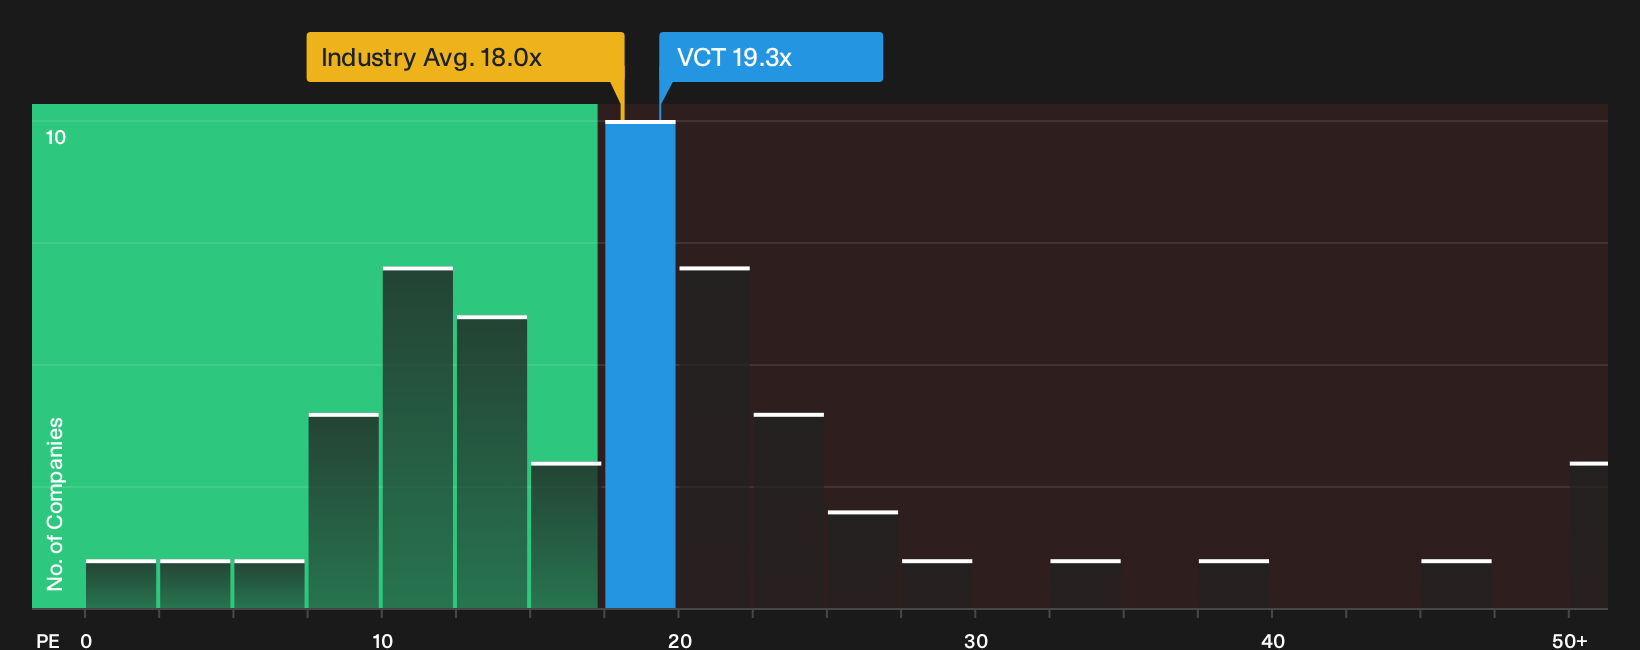
That 8% undervalued fair value at NZ$5.05 leans on analyst narratives and price targets. A simple P/E check tells a different story. Vector trades on 19.3x earnings, above the global integrated utilities average of 18x, yet below an estimated fair ratio of 27.9x.
In practice, that mix points to a stock that already carries some valuation risk versus the wider sector, while still sitting well under what the fair ratio suggests the market could move toward if sentiment improves. The key question for you is whether Vector’s balance of growth, debt and gas decline justifies paying above industry multiples today.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Vector story feels finely balanced between opportunity and concern, move quickly to review the data and form your own view using 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Vector?
You do not need to stop with Vector. Use the Simply Wall St screener to quickly surface fresh opportunities that fit your risk, income, and quality preferences.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (205 results) that can better withstand shocks and funding pressure.
- Hunt for mispriced quality by reviewing a 201 high quality undervalued stocks that filters for strong fundamentals at appealing valuations.
- Lock in potential income streams by assessing a 227 dividend fortresses that focuses on higher yielding payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com