


EN
Berkshire Stock Just Hit a Record High. Don’t Back Up the Truck at the Top.
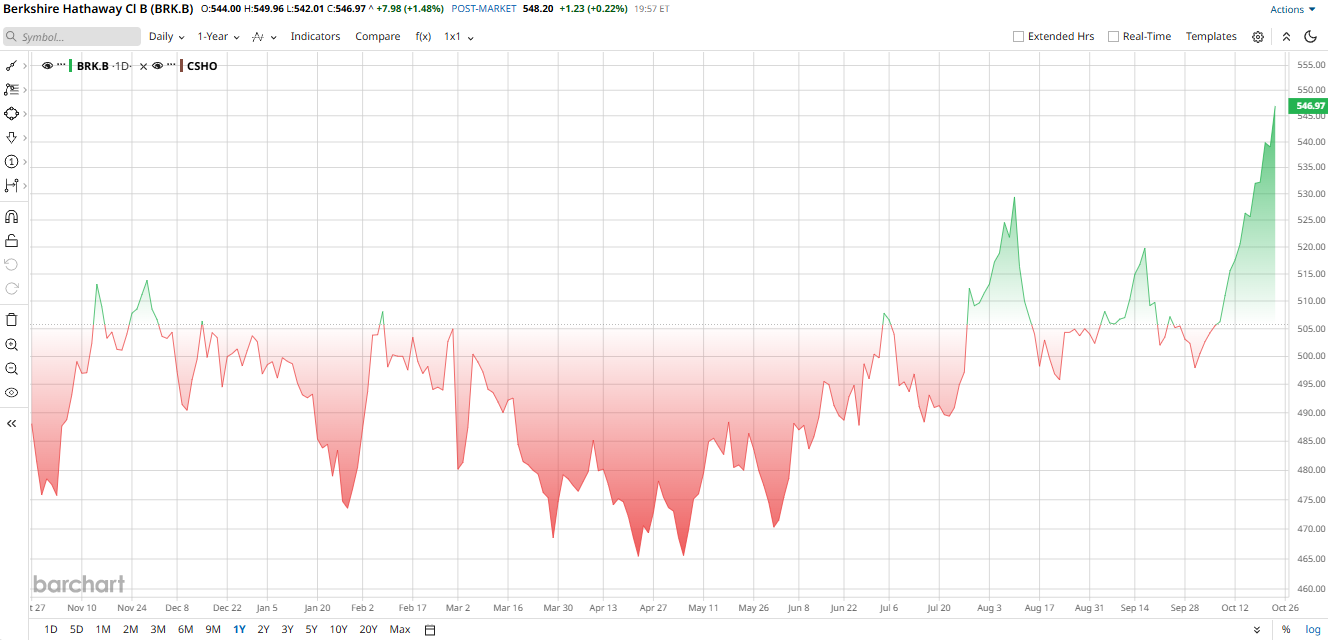
Berkshire Hathaway (BRK.A) (BRK.B) shares just touched a fresh all-time high this week. That is a massive moment for the company. For months, investors worried about life after Warren Buffett. The stock badly lagged the market in 2025. Greg Abel took over as CEO on Jan. 1, 2026. Many wondered if the magic was gone.
Fast forward to late October 2026. The stock is back near the top. Abel is putting Berkshire's massive cash pile to work. He is buying whole companies, taking big stakes in tech, and repurchasing Berkshire stock hand over fist. The market likes what it sees.
Shares of BRK.B have risen only about 8% year-to-date (YTD). So why the record high now? The answer is confidence. Investors are finally warming up to Abel. He is not Buffett. But he is decisive. And he is deploying capital in ways Buffett refused to for years.
The Valuation Is Not a Steal
Let's be honest. Berkshire is not cheap anymore. The stock trades at a price-to-book ratio of about 1.44. That is slightly above the industry average. It is also above the three-year median. The forward price-to-earnings ratio sits near 24.7. The sector median is closer to 12. So this is not a deep-value play. You are paying a fair price for a great business. Not a bargain price.
Abel Is Putting the Cash to Work
This is what actually happened. During Buffett's tenure, Berkshire was endowed with a surplus of cash. Investors hated it. It's only in the second quarter that Abel entered the game and turned things around. Berkshire was a net acquirer of stock for the first time over the last 14 quarters. It purchased $23.5 billion worth of stocks and sold $3.7 billion.
Their largest movements are indicators. Abel has already closed a $6.8 billion acquisition of home builder group Taylor Morrison. He invested $10 billion by raising $10 billion via a private placement in Alphabet (GOOG) (GOOGL). Which is why Alphabet was one of Berkshire's best-kept stocks. He has also repurchased $4.5 billion of Berkshire's shares. In October, Berkshire added another $330 million to its Bending Spoons (BSP) stake.
CEO Greg Abel has a straightforward mantra: “dry powder.” He became strongly associated with the term from his first shareholder letter regarding Berkshire's cash position. He also stated that they will always be striving to acquire ownership of productive businesses over U.S. Treasuries. And he's doing just that. Buffett might not have seen the value in everything that Abel saw, but unlike his predecessor, he is willing to pay to grow! That's the catalyst that the market is finally factoring in.
The Quarter Was a Blowout
Berkshire reported second-quarter 2026 results on Aug. 8, and the numbers were strong across the board.
Total revenue came in at $101.8 billion. That was up 10% from the same quarter last year. The insurance and other segment led the way with $88.5 billion in revenue, up 10% year-over-year (YoY).
Net income more than doubled to $25.67 billion. That is up from $12.37 billion a year earlier. Operating earnings rose 16% to $12.98 billion. Adjusted operating earnings per share came in at $6.02. That crushed the consensus estimate of $5.24. The beat was nearly 15%.
Cash and cash equivalents stood at $35.1 billion at the end of June. Add short-term Treasury bills, and Berkshire's total liquidity was around $365 billion. That is a staggering war chest.
Guidance looks steady. Analysts expect third-quarter revenue near $100.9 billion and earnings per share of about $5.91. For the full year 2026, the consensus revenue estimate is $403.5 billion. The full-year EPS estimate sits around $21.8 per share.
What the Analysts Are Saying About Berkshire Stock
Wall Street is warming up, but the crowd is not fully on board yet.
UBS is the most bullish voice. Analyst Brian Meredith raised the price target to $628 from $604 on Oct. 22. He kept a “Buy” rating. That implies an upside of nearly 15% from recent prices.
DA Davidson also likes the stock. The firm lifted its target to $592 from $531 and maintained a “Buy” rating.
Argus Research rounds out the group with a “Buy” rating.
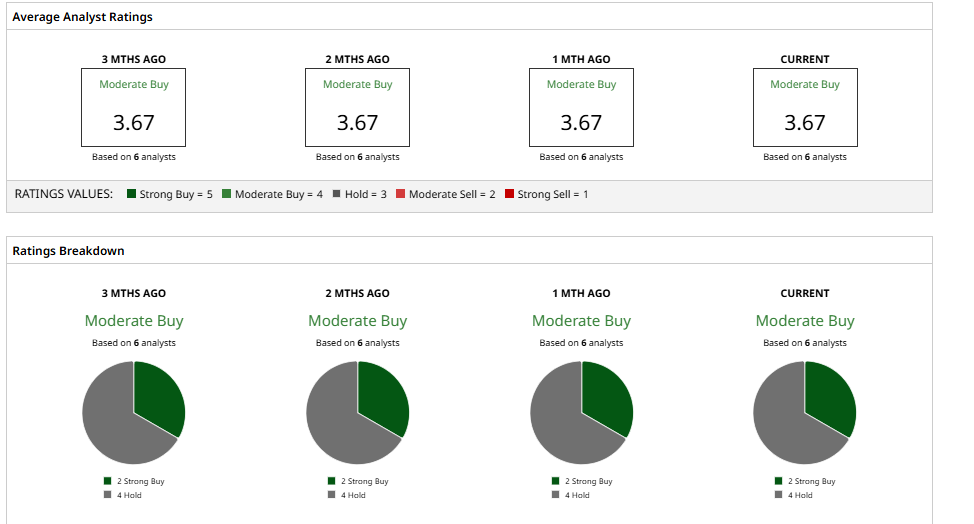
Analysts put the company at a “Moderate Buy” consensus. The average price target is $542. That is barely down from the current price of around $547. The high target is $604. The low is $500. So the message is mixed. Analysts like the business. But most do not see a considerable margin of safety at today's levels, as the stock has caught up to their fair-value estimates.
The Bottom Line
Berkshire is a better-run company today than it was a year ago. Abel is proving he can allocate capital. The balance sheet is still Fort Knox.
But the stock is no longer a hidden gem. It trades at a premium to its own history on some metrics. The easy re-rating trade has happened. If you already own Berkshire, there is no urgent reason to sell. The long-term story is intact. If you are thinking about buying, consider dollar-cost averaging. Do not back up the truck at a record high. The company is great. The price is fair. That is not the same thing as a bargain.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.