


EN
Does Product Upgrade Change The Bull Case For Qualys (QLYS)?
- Qualys released TruRisk Eliminate 2.0 with TruConfidence, an AI-driven remediation intelligence engine designed to automate cyber risk actions across hybrid environments using data from hundreds of millions of prior patch deployments.
- The launch formalizes Qualys' push into Autonomous RemOps. AI agents and orchestration are intended to help cut exposure while reducing duplicate controls and operational disruption.
- This article examines how Qualys' investment narrative is affected by TruRisk Eliminate 2.0 and its AI-driven Autonomous RemOps focus.
Scan how Qualys' Autonomous RemOps push fits into a wider security and AI story by lining it up against 38 profitable AI stocks that aren't just burning cash already executing on real-world demand.
Qualys Investment Narrative Recap
To own Qualys, you need to believe that its TruRisk platform, Agentic AI efforts and now Autonomous RemOps can turn a mid single digit revenue trajectory into durable, high margin security operations at scale. The key near term swing factor is whether this broader risk operations story converts into stronger new logo activity and deeper adoption within existing customers.
TruRisk Eliminate 2.0 supports that pitch by pushing Qualys further into outcome focused remediation across hybrid environments. The launch does not remove the biggest risks. AI security remains highly competitive, billings expectations stay in the high single digit range and heavy insider selling over the past year may continue to cap how much credit investors give execution wins.
Against this TruRisk Eliminate news, the earlier launch of the cloud native risk operations center and Agentic AI platform matters most. That initiative is meant to unify data, orchestration and automation across both Qualys and third party signals, which ties directly into the Autonomous RemOps promise of acting on risk at scale rather than just reporting on it.
If customers start using the risk operations center as the primary control plane, TruRisk Eliminate 2.0 looks less like a standalone module and more like a crucial workflow inside a broader operating model. A potential positive outcome would be higher average revenue per customer, stronger net dollar expansion and better leverage on already high EBITDA margins. The execution risk is that competing AI led security platforms move faster and reduce any platform advantage before it appears in billings and earnings.
What TruRisk Eliminate Means Against Current Qualys Forecasts
Qualys' TruRisk Eliminate story sits on top of a fairly specific analyst model. Forecasts point to revenue rising at about 7.4% a year over the next three years, with profit margins easing from 29.4% today to 25.9% by 2029. On that math, the business is expected to move from current earnings of $206.5 million to consensus earnings of $225.7 million in 2029, which is an earnings increase of roughly $19.2 million, even though some analysts see potential for as much as $258.9 million. Those same projections anchor on 2029 revenue of $871.6 million and assume a P/E of 31.9x on those earnings, compared with 33.2x today and a US Software sector P/E of 30.6x, with the share count modeled to fall about 3.52% each year over the next three years.
On the valuation side, the analyst framework effectively asks investors to weigh TruRisk Eliminate and Autonomous RemOps execution against a defined 2029 destination. The consensus view points to revenue of $871.6 million and earnings of $225.7 million in that year, discounted back using a rate around 8.6%. Price targets cluster around $181.03 per share, with a range from $130.00 to $220.00, compared with a current price of $198.11. This implies analysts on average see the stock as roughly fairly priced on their assumptions rather than deeply misvalued.
Qualys' current analyst consensus points to revenues of $871.6 million and earnings of $225.7 million by 2029, which implies about 7.4% yearly revenue growth and an earnings increase of roughly $19.2 million from $206.5 million today.
Uncover why Qualys' fair value indicates a 13% potential downside to its current price, which leaves little room for error.
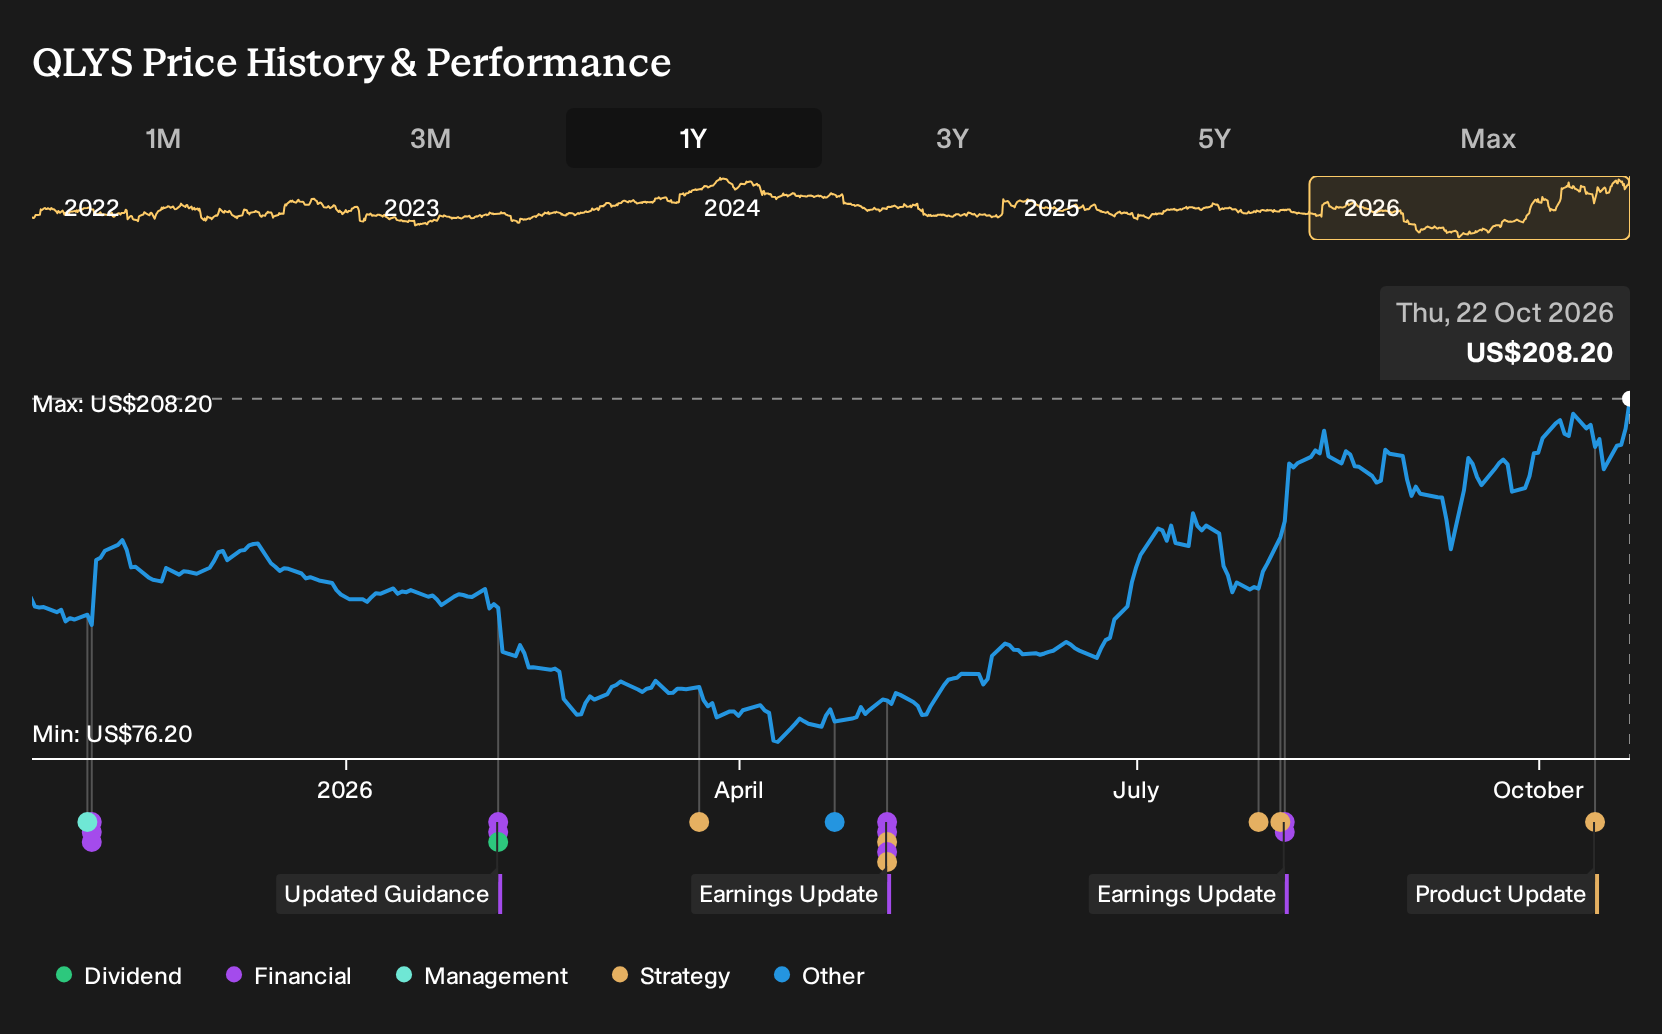
Exploring Other Perspectives
One bullish twist you might explore is how the most optimistic analysts already framed Qualys as an underappreciated AI risk operations play. Before this TruRisk Eliminate 2.0 launch, that group was penciling in about $934.6 million of 2029 revenue and $258.5 million of earnings. Those richer forecasts may shift again as this new product settles in.
Explore 2 other Qualys fair value estimates, including one that suggests potential upside of as much as 12% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Qualys research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Qualys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qualys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Qualys?
If TruRisk Eliminate 2.0 has sharpened your view on Qualys but you still want a broader watchlist, it can help to line up similar quality filters across other companies and see how they stack up side by side.
- For investors who want potential mispricings with solid fundamentals, start with a focused group of 29 high quality undervalued stocks that already clear strict quality checks.
- If capital preservation sits high on your priority list, use a curated universe of 30 resilient stocks with low risk scores to look for businesses with more resilient profiles.
- When you care about balance sheet strength as much as the income statement, filter for a list of solid balance sheet and fundamentals (26 results) and see which companies pair financial stability with cleaner fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com