


EN
Is Balchem (BCPC) Undervalued On Its Dividend Reset And Q3 Earnings Focus?
Dividend update and upcoming earnings focus attention on Balchem
Balchem (BCPC) has set an annual dividend of $0.3984 per share, payable on January 15, 2027, with an ex dividend and record date on December 31, 2026, drawing attention to its income profile.
Recent trading has been constructive for Balchem, with a 1-month share price return of 2.87% and a 90-day move of 6.40% helping lift the year-to-date share price gain to 12.47% at a last close of $173.23. The 3-year total shareholder return of 44.77% points to momentum that has built over a longer stretch and sets the backdrop for both the dividend reset and the upcoming Q3 2026 earnings update on October 23.
Scan how Balchem compares by lining up its dividend reset and earnings date against a hand picked 6 dividend fortresses for income focused investors.
After a steady climb in Balchem, supported by a richer income profile and upcoming Q3 numbers, the real puzzle now sits in the price tag. Does the current risk reward still lean toward buyers?
Most Popular Narrative: 17% Undervalued
Balchem's most followed valuation storyline pegs fair value at $209.25 against the recent $173.23 share price. The current dividend reset and Q3 earnings date therefore land against a backdrop of a stock that this framework treats as priced below its assessed worth using a 7.3% discount rate.
The numbers and current valuation together indicate that Balchem’s share price may not fully reflect the company’s record revenue, consistent adjusted EBITDA, and balance sheet capacity for reinvestment and buybacks.
The expanded US$650 million revolving credit facility, low net leverage of 0.3x and ongoing share repurchases give Balchem financial flexibility to fund additional product development, capacity projects and acquisitions that can add to future revenue and adjusted EBITDA.
See why 2 investors see Balchem as 17% undervalued.
Result: Fair Value of $209.25 (UNDERVALUED)
Still, two weak spots can quickly upset the Balchem story: a reversal in EU choline duties that hits Animal Nutrition economics and stubborn petrochemical and freight costs that squeeze margins.
Find out about the key risks to this Balchem narrative.
Another View: Balchem on earnings multiples
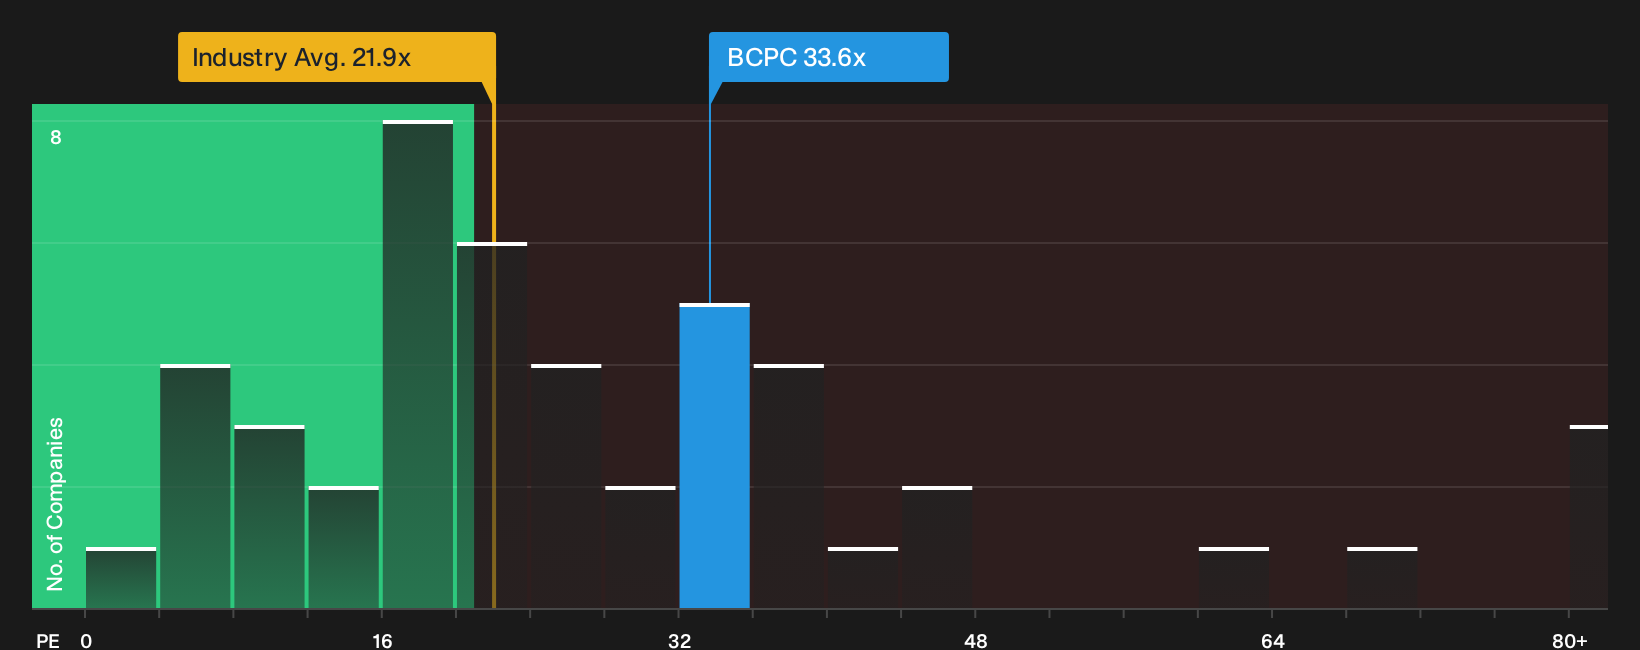
Balchem screens as undervalued on fair value models, yet the simple earnings multiple tells a tougher story. The stock trades on a P/E of 33.6x, compared with 22x for the US Chemicals industry and a fair ratio of 15.8x that the market could move toward. Is that premium headroom or valuation risk for you?
To pressure test that richer earnings multiple against detailed valuation work, take a look at the breakdown in our ratio based approach. Then weigh how much of Balchem's story you think is already in the price with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Balchem story points to optimism, yet the verdict is still yours. Move quickly from reading to testing the numbers yourself, and weigh both the upside signals and the valuation debate with 4 key rewards
Looking for more Balchem sized opportunities?
If Balchem has sharpened your thinking, do not stop here. Broaden your watchlist with focused stock ideas built from clear metrics and disciplined filters.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing valuations using the 29 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with clean finances and sturdy fundamentals through the list of solid balance sheet and fundamentals (26 results).
- Aim earlier in the story by reviewing a curated 20 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com