


EN
Advance Residence Investment (TSE:3269) Could Be 20% Undervalued As Cash Flow Questions Grow
Fresh scrutiny of Advance Residence Investment (TSE:3269) has been sparked by questions around how securely its rental income and property cash flows support today’s unit price, along with flagged warning signs that are prompting a more cautious investor stance.
At a latest share price of ¥133,500, Advance Residence Investment has seen its 30 day share price return fall 4.3% and its year to date share price return decline 22.7%, while the 1 year total shareholder return is down 17.7%, pointing to fading momentum as investors reassess rental income resilience and the recently flagged warning signs.
Scan the residential REIT space beyond Advance Residence Investment by lining up its recent slide against a hand-picked 22 resilient stocks with low risk scores that aim to keep cash flows and balance sheets resilient.
The recent slide in Advance Residence Investment raises a simple tension. Has the weaker unit price reset expectations enough, or has most of the potential re rating already happened in the cash flows the market is willing to pay for today?
Most Popular Narrative: 20% Undervalued
Based on the numbers in front of you, the popular narrative pegs Advance Residence Investment’s fair value around ¥166,714 per unit versus a last close of ¥133,500. That gap puts the focus squarely on whether its rent driven cash flows and balance sheet discipline can support that higher figure over time.
The main factor that has to go right is that Advance Residence Investment continues to convert strong urban rental demand and its value add remodeling and asset replacement programs into higher replacement rents and profitable internal growth, despite higher funding costs.
The current valuation suggests the share price does not fully reflect this narrative’s view that Advance Residence Investment is undervalued and that its rent driven FFO growth, disciplined LTV near 50%, and younger portfolio could support more resilient cash flows than the market is pricing in.
See why 1 investors see Advance Residence Investment as 20% undervalued.
Result: Fair Value of ¥166,714 (UNDERVALUED)
Still, the case around Advance Residence Investment can unravel quickly if higher floating rate debt keeps lifting funding costs, or if property sale gains dry up faster than expected.
Find out about the key risks to this Advance Residence Investment narrative.
Another View: Multiples Push Back On The DCF Story For Advance Residence Investment
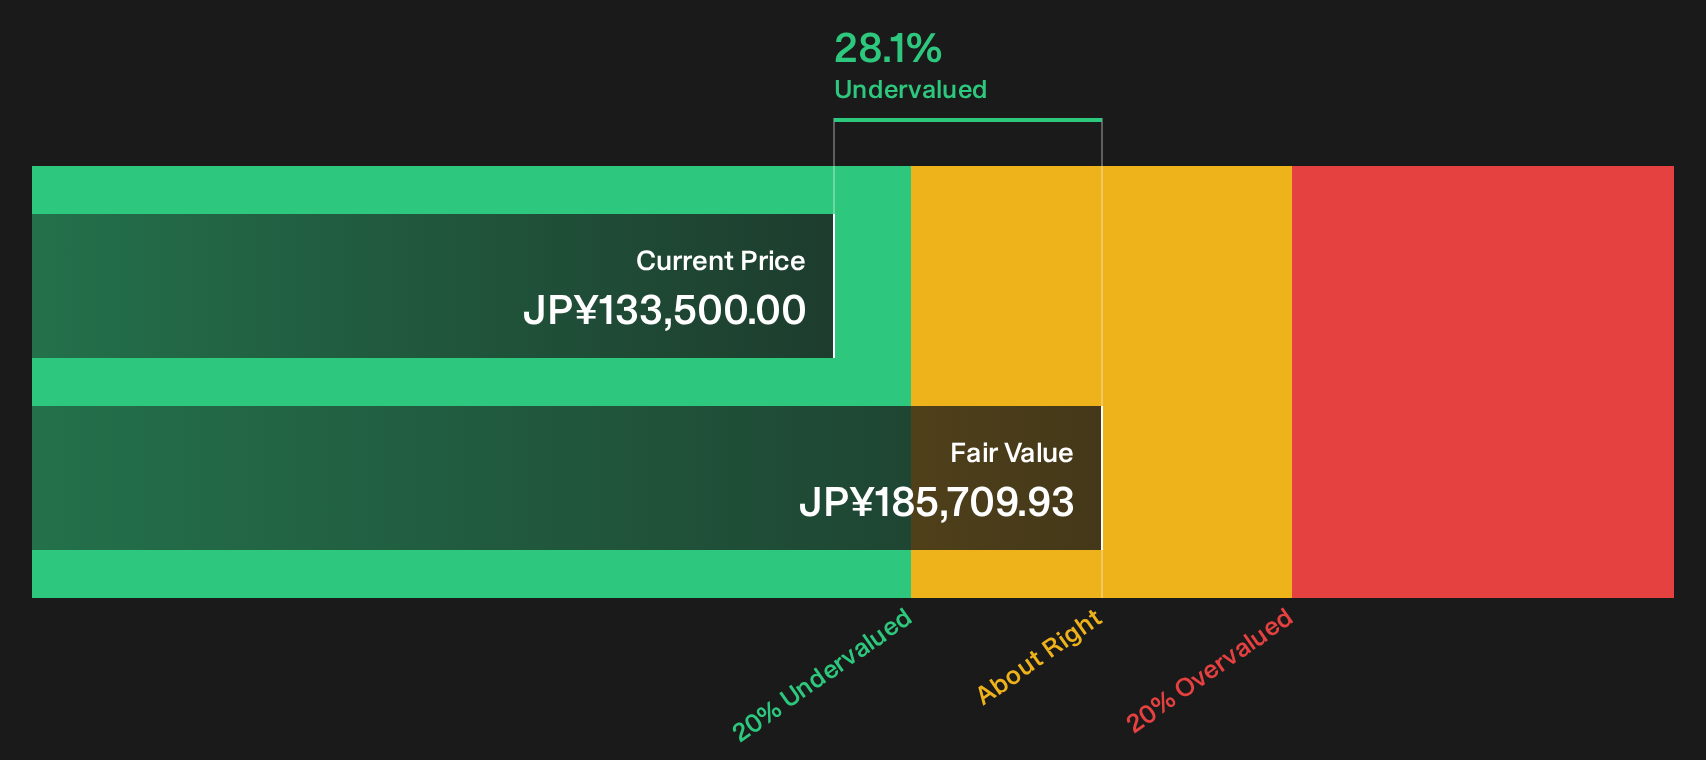
The SWS DCF model points to Advance Residence Investment trading below an estimated future cash flow value of ¥185,709.93 per unit, which supports the undervalued narrative. The P/E picture is less forgiving though. At 21.2x, the units change hands above both peer average at 17.6x and the Global Residential REITs group at 18.5x, and even above a fair ratio of 20.2x. That richer earnings tag can quickly eat into any perceived cushion from cash flow models. The key question is how much multiple risk you are really comfortable carrying if sentiment turns again.
To pressure test that question against a full set of cash flow assumptions, walk through the SWS DCF model next Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the numbers and sentiment can feel uncomfortable, so move quickly, review the data independently, and consider both sides of the story by checking the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Advance Residence Investment?
If you stop here, you only see one slice of the market. Put a fuller watchlist together by scanning other setups with solid balance sheets, income strength, or mispriced potential.
- Spot potential mispricings before the crowd by reviewing a curated 15 high quality undervalued stocks that pairs balance sheet strength with earnings quality signals.
- Build a steadier income stream by reviewing a focused 29 dividend fortresses built around higher yielding payouts backed by measurable fundamentals.
- Prioritise staying power in tougher markets by filtering for a list of solid balance sheet and fundamentals (23 results) that screens for robust financial positions and cleaner leverage profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com